
Investigator Payment Management Solutions Market Report Scope & Overview:
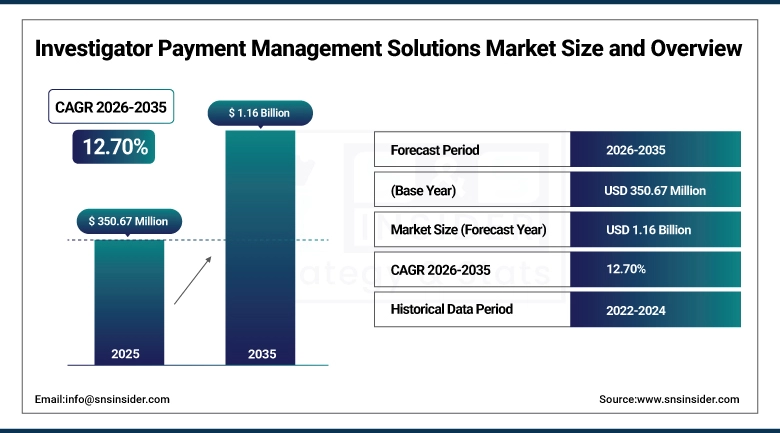
The Investigator Payment Management Solutions Market was valued at USD 350.67 Million in 2025 and is expected to reach USD 1.16 Billion by 2035, growing at a CAGR of 12.70% from 2026-2035.
The Investigator Payment Management Solutions Market is growing as sponsors and contract research organizations move away from manual, check-based investigator and site payment processes toward dedicated software. Multi-country trials raise the administrative burden of calculating, approving and reconciling payments across currencies and tax regimes. Vendors are combining budgeting, multi-currency payment and audit-trail functions into single platforms to cut delays at the site level. Consolidation among payment-focused technology providers is concentrating capability in fewer, broader platforms. Cloud deployment is gaining preference over on-premise installations, which shortens implementation for distributed site networks. Demand from multi-regional late-phase studies is projected to keep the market on a steady growth path through 2035.
In September 2025, IQVIA launched its Clinical Trial Financial Suite to give sponsors a single platform for calculating and distributing investigator and site payments across studies. The launch shows how established eClinical vendors are consolidating payment functionality once handled by separate point solutions.
To Get more information On Investigator Payment Management Solutions Market - Request Free Sample Report
Investigator Payment Management Solutions Market Trends
-
Cloud-based deployment is replacing on-premise installations across sponsor and CRO payment platforms.
-
Artificial intelligence is being used to read site invoices and match them automatically to budget categories.
-
Regulatory scrutiny of cross-border investigator payments for tax withholding and anti-corruption compliance is increasing in several jurisdictions.
-
Multi-currency and cross-border payment capability is becoming a baseline requirement for global trials.
-
Fee-free participant and investigator payment cards are gaining adoption to widen site participation.
-
Sponsors are integrating payment platforms directly with clinical trial budgeting and management systems.
U.S. Investigator Payment Management Solutions Market Outlook
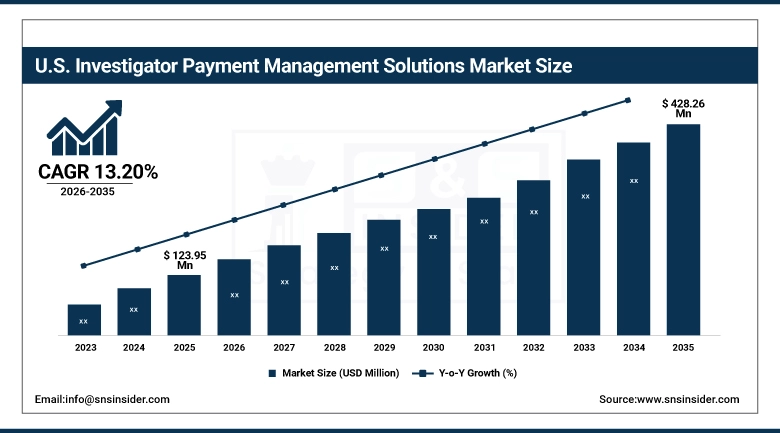
The U.S. Investigator Payment Management Solutions Market was valued at USD 123.95 Million in 2025 and is expected to reach USD 428.26 Million by 2035, growing at a CAGR of 13.20% from 2026-2035.
The U.S. Investigator Payment Management Solutions Market remains the largest national contributor to global demand. A concentration of payment-technology vendors headquartered in the country keeps adoption ahead of other markets. Large pharmaceutical sponsors and academic medical centers run multi-site studies that require fast, auditable investigator and site payments. Venture-backed entrants are building artificial intelligence into invoice processing to cut the administrative load on site staff. Large pharmaceutical sponsors increasingly require payment vendors to hold SOC 2 or HITRUST certification before approving a platform for enterprise-wide use. Academic research institutes and federally funded trial networks add further demand for compliant grant payment tracking. The market is projected to keep expanding steadily through 2035 as sponsors replace manual payment processes with automated platforms.
⮞In April 2026, Ledger Run upgraded its ClinRun platform with artificial intelligence that reads site invoices and matches them to budget categories, a system used by roughly 17,000 trial sites worldwide. The upgrade reflects growing sponsor demand for automated investigator payment processing in the country.
Investigator Payment Management Solutions Market Segment Analysis
-
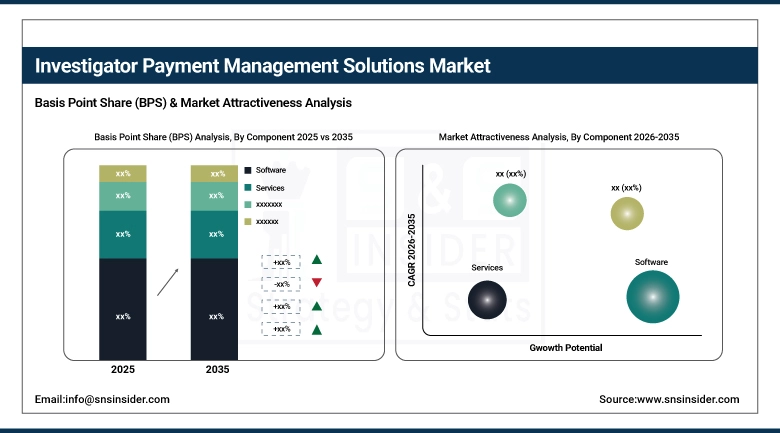
By Component, the Software segment dominated the Investigator Payment Management Solutions Market with approximately 66.27% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 14.20%.
-
By Deployment Mode, the Cloud-based segment dominated the Investigator Payment Management Solutions Market with approximately 61.50% share in 2025 and is also the fastest growing with a CAGR of approximately 13.80%.
-
By Functionality, the Payment Calculation and Automation segment dominated the Investigator Payment Management Solutions Market with approximately 13.90% share in 2025, while the Multi-Currency and Cross-Border Payment Management segment is the fastest growing with a CAGR of approximately 14.70%.
-
By End Use, the Pharmaceutical and Biotechnology Companies segment dominated the Investigator Payment Management Solutions Market with approximately 51.10% share in 2025, while the Contract Research Organizations segment is the fastest growing with a CAGR of approximately 14.00%.
-
By Payment Type, the Site Payments segment dominated the Investigator Payment Management Solutions Market with approximately 21.90% share in 2025, while the Performance and Milestone-Based Payments segment is the fastest growing with a CAGR of approximately 15.00%.
By Component, Software Dominates the Investigator Payment Management Solutions Market and Services Grows Fastest
Software anchors the component split, as sponsors and CROs need a system of record that calculates, approves and reconciles payments across every site in a study. Licensed platforms integrate with clinical trial management and finance systems, which reduces duplicate data entry and shortens the time between a site visit and payment release. Vendors continue to add budgeting, multi-currency and audit-trail modules directly into their core software rather than through separate tools. Combining these functions in one system raises the cost of switching to a different platform and favors established vendors with broad feature sets.
Services are growing at the faster pace as sponsors rely on implementation, configuration and managed payment-operations support to launch new platforms quickly. Smaller sponsors and academic research institutes often lack in-house staff to manage currency compliance and tax reporting, so they outsource these functions to specialist service teams. Consulting support around data migration from legacy spreadsheets and manual processes is in especially high demand during platform transitions. Vendors that bundle managed services with their software are capturing more of this growth.
⮞In April 2025, Suvoda completed its merger with Greenphire, combining Greenphire's clinical trial payment and financial technology with Suvoda's randomization and supply platforms. The deal illustrates how software vendors are absorbing services and support capability through consolidation rather than building it independently.
By Deployment Mode, Cloud-based Dominates the Investigator Payment Management Solutions Market and Also Grows Fastest
Cloud-based deployment leads, as it lets sponsors onboard new studies and sites without installing software locally at every location. Centralized hosting simplifies version control and lets vendors push compliance updates across all client studies at once, which matters as tax and currency rules change across jurisdictions. Remote and hybrid clinical trial teams can access payment dashboards from any site without a dedicated local server. Cloud platforms also integrate more easily with other cloud-native clinical systems, including electronic data capture and clinical trial management tools.
The format is also the fastest growing, as new sponsors and smaller CROs default to cloud options when selecting a platform for the first time, avoiding the upfront infrastructure cost of an on-premise system. Legacy on-premise installations at larger, longer-established sponsors are being migrated as contracts renew. Vendors are increasingly declining to support new on-premise implementations, which pushes the remaining base toward the cloud over time. Security certifications and data residency options have reduced the hesitation some sponsors previously had about hosting payment data off-site.
⮞In 2024, China registered 4,900 clinical trials, an increase of 13.9% from the prior year, a volume that increasingly runs on cloud-hosted trial systems to coordinate sites across the country. The scale of this growth adds to the case for platforms that can be deployed quickly across new geographies without local infrastructure.
By Functionality, Payment Calculation and Automation Dominates the Investigator Payment Management Solutions Market and Multi-Currency and Cross-Border Payment Management Grows Fastest
Payment calculation and automation leads, serving as the core function every sponsor needs regardless of study size, applying visit schedules and budget rules to generate accurate investigator and site payments without manual spreadsheet work. Automating this step reduces common errors such as duplicate payments or missed milestones that previously required manual audits. The function also feeds directly into financial reporting, which sponsors need for internal controls and external audit purposes. Since it touches every payment cycle, vendors treat it as the anchor module around which other functionality is sold.
Multi-currency and cross-border payment management is growing fastest as trials expand into more countries simultaneously, each with its own currency, tax withholding and banking requirements. Sponsors running programs across Asia Pacific, Europe and Latin America need a single platform that can calculate local withholding tax and settle payments in local currency without manual conversion. Regulatory scrutiny of cross-border payments to investigators has increased, which pushes sponsors toward systems with built-in compliance checks rather than informal wire transfers.
By End Use, Pharmaceutical and Biotechnology Companies Dominate the Investigator Payment Management Solutions Market and Contract Research Organizations Grow Fastest
Pharmaceutical and biotechnology sponsors dominate end use, as they fund the large majority of late-phase trials and carry direct financial and regulatory responsibility for investigator and participant payments. Large pharmaceutical companies standardize a single payment platform across their global trial portfolio to simplify audit and reporting. Biotechnology companies, often running fewer but higher-stakes studies, favor configurable platforms that scale from early-phase to pivotal trials without a platform change. Both groups increasingly require payment systems that integrate with enterprise finance software for consolidated reporting.
Contract research organizations are adopting payment platforms at the fastest pace as sponsors increasingly outsource full trial operations, including financial administration, to a single CRO partner. CROs that offer integrated payment management as part of their service package can differentiate from competitors that still rely on manual processes. Running payments across many sponsor studies at once gives CROs an incentive to standardize on one platform rather than using whatever system each sponsor prefers. This consolidation is expanding the installed base of enterprise-wide licenses across the CRO segment.
⮞In March 2025, ICON, a contract research organization, began using Mural Health's Mural Link platform to manage participant and site payments across its studies, adopting a fee-free payment card intended to widen the pool of patients able to take part. The adoption shows how CROs are turning to dedicated payment vendors rather than building the capability internally.
By Payment Type, Site Payments Dominate the Investigator Payment Management Solutions Market and Performance and Milestone-Based Payments Grow Fastest
Site payments make up the largest share of payment volume, as every active trial site, regardless of enrollment, receives recurring payments for overhead, staff time and procedure costs tied to protocol visits. These payments occur on a continuous cycle throughout a study, unlike one-time grant disbursements, which keeps transaction volume high. Sponsors prioritize automating this payment type first, since delays in site payments are a recognized driver of investigator dissatisfaction and slower recruitment. Platforms that can process site payments quickly after a monitoring visit shortens the overall payment cycle sponsors must manage.
Performance and milestone-based payments are growing fastest as sponsors shift away from flat per-visit fees toward structures that reward enrollment speed, data quality and protocol adherence. This approach ties investigator compensation more closely to trial outcomes that sponsors care about, rather than simple attendance at a scheduled visit. Calculating these payments is more complex, since it depends on variable performance metrics rather than a fixed visit schedule, which increases demand for software that can apply milestone rules automatically. Sponsors view the structure as a way to improve recruitment timelines without raising overall payment budgets.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
76.84% |
|
Europe |
United Kingdom |
24.37% |
|
Asia Pacific |
China |
33.92% |
|
Middle East and Africa |
Saudi Arabia |
29.15% |
|
Latin America |
Brazil |
48.63% |
North America Investigator Payment Management Solutions Market Insights
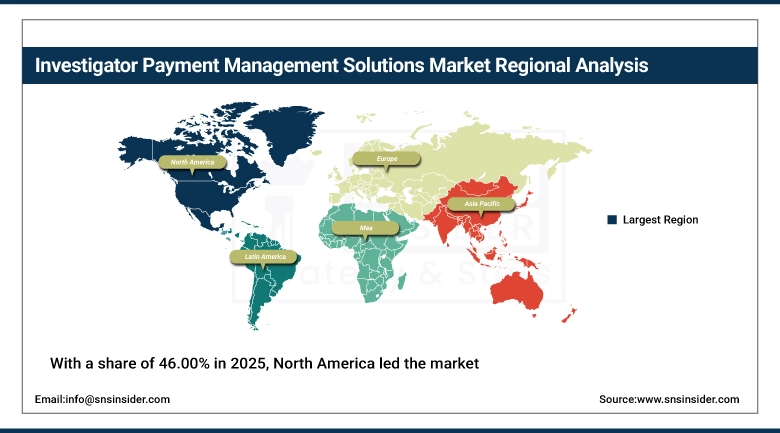
With a share of 46.00% in 2025, North America led the market, supported by the largest concentration of dedicated payment-technology vendors and a dense network of late-phase trial sponsors. The United States accounts for most regional activity, driven by large pharmaceutical headquarters and academic medical centers running multi-site programs. Canada contributes through its own research institutions and cross-border trial participation with the United States. Established contract research organizations based in the region standardize payment platforms across their global client base.
Venture investment in payment-focused clinical technology companies remains concentrated in North America, supporting a steady pipeline of new entrants alongside established platforms. Sponsors in the region are early adopters of artificial intelligence for invoice processing and budget reconciliation. Enterprise procurement teams at large North American sponsors increasingly require SOC 2 or HITRUST security certification before approving a new payment vendor for multi-study use. Regulatory requirements around tax withholding and anti-corruption compliance for investigator payments are well established in the region, giving vendors a mature compliance framework to build around.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Investigator Payment Management Solutions Market Insights
Europe holds the second-largest position in the market, supported by harmonized clinical trial rules across the European Union and a dense base of academic and commercial trial sponsors. The United Kingdom, Germany and France host the largest concentrations of trial sites among European countries. Multinational sponsors running studies across several European countries need payment platforms that can handle differing national tax and currency requirements within a single region. National health systems and publicly funded research institutes add further demand for compliant, auditable grant payment tracking.
Regulatory harmonization under the European Union's Clinical Trials Regulation is simplifying multinational trial submissions, which indirectly supports payment platforms designed to operate across several countries from one system. Sponsors in the region are also subject to strict data protection requirements that shape how payment platforms store and transmit site and investigator banking information. Smaller national markets within Europe continue to rely more heavily on manual payment processes than the largest countries, reflecting a more mature base of platform adoption than in emerging markets.
⮞The European Medicines Agency confirmed that the Clinical Trials Regulation became fully applicable across the European Union in January 2025, ending the transition period for sponsors submitting multinational trial applications. The change supports platforms built to manage payments consistently across the harmonized submission framework.
Asia Pacific Investigator Payment Management Solutions Market Insights
Asia Pacific is the fastest-growing region and is projected to expand at a CAGR of approximately 15.10% from 2026 to 2035. Rising clinical trial volumes in China, India, Japan and South Korea are increasing the number of sites and investigators that require timely, compliant payments. Sponsors running China-inclusive and India-inclusive trial programs face a wider range of currency and tax requirements than in more established markets, increasing reliance on dedicated payment software rather than manual processes.
Regulatory reform across several countries is shortening the gap between trial approval in the region and in established markets, encouraging sponsors to run more studies locally rather than relying solely on bridging data. Investment in local research infrastructure is also improving the capacity of academic and hospital-based sites to manage trial administration, including payments, without relying entirely on sponsor-side staff. Local vendors and global platforms are both expanding sales efforts in the region as adoption rises from a comparatively low base.
⮞The Information Technology and Innovation Foundation reported in June 2025 that China registered about 7,100 drug clinical trials in 2024 compared with about 6,000 in the United States, overtaking the country long seen as the largest trial market. A shift of this scale in trial volume adds directly to the number of sites and investigators requiring payment administration across the region.
MEA & Latin America Investigator Payment Management Solutions Market Insights
The Middle East and Africa is a smaller but emerging market. Gulf countries are investing in hospital research capacity and clinical trial regulation to attract international sponsors, which is gradually increasing demand for compliant payment infrastructure at newly accredited sites. South Africa remains the most established trial market on the continent, supported by experienced investigators and research networks built up over several decades. Limited local vendor presence means most platforms used in the region are deployed by global sponsors and CROs rather than sold locally.
Latin America contributes through large patient populations and experienced investigators in Brazil, Argentina and Mexico, where sponsors value rapid enrollment for cardiovascular, metabolic and infectious disease studies. Currency volatility and import or banking restrictions in some countries complicate cross-border payment settlement, reinforcing demand for platforms with local payment rails and compliance handling. Growth in both regions remains at an earlier stage than in North America, Europe or Asia Pacific, with adoption concentrated among larger, internationally sponsored studies.
Market Dynamics
Growth Drivers: Rising trial complexity and site payment modernization
The most important driver is the growing number and complexity of multi-country clinical trials, which raises the administrative burden of calculating and distributing investigator, site and grant payments on time. Sponsors increasingly treat payment delays as a recruitment and retention risk, since sites that wait months for reimbursement are less willing to prioritize new studies. Regulatory scrutiny of cross-border payments to investigators is also pushing sponsors toward auditable software rather than manual wire transfers and spreadsheets.
A second driver is the broader shift toward outsourcing trial operations, including financial administration, to contract research organizations and specialist vendors. CROs that standardize payment platforms across their sponsor base can run more studies without proportionally increasing finance staff. Growth in the number of active trial sites worldwide, including a sharp rise in Asia Pacific registrations, is directly expanding the base of payments that need to be processed. Growing adoption of milestone- and performance-based investigator compensation structures is also increasing the computational complexity that vendors must support.
⮞Medidata launched Patient Payments in September 2024, a tool built on its platform that automates stipends and reimbursements for travel, meals, lodging and other study-related expenses, triggered directly by completed study activities. The launch illustrates how established eClinical vendors are extending automation from site payments into the patient-facing side of trial finance.
Restraints: Fragmented systems, integration complexity and manual processes
A persistent restraint is the continued reliance on manual, spreadsheet-based payment processes at smaller sponsors, academic institutes and independent sites, which slows platform adoption even where the benefits are well understood. Integrating a new payment platform with existing clinical trial management, finance and tax-reporting systems can take months and requires coordination across sponsor, CRO and site teams. Smaller organizations often lack dedicated information technology staff to manage this integration, which lengthens implementation timelines and raises switching costs once a system is in place.
Data security and privacy requirements for storing investigator and participant banking details add further complexity, particularly for platforms operating across multiple countries with different data protection regimes. Smaller vendors face pressure to meet the same compliance standards as larger competitors without equivalent resources, which can slow their ability to win sponsor business. Resistance to changing established payment workflows at some larger, longer-established sponsors also limits how quickly the installed base of manual processes converts to software.
Opportunities: Artificial intelligence and emerging-market expansion
Artificial intelligence offers the clearest opportunity, with vendors building automated invoice reading, budget-category matching and anomaly detection directly into payment platforms. These capabilities can cut the manual review time sponsors and sites spend reconciling payments, which addresses one of the market's most cited restraints. Vendors that successfully combine automation with existing compliance and audit-trail functionality can differentiate from competitors still relying on manual review steps. Early deployments covering tens of thousands of trial sites suggest meaningful room for broader rollout across the installed base.
Expansion into Asia Pacific, Latin America and the Middle East presents a further opportunity as trial volumes in these regions grow faster than in established markets. Vendors that build local currency, tax and banking support into their platforms can capture demand from sponsors running China-inclusive and India-inclusive studies without relying on manual local workarounds. Partnerships between global payment platforms and regional CROs can accelerate market entry without the cost of building local sales infrastructure from scratch.
⮞India's Clinical Trials Registry recorded about 18,000 new trial registrations in 2024, a rise of roughly 50% from the prior year, pointing to a rapidly expanding base of sites and investigators that will increasingly need dedicated payment administration. Growth at this pace represents a substantial addressable opportunity for vendors expanding into the region.
Recent Developments:
-
In May 2025, Greenphire’s GreenSpace patient engagement hub won the MedTech Breakthrough Award for Best Patient Portal, recognizing its integrated payment-choice, receipt-upload, travel-coordination and support-alert features. The recognition followed Greenphire’s 2025 merger with Suvoda, pairing investigator and site payment technology with randomization and trial supply management on a single platform, and signals continued investment in participant-facing payment tools as the combined company integrates its broader product line.
-
In November 2025, Sitero acquired the artificial intelligence assets and business of studyOS and launched SiteroAI, combining its Mentor eClinical suite with studyOS's Ash clinical trial agent. Sitero projects efficiency gains of 20% to 30% across the clinical development lifecycle starting in 2026, with studyOS’s chief executive, Ellis Butterfield, joining Sitero as its chief technology officer.
-
In October 2026, Suvoda made Sofia, an AI assistant embedded in its randomization and trial supply platform, available for all new studies using its RTSM and eCOA systems, where it answers questions across more than 40 topics and can execute approved system actions under existing user permissions. The launch builds on a 2025 patient-facing app that combines electronic clinical outcome assessments, patient payments, visit scheduling and reminders in a single interface, and follows Everest Group naming Suvoda a Leader in its RTSM assessment, citing the platform’s expanding breadth.
Investigator Payment Management Solutions Market Key Players
-
IQVIA
-
Suvoda (Greenphire)
-
Veeva Systems
-
Medidata Solutions (Dassault Systèmes)
-
Sitero
-
Ledger Run
-
WCG Clinical
Investigator Payment Management Solutions Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 350.67 Million |
| Market Size by 2035 | USD 1.16 Billion |
| CAGR | CAGR of 12.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software, Services) • By Deployment Mode (Cloud-based, On-premise) • By Functionality (Investigator Budget Management, Payment Calculation and Automation, Milestone-Based Payment Tracking, Multi-Currency and Cross-Border Payment Management, Tax and Regulatory Compliance Management, Contract and Grant Management, Payment Reconciliation and Audit Trail, Financial Reporting and Analytics) • By End Use (Pharmaceutical Companies, Biotechnology Companies, Contract Research Organizations, Academic and Research Institutes, Government and Non-Profit Research Organizations) • By Payment Type (Investigator Fees, Site Payments, Patient Stipend Disbursements, Grant Payments, Performance and Milestone-Based Payments) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | IQVIA, Suvoda (Greenphire), Veeva Systems, Medidata Solutions (Dassault Systèmes), Sitero, Ledger Run, WCG Clinical |

Frequently Asked Questions
The market includes IQVIA, Suvoda (Greenphire), Veeva Systems, Medidata Solutions, Sitero, Ledger Run, and WCG Clinical. These providers compete on payment automation capability, multi-currency support, platform integration and site network reach.
The main opportunities lie in artificial intelligence for invoice and budget automation, expansion into Asia Pacific, Latin America and the Middle East, and partnerships between global payment platforms and regional contract research organizations.
The key growth factor is rising clinical trial complexity across more countries and currencies, which increases the administrative burden of investigator, site and grant payments and pushes sponsors toward dedicated software over manual processes.
By component, the Software segment dominated the market with approximately 66.27% share in 2025, supported by its role as the system of record for payment calculation. The Cloud-based deployment mode and the Site Payments category led their respective axes.
North America dominated the market with approximately 46.00% share in 2025, supported by the largest concentration of payment-technology vendors and sponsors. Asia Pacific is the fastest-growing region with a projected CAGR of approximately 15.10% from 2026 to 2035.
