
Isoparaffin Solvents Market Report Scope & Overview:
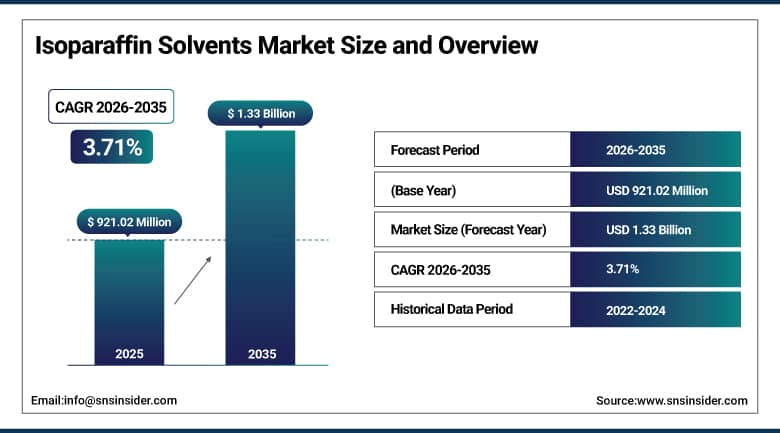
The Isoparaffin Solvents Market was valued at USD 921.02 Million in 2025 and is expected to reach USD 1.33 Billion by 2035, growing at a CAGR of 3.71% from 2026-2035.
The Isoparaffin Solvents Market is witnessing steady growth as formulators look to replace aromatic solvents and mineral spirits with odorless and low toxic solvents. Fluids such as coatings, metal working fluids, agrochemical carriers, and personal care products can benefit from these fluids. Stricter VOC regulations favor substitution. Ultra-pure grades of fluids for use in pharmaceuticals and electronics are now being demanded by buyers. The Asia Pacific region is driving demand through increased production of chips and cosmetics. Refiners are investing in hydrogenation technology and Gas-to-Liquid processes in order to improve purity. There is also entry of renewable feedstock based fluids into portfolio as customers require low carbon footprint.
⮞In February 2026, the Semiconductor Industry Association reported that global semiconductor sales reached USD 791.70 Billion in 2025. Rising chip output lifts demand for ultra-pure solvents used in wafer cleaning and packaging.
To Get More Information On Isoparaffin Solvents Market - Request Free Sample Report
Isoparaffin Solvents Market Trends:
-
Low-VOC rules are speeding the substitution of aromatic solvents and white spirit in coatings, inks and cleaners.
-
Hydrogenation and gas-to-liquids routes are delivering aromatic-free grades with consistent boiling ranges.
-
Renewable and bio-based isoparaffin variants are entering portfolios as buyers target lower carbon footprints.
-
High-purity grades for pharmaceutical, cosmetic and electronics uses are lifting average selling prices.
-
Portfolio reviews among large refiners and chemical groups are reshaping regional supply and ownership.
U.S. Isoparaffin Solvents Market Outlook:
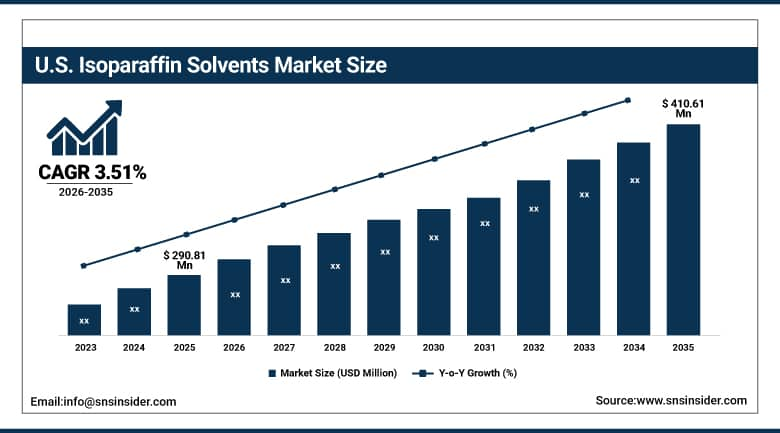
The U.S. Isoparaffin Solvents Market was valued at USD 290.81 Million in 2025 and is expected to reach USD 410.61 Million by 2035, growing at a CAGR of 3.51% from 2026-2035.
The U.S. Isoparaffin Solvents Market holds 89.70% of North American revenue and serves a mature, specification-driven buyer base. Coatings producers favor low-odor fluids that meet state limits on volatile organic compounds. Metalworking plants and aerosol fillers specify steady boiling ranges. Crop protection formulators use the fluids as carriers in concentrates. Pharmaceutical and cosmetic customers pay premiums for ultra-pure grades. Integrated Gulf Coast refining secures feedstock access for producers. Steady building activity and vehicle production sustain base volumes. Regulatory pressure on aromatic solvents keeps reformulation projects active across the country, and buyers increasingly request documented purity from every supplier. Distributors serve mid-sized blenders from regional terminals.
⮞In February 2026, the U.S. Census Bureau reported that construction spending reached USD 2,164.40 Billion during 2025. This activity sustains orders for low-odor paints, sealants and adhesives built on isoparaffin carriers.
Isoparaffin Solvents Market Segment Analysis:
-
By Application, the Paints and Coatings segment dominated the Isoparaffin Solvents Market with approximately 37.36% share in 2025, while the Personal Care segment is the fastest growing with a CAGR of approximately 5.21%.
-
By Grade, the Commercial Grade segment dominated the Isoparaffin Solvents Market in 2025, while the High Purity Grade segment is the fastest growing with a CAGR of approximately 4.91%.
-
By End Use, the Automotive segment dominated the Isoparaffin Solvents Market in 2025, while the Aerospace segment is the fastest growing with a CAGR of approximately 5.11%.
-
By Distribution Channel, the Offline segment dominated the Isoparaffin Solvents Market in 2025, while the Online segment is the fastest growing with a CAGR of approximately 5.31%.
By Application, Paints and Coatings Dominate Isoparaffin Solvents Market; Personal Care to Register Fastest Growth.
Paints and coatings absorb the largest volumes because isoparaffins combine low odor, low viscosity and low surface tension with fast, even drying. They are exempt from volatile organic compound classification in several jurisdictions, which makes them easier to use than mineral spirits and aromatics. Residential construction and renovation sustain architectural demand, while industrial maintenance and wood finishing add recurring orders. Interior paint makers value the balanced solvency and evaporation rate because occupants notice smell immediately after each application
Personal care is advancing fastest as brands formulate lightweight, non-greasy emollients and volatile carriers for skin, hair and body products. Low odor and low toxicity suit leave-on formulations, and ultra-pure grades command premium prices from global cosmetic makers. Rising disposable income and growing beauty awareness widen the consumer base, particularly in Asia Pacific. Launches in sunscreens, anti-aging serums, conditioners and hair care pull more refined volume per formulation than coatings do, and premium brand positioning supports steady reordering.
⮞The American Coatings Association reported in April 2026 that U.S. paint exports reached about USD 2.80 Billion in 2025. Such trade flows keep coatings plants running at scale and support steady solvent offtake.
By Grade, Commercial Grade Dominates Isoparaffin Solvents Market; High Purity Grade to Register Fastest Growth.
Commercial grade fluids lead because they are versatile and cost-effective and they meet the purity levels that most industrial users require. Coatings makers, metalworking shops, cleaner blenders and agrochemical formulators buy large drum and bulk volumes and see little return in paying for purity beyond their specification. Refinery-integrated producers supply these grades widely, which keeps lead times short and delivered quality consistent and contract pricing competitive for high-volume buyers across all regions, while small price gaps rarely justify specification changes.
High purity grades are growing fastest because pharmaceutical and electronics users work under strict quality compliance. Aromatic content in the low parts per million, benzene-free certification and tight distillation cuts support active ingredient synthesis, semiconductor cleaning and cosmetic formulation. Hydrogenation and gas-to-liquids routes make such quality repeatable and verifiable, and customers accept price premiums in exchange for batch consistency, traceability and complete regulatory documentation that auditors can verify at each shipment. Qualification takes months, which discourages switching afterwards.
⮞The U.S. Food and Drug Administration reported that its drug evaluation center approved 46 novel drugs in 2025. Each new therapy widens the pool of synthesis and formulation work that depends on pharmaceutical-grade solvents.
By End Use, Automotive Dominates Isoparaffin Solvents Market; Aerospace to Register Fastest Growth.
Vehicle manufacturing consumes isoparaffins across paint shops, adhesives, sealants and metalworking fluids. Assembly plants and tier-one suppliers rely on low-odor coating systems and clean degreasing steps before painting and bonding. Machining of engine, transmission and brake parts uses cutting fluids built on refined hydrocarbon bases. Large production volumes and frequent refinishing of repaired vehicles give automotive buyers the broadest and steadiest purchasing pattern among end users, which anchors baseline demand for large producers and supports long contract cycles.
Aerospace is growing fastest because aircraft makers and maintenance providers need residue-free cleaning, degreasing and surface preparation ahead of coating and bonding. Strict qualification processes favor tightly specified fluids that evaporate cleanly from composites and alloys. Rising aircraft build rates and a long order backlog raise demand for both new production and scheduled maintenance checks, and each is a recurring buyer of specialty solvents with documented purity and traceable batches. Cleanliness failures are costly, so buyers rarely compromise.
⮞In April 2026, the International Organization of Motor Vehicle Manufacturers (OICA) reported global vehicle production of 96.40 Million units for 2025. Output at that scale underpins constant demand for paint shop and degreasing fluids.
By Distribution Channel, Offline Dominates Isoparaffin Solvents Market; Online to Register Fastest Growth.
Direct contracts and distributor networks carry most volumes because isoparaffins are flammable products that need regulated storage, safety documentation and specialized transport. Buyers want tank truck, ISO tank and drum deliveries on dependable schedules, along with technical advice on grade selection. Long-standing supply agreements give large coatings, metalworking and agrochemical customers the continuity, traceability and credit terms they require, and local depots shorten emergency replenishment. Safety rules for flammable liquids also favor suppliers with certified terminals and trained drivers.
Online channels are expanding fastest as small buyers turn to digital platforms for quick quotations and compact packs. Laboratories, cosmetic start-ups and small formulators value price transparency, wider grade catalogs and doorstep delivery without large minimum orders. Distributors are adding e-commerce portals with downloadable safety data sheets and certificates, which makes digital purchasing of regulated fluids more practical for new customers who previously relied on phone orders and local agents. Small quantities and flexible reordering also suit seasonal buyers.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
89.70 |
|
Asia Pacific |
China |
70.40 |
|
Europe |
Germany |
28.90 |
|
Latin America |
Brazil |
57.60 |
|
Middle East & Africa |
Saudi Arabia |
36.30 |
North America Isoparaffin Solvents Market Insights
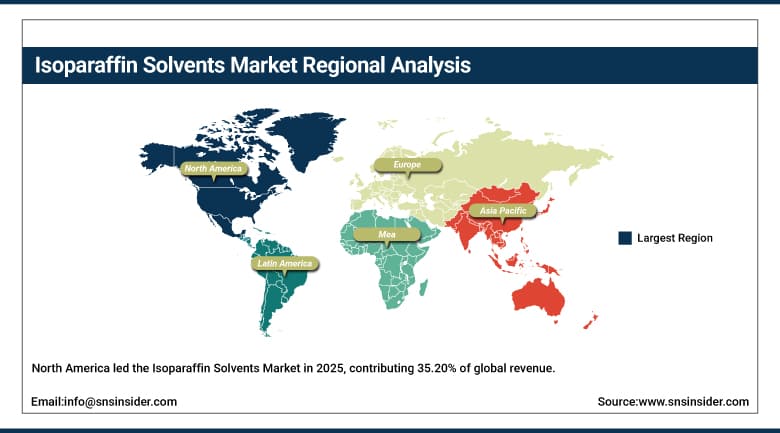
North America led the Isoparaffin Solvents Market in 2025, contributing 35.20% of global revenue. The United States anchors regional consumption through coatings, metalworking and pharmaceutical users, while Canada adds steady demand from energy services, construction and agriculture. Established refining and petrochemical infrastructure supplies feedstock and finished fluids close to customers. Major producers maintain technical service teams across the region, which helps formulators qualify new grades quickly and keeps long-term supply agreements in place. Cross-border trade with Canada keeps inventories balanced. Distributors with regional terminals shorten lead times for mid-sized blenders and support just-in-time purchasing.
Regulation shapes purchasing patterns throughout the region. State and federal limits on volatile organic compounds push formulators of paints, cleaners and aerosols away from aromatic solvents. Polyolefin producers use isoparaffinic diluents in process steps, and agricultural chemical blenders draw on the fluids as carriers for active ingredients. Premium grades for drug manufacturing and electronics continue to gain share of regional sales, and buyers increasingly request certificates covering aromatic and benzene content. Contract manufacturers in electronics and medical devices add further precision cleaning volumes. Environmental permitting for new plants is demanding, so incumbents benefit from existing licensed capacity.
⮞The American Chemistry Council reported in March 2026 that U.S. resin production totaled 136.10 Billion pounds in 2025. Polyolefin synthesis is a recognized outlet for isoparaffin process diluents.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Isoparaffin Solvents Market Insights
Asia Pacific held a 34.60% share in 2025 and is set to post the quickest regional expansion, advancing at a CAGR of 4.81% across 2026-2035. China is the largest national buyer by value, supported by coatings output, electronics assembly and agrochemical formulation. India, Japan and South Korea add demand from automotive plants, cosmetics makers and precision manufacturing, and the breadth of end users reduces dependence on any single cycle. Rapid urbanization and large construction pipelines keep paint plants running at high utilization across several economies, and the concentration of electronics assembly in the region reinforces the pull on high-purity fluids.
Industrialization and the growth of an urban middle class lift consumption of paints, personal care items and processed goods. Local joint ventures are bringing refined hydrocarbon capacity closer to regional customers and shortening delivery times. Electronics clusters in East Asia require high-purity cleaning fluids for wafers and displays. Cosmetics exporters in the region also specify low-odor emollient bases, which supports premium grade uptake and gradually raises the average value of each shipment. Pharmaceutical contract manufacturing in India and China adds further demand. Trade agreements within the region also ease the movement of finished fluids between producing and consuming economies.
⮞In January 2026, South Korea's Ministry of Food and Drug Safety reported that cosmetics exports reached USD 11.43 Billion in 2025. Expanding beauty exports raise demand for odorless, skin-friendly carrier fluids.
Europe Isoparaffin Solvents Market Insights
Europe represented 25.40% of the market in 2025, with Germany, the United Kingdom, France and Italy forming the main demand centers. Strict chemical registration and emissions rules favor low-aromatic fluids. Paint and coatings makers, machine tool builders and automotive suppliers form a dense industrial customer base. Regional producers have invested in hydrogenation capacity to deliver ultra-pure grades, and several operate dedicated lines for pharmaceutical and cosmetic customers. Strong aerospace and rail manufacturing adds precision cleaning demand. Germany contributes the largest national value through chemicals, machinery and automotive production.
Sustainability goals are shaping product choices. Biosourced isoparaffin variants and lower-carbon production routes are gaining attention among large formulators with emissions targets. Pharmaceutical and cosmetics hubs in Germany, Switzerland and France buy tightly specified grades and audit suppliers closely. Asset reviews at large chemical groups may redraw the supply map over the coming years, and buyers are diversifying sources to protect continuity. Machine tool exports from Germany and Italy sustain metalworking fluid demand. Circular economy initiatives are also encouraging solvent recovery and reuse programs in industrial plants. Distributors with multilingual safety documentation hold an advantage in cross-border sales. Compliance support is a selling point.
⮞Airbus reported in January 2026 that it delivered 793 commercial aircraft in 2025. Production at that pace sustains regional demand for precision cleaning and surface preparation fluids.
Latin America & MEA Isoparaffin Solvents Market Insights
Latin America accounted for 2.90% of the market in 2025, with Brazil, Mexico and Argentina leading consumption. Brazil dominates the regional mix through large paint, agrochemical and cosmetics industries. Mexico supplies automotive and manufacturing demand linked to cross-border production. Imports from North America and Asia cover most regional needs, so currency swings and freight costs influence pricing. Local blenders are expanding storage to hold safety stock and to serve smaller customers faster. Agricultural expansion in the Southern Cone also lifts demand for crop protection carriers. Growing middle-class populations are lifting consumption of paints and household products.
⮞In August 2026, the Brazilian crop protection association Sindiveg reported that sales in Brazil reached about USD 9.00 Billion in the first half of 2026, an increase of 11.10%. Heavy agrochemical activity keeps regional carrier fluid demand firm.
The Middle East and Africa held 1.80% in 2025, with Saudi Arabia, the United Arab Emirates and South Africa as principal markets. Construction programs, oil and gas services and growing industrial zones support steady volumes. Regional refiners and petrochemical complexes are exploring downstream specialty fluids, which could reduce reliance on imports over time. Distributors in the Gulf also serve African customers, and that re-export trade widens the reach of imported grades. Infrastructure investment is also supporting coatings demand in the Gulf and East Africa. Local content policies may encourage in-region blending of imported base fluids.
⮞Kamco Invest reported in January 2026 that contract awards across the Gulf Cooperation Council totaled USD 213.40 Billion in 2025. Such project activity feeds regional demand for coatings and construction chemicals.
Market Dynamics:
Growth Drivers: Tighter VOC rules and expanding coatings and personal care output are raising demand for isoparaffin solvents
Environmental regulation is the strongest force behind adoption. Limits on volatile organic compounds and workplace exposure are pushing formulators away from aromatic solvents and mineral spirits. Isoparaffins offer low odor, low toxicity and strong solvency, so paint, cleaner and ink makers can reformulate without losing performance. Construction and vehicle production keep coatings volumes high, and reformulation work extends the use of these fluids into adhesives, sealants and aerosols across both mature and emerging economies. Brand owners now include solvent choice in sustainability reporting. Producers that document compliance early gain preference in tenders from multinational brand owners.
Growth is provided by downstream sectors through several channels. The cosmetics industry prefers odorless emollients; the metalworking industry relies on clean fluids for cutting and degreasing, while crop protection firms look for stable carriers. Isoparaffinic diluents are used by polyolefin manufacturers during production. There is an additional premium demand from pharmaceutical and electronics firms for ultra-pure grades, which provides higher average pricing for manufacturers who can deliver high-specification products. These grades have been qualified for long-term contract work. Increased income in emerging economies expands the market for premium household and personal care products.
⮞In August 2025, the Brazilian Paint Manufacturers Association (Abrafati) reported that paint sales in Brazil reached 670 Million liters in the first half of 2025. Volumes of this size show how construction and renovation sustain solvent consumption.
Restraints: Volatile petroleum feedstock costs and cheaper substitutes are limiting pricing power for isoparaffin solvents
Feedstock linked to crude oil exposes producers to swings in input costs. Refining and hydrogenation steps are capital intensive, and the resulting price premium over mineral spirits and standard paraffins discourages price-sensitive buyers. Contract pricing must absorb these movements, and smaller producers lack the integration needed to cushion them. Emission controls and flammability handling add further expense to production, storage and transport. Buyers frequently run dual-sourcing programs to manage this exposure. Hedging is usually limited because solvent contracts often run quarterly.
Competition from substitutes provides additional pressure. Glycol ethers, mineral spirits, and biobased solvents provide competition to glycol ethers in coating, cleaning, and agricultural applications especially when the specifications required are not very high. Chemicals registration costs create a problem for small manufacturers while import duties on equipment and intermediates increase costs. Hence, purchasers balance their decision on performance improvement and cost, thus making the uptake slower in cost-sensitive areas. Supply chain disruptions from a single plant cause disruption among buyers that use the specific cut products. Differences in solvent types allowed in each region create problems in developing product lines for multinational buyers. Import duties may affect price comparisons between local and imported products.
⮞The U.S. Energy Information Administration reported in January 2026 that Brent crude averaged USD 69.04 per barrel in 2025 and forecast USD 55.87 for 2026. Movements of that size complicate contract pricing for refined solvents.
Opportunities: Ultra-pure grades, renewable feedstocks and agrochemical formulation are opening new revenue pools for isoparaffin solvents
Ultra-pure grades for pharmaceutical, cosmetic and semiconductor uses carry premium pricing and steadier margins than bulk fluids. Producers with hydrogenation or gas-to-liquids capacity can qualify products with leading drug makers and chip fabricators. Precision cleaning in electronics manufacturing is a rising outlet as device complexity grows. Joint ventures in Asia Pacific offer routes to local customers and shorter supply chains, and they allow technology owners to share capital risk. Regulatory approval of new grades in drug manufacturing can lock in suppliers for many years. Qualification cycles are long but the resulting contracts tend to be sticky.
Renewable feedstocks offer a second path. Bio-based and hybrid isoparaffin blends let brand owners cut the carbon footprint of finished products, and early suppliers can secure long-term agreements. Agricultural formulation also remains a large outlet, since crop protection concentrates depend on low-odor carriers. Infrastructure programs in developing economies further widen the base for paints and coatings, and they create openings for regional blenders to build recurring accounts. Digital ordering tools also help suppliers reach smaller buyers at lower cost. Recycling and solvent recovery services may add recurring service revenue. Partnerships with cosmetic and agrochemical brands can speed market entry.
⮞The Food and Agriculture Organization reported in July 2025 that global pesticide use reached 3.73 Million tonnes of active ingredients in 2023. This large formulation base continues to rely on low-aromatic carrier fluids.
Recent Developments:
-
November 2025, Haltermann Carless extended its license for Neste NEXSAT hydrogenation technology at the Speyer plant to cover the entire naphtha boiling range. The unit, commissioned in 2022, removes aromatics and olefins to make high-purity solvents for active pharmaceutical ingredient synthesis, adhesives and process uses.
-
March 2025, Shell confirmed that it is considering a sale of chemical assets in the United States and Europe. The review covers strategic options in the United States and a high-grading of European holdings.
-
August 2026, Calumet reported second quarter results that cited a global shortage of specialty products in its Specialty Products and Solutions segment. The comment points to tight availability of specialty fluids, a group that includes solvent lines.
-
May 2026, Chevron Phillips Chemical said its Golden Triangle Polymers complex is entering commissioning and startup. The venture with QatarEnergy includes an ethane cracker of 2,080 kilotons per year and two high-density polyethylene units of 1,000 kilotons each, with full operation projected for 2027.
Isoparaffin Solvents Market Key Players:
-
ExxonMobil
-
TotalEnergies
-
Chevron Phillips Chemical
-
Idemitsu Kosan
-
Shell
-
Haltermann Carless
-
Calumet
-
Mehta Petro Refineries
Isoparaffin Solvents Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 921.02 Million |
| Market Size by 2035 | USD 1.33 Billion |
| CAGR | CAGR of 3.71% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Application (Paints and Coatings, Metalworking, Agrochemicals, Polymers, Cleaning Agents, Personal Care, Pharmaceuticals, and Others) • By Grade (Commercial Grade and High Purity Grade) • By End Use (Automotive, Aerospace, Construction, Healthcare, and Electronics) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ExxonMobil, TotalEnergies, Chevron Phillips Chemical, Idemitsu Kosan, Shell, Haltermann Carless, Calumet, Mehta Petro Refineries |

Frequently Asked Questions
ExxonMobil, TotalEnergies, Chevron Phillips Chemical, Idemitsu Kosan and Shell are the key players in the Isoparaffin Solvents Market, among others.
Key opportunities include ultra-pure grades for pharmaceutical, cosmetic and semiconductor uses, renewable and bio-based isoparaffin blends, precision cleaning in electronics and agrochemical formulation. Joint ventures in Asia Pacific and infrastructure programs in developing economies also widen the customer base.
The major growth factor is tighter regulation of volatile organic compounds, which is pushing paint, cleaner and ink makers to replace aromatic solvents and mineral spirits with low-odor, low-toxicity isoparaffins.
The Paints and Coatings segment dominated the Isoparaffin Solvents Market in 2025 with a share of 37.36%, supported by low odor, fast drying and favorable treatment under volatile organic compound rules.
North America dominated the Isoparaffin Solvents Market in 2025 with a share of 35.20%, owing to its strong industrial infrastructure, strict solvent regulations and the presence of major producers.
