
Legal Technology Market Report Scope & Overview:
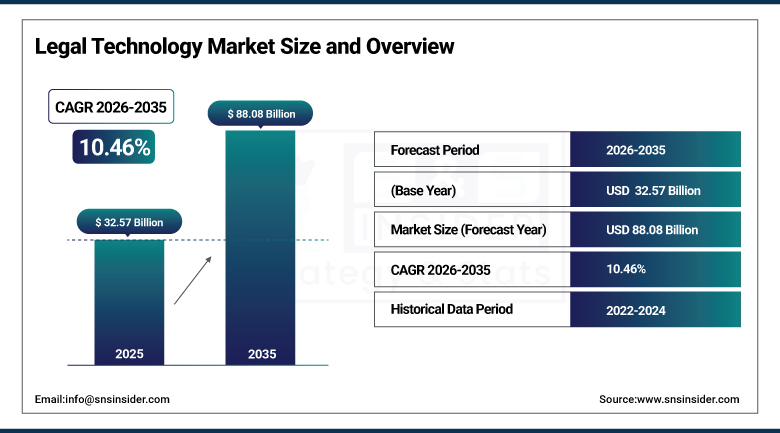
The Legal Technology Market was valued at USD 32.57 Billion in 2025 and is estimated at USD 35.98 Billion in 2026. It is projected to reach USD 88.08 Billion by 2035, registering a compound annual growth rate (CAGR) of 10.46% from 2026 to 2035. Generative artificial intelligence (AI) assistants, growing document volumes, and pressure to lower the cost of legal work are moving the profession from manual processes toward integrated digital platforms.
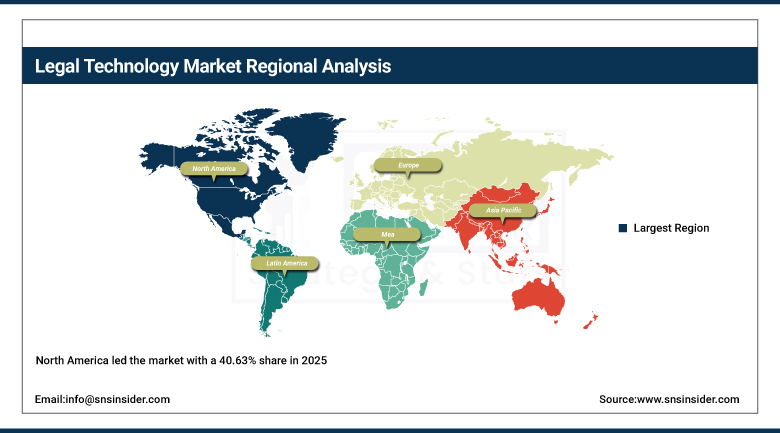
North America held the leading market share with a 40.63% contribution in 2025 owing to having a substantial legal services market, early adaptation to cloud legal practice solutions, and extensive vendor and investor presence. Europe follows North America in terms of market size, as here the legal purchase decisions are regulated by data protection and AI policies. Asia-Pacific region is estimated to have the highest growth rate up to 2035 due to digitalization of the judiciary, law offices, and in-house corporate lawyers in China, India, Japan, and Australia.
To Get more information Legal Technology Market - Request Free Sample Report
Key Report Takeaways
-
By component, software held a 72.94% share in 2025, while services are the fastest growing.
-
By application, e-discovery held a 24.12% share in 2025, while contract lifecycle management is the fastest growing.
-
By end user, law firms held a 54.37% share in 2025, while corporate legal departments are the fastest growing.
-
By deployment, cloud held a 61.58% share in 2025, while hybrid deployment is the fastest growing.
-
By region, North America held a 40.63% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights
-
Generative AI assistants for drafting, research, and contract review are being built into mainstream legal platforms.
-
Vendors are combining research content, practice management, and document systems into single AI workspaces.
-
Corporate legal departments are consolidating contract, matter, and spend tools to control outside counsel costs.
-
Courts and bar bodies are issuing rules on AI-assisted filings, which is creating demand for verification and citation checking tools.
-
Cloud delivery and application programming interfaces are replacing on-premises installations in firms of all sizes.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Adoption of generative AI by lawyers and legal teams |
+4.02% |
North America, Europe |
Short term (2 years or less) |
|
Growth in document volumes and compliance workload |
+3.14% |
Global |
Medium term (2 to 4 years) |
|
Cost pressure on corporate legal departments |
+2.58% |
North America, Europe |
Medium term (2 to 4 years) |
|
Migration to cloud-based practice platforms |
+2.21% |
Global |
Medium term (2 to 4 years) |
|
Digitization of courts and filing systems |
+1.74% |
Asia Pacific, Europe |
Long term (4 years or more) |
Adoption of Generative AI by Lawyers and Legal Teams Expands Software Spending
Generative AI tools now draft documents, summarize case files, search precedent, and answer questions over firm knowledge, and lawyers are moving from experiments to daily use. In March 2025, the American Bar Association reported in its Legal Technology Survey Report that 30.00% of responding lawyers used AI tools, up from 11.00% a year earlier. Vendors respond with assistants built into research, drafting, and document platforms, and buyers expand licenses as results become visible in time savings and faster turnaround. Adoption continues to spread.
Growth in Document Volumes and Compliance Workload Raises Demand for Automation
Litigation and investigations involve ever larger sets of email, chat messages, and cloud files, and regulatory requirements add review work for corporate legal teams. Technology that culls, tags, and summarizes documents lowers the cost of each matter and shortens deadlines. Compliance monitoring, privacy requests, and contract obligations also generate steady workloads that software can structure. These pressures make e-discovery and compliance tools a standing budget item. Data analytics also helps legal operations teams forecast review costs and allocate resources across matters.
Cost Pressure on Corporate Legal Departments Encourages Outsourcing to Technology
Due to budget constraints, along with the rising needs of business units, the GCs will be interested in finding out how they can manage their operations internally and cut costs in external counsel. The use of contract management, matter management, and spend analytics tools helps in getting visibility about cost management within the departments. With self-service and approvals, the business units can negotiate without the involvement of legal. Dashboards show delayed agreements, risky clauses, and the workload each business unit sends to the legal team, which supports resourcing decisions.
Migration to Cloud-Based Practice Platforms Lowers Barriers for Smaller Firms
The use of subscription software lowers the initial investment required for practice management, billing and document management software, and smaller firms now have access to software that was previously accessible only to larger firms. The use of cloud computing technology enables remote working capabilities, mobility of software products, and regular updates to products. Vendors bundle research, electronic signature and payments in one account, and this helps to make purchases easier for buyers. The adoption of cloud computing widens the pool of buyers and recurring revenue sources for vendors.
Digitization of Courts and Filing Systems Builds a Base for Legal Software
Courts and government agencies in many countries are moving to electronic filing, remote hearings, and digital case records. Law firms and legal departments must then adapt their workflows, document formats, and calendars to these systems. Public sector investment in case management and online dispute resolution also creates demand for specialized software. As digital court records become standard, analytics and research tools gain richer data to work with. Online dispute resolution platforms and virtual hearings also bring new categories of users into digital legal services.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Confidentiality, privilege, and data security concerns |
-1.12% |
Global |
Short term (2 years or less) |
|
AI accuracy risk and sanctions for unverified citations |
-0.94% |
North America, Europe |
Short term (2 years or less) |
|
Billable-hour pricing that rewards time spent |
-0.71% |
North America, Europe |
Long term (4 years or more) |
|
Integration cost and change management for smaller firms |
-0.46% |
Global |
Medium term (2 to 4 years) |
Confidentiality, Privilege, and Data Security Concerns Slow Adoption
Lawyers owe duties of confidentiality, and clients increasingly review how firms handle their data. Concerns about sending sensitive documents to cloud services or to AI models, and about possible loss of privilege, make some firms cautious. Corporate clients add security questionnaires and audit rights to outside counsel guidelines, and vendors must provide encryption, tenant isolation, and clear data retention terms. Procurement reviews can take months, which delays rollouts. Vendors respond with certifications, private model options, and zero-retention terms to ease concerns.
AI Accuracy Risk and Sanctions for Unverified Citations Create Caution
Plausible but inaccurate citations may be generated through generative models, and there have been sanctions against lawyers who submitted their documents without verifying them. In March 2026, the New York Unified Court System introduced Part 161, which took effect on 1 June 2026, mandating that all persons using AI in the submission of any document in court must verify the absence of fictitious cases and statutes. Law firms adjust by introducing a verification process as well as citation checking mechanisms. The supervision needs slow down the adoption pace.
Billable-Hour Pricing Reduces Incentives to Adopt Efficiency Tools
Many companies continue making money based on time spent, and technologies that save time seem to have the potential to reduce revenue. Partners tend to be more willing to implement technology in order to benefit clients rather than their company’s internal processes. Alternative fee arrangements become increasingly popular, but this transition process is slow and patchy. Fixed-fee and subscription models reward efficiency, and corporate clients are pressing outside counsel to adopt them, which gradually changes incentives. Change is steady.
Integration Cost and Change Management Burden Smaller Firms
Connecting new tools to existing document systems, billing software, and email requires technical support that small firms rarely have. Training lawyers and staff to change habits takes time, and poor adoption reduces the return on licenses. Vendors offer onboarding and templates, but many small practices stay with familiar spreadsheets and manual processes until a client or court requirement forces change. Resellers and bar associations offer discounted bundles and training programs, which help, but support gaps remain for very small practices with limited technical expertise.
Legal Technology Market Segment Analysis
By Component, Software Dominates Legal Technology Market; Services to Register Fastest Growth.
Software accounted for a 72.94% share in 2025 because law firms and legal departments license platforms for practice management, document handling, research, e-discovery, and contract workflows on recurring subscriptions. AI assistants are packaged as add-ons or embedded modules, which raises revenue per user. Large vendors keep customers through integrated suites and content libraries that are costly to replace. Contract values grow as firms add research, drafting, and analytics modules to existing accounts through tiered packages each year. Renewals are strong.
Services are expected to witness a growth rate of 11.43% CAGR from 2026 to 2035 due to buyer need for assistance with implementation, data migration, managed e-discovery review, and AI governance. Alternative legal service providers and consultants manage the technology-enabled review and contract operations for their corporate buyers. The training and change management services segment also expands due to the complexity of tools used. Legal services organizations also employ outsourcing firms for reviewing and transcribing documents. Demand is broad.
By Application, E-Discovery Dominates Legal Technology Market; Contract Lifecycle Management to Register Fastest Growth.
The e-discovery segment had a market share of 24.12% in 2025, as there is enormous generation of data during legal proceedings like litigations, investigations, and inquiries, which needs to be collected and analyzed. In-house counsels and external law firms require systems which can do analysis and document sorting, and review services use such systems. Cost-per-matter and tight timelines guarantee spending of money all the time. Early case assessment, TAR, and generative summaries reduce the volume of documents that the lawyers have to manually analyze.
Contract Lifecycle Management (CLM) will have a CAGR of 15.76% from 2026-2035 as firms look for quicker contract drafting, signing, and renewal monitoring. AI identifies the clauses and warns about risks within huge portfolios of contracts, providing distinct value to lawyers and financial professionals. The integration with electronic signature, CRM, and purchasing systems helps widen its use. It is also preferred by buyers as it identifies bottlenecks in negotiations, and the cloud-based repository can search signed agreements for their renewals and unique clauses. Finance teams benefit too.
By End User, Law Firms Dominate Legal Technology Market; Corporate Legal Departments to Register Fastest Growth.
Law firm’s share in 2025 was 54.37% due to the volume of work, paperwork, and billing involved in their operations and their competition based on speed and expertise. Larger firms spend in research, writing, and knowledge management, while mid-sized and smaller firms use cloud-based practice management. The efficiency and security of clients also compel them to go for modernization. Law firms spend in time capture, billing, and knowledge management systems that help partners in decision making and minimize write-offs on each case.
Corporate legal departments are projected to register a CAGR of 11.81% from 2026 to 2035 as general counsel digitize contract, matter, and compliance work and build in-house capacity. Growth in regulation, privacy duties, and litigation risk adds responsibilities. Departments favor platforms that give business users self-service tools while keeping oversight. Departments also build legal operations teams that select tools, track spending, and report results to chief financial officers and boards each quarter. Reporting lines increasingly reach finance leaders.
By Deployment, Cloud Dominates Legal Technology Market; Hybrid to Register Fastest Growth.
In 2025, Cloud occupied a share of 61.58%, which is owing to the fact that it has rapid deployment, offers remote working capabilities, and receives continuous updates, including AI-related functionalities. Small and medium enterprises find them useful owing to their low initial costs; while big enterprises are increasingly moving over to them owing to document and matter management being certified by the vendor. These applications integrate through API and offer disaster recovery and uptime guarantees to businesses that used to keep servers in-house.
The hybrid approach is anticipated to see a CAGR of 11.76% in the period between 2026 and 2035, since organizations and governments will ensure that confidential data centers remain on-premises while the rest is used in cloud infrastructure for AI applications and collaborations. The requirement of the data residency laws and client requests also backs up the hybrid approach. The vendors offer connection services and private tenant facilities for the two different infrastructures. Pilots are often limited to one practice group.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.41% |
|
Europe |
United Kingdom |
29.36% |
|
Asia Pacific |
China |
28.53% |
|
Middle East & Africa |
United Arab Emirates |
31.07% |
|
Latin America |
Brazil |
48.15% |
North America Legal Technology Market
North America led the market with a 40.63% share in 2025, supported by a large legal services sector, early adoption of cloud practice tools, and a deep base of vendors and investors. USD 11.57 Billion revenue was made by the US in 2025 and is expected to rise at a CAGR of 9.57% between 2026 and 2035. Big law firms, corporate law departments, as well as federal and state courts, spend on e-discovery, research, and contract management solutions, while Canada contributes demand from their respective legal markets.
In May 2026, the Florida Supreme Court revised its rule on signatures to note that signing a document is an acknowledgment that any legal sources referred to within the document do exist and were properly cited, thus giving yet another reason why citation checking services are important. Legal AI start-ups keep raising venture capital and being acquired, while bar associations keep issuing guidelines on technological competency. In New York City, Chicago, and Los Angeles, law firms are the first users of artificial intelligence tools for drafting documents.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Legal Technology Market
The Europe region is ranked second among regional markets with a 25.94% share in 2025. In the region, the UK ranks first followed by Germany, France, the Netherlands, and Spain. Legal firms in London as well as other business centers on the continent embrace AI research and writing tools. Corporate legal teams in finance, pharmaceuticals, and manufacturing industries modernize their contracting and compliance procedures. Other countries in the region like Switzerland, Ireland, and the Nordic nations create demand for AI from their arbitration, finance, and technology sectors.
In May 2026, the EU Institutions made a political deal regarding the AI Act omnibus bill that pushes back the deadline for obligations concerning stand-alone high-risk systems until December 2027, giving vendors more time to prepare documentation. Data protection legislation, multilingual information, and national judicial systems are in favor of vendors with local hosting and regional content. Brussels and Luxembourg institutions also drive demand for multilingual research and translation tools, and national bar bodies publish guidance that firms use when choosing vendors. Local rules still matter greatly.
Asia Pacific Legal Technology Market
Asia Pacific is expected to record the fastest growth, at a CAGR of 12.19% from 2026 to 2035, as courts, law firms, and corporate legal teams digitize in China, India, Japan, and Australia. China dominates the market share in the region, backed up by their online court system and the use of technological tools in judiciary, financed by the government. Japan, South Korea, and Singapore have adopted contract and compliance software. Hong Kong and Singapore act as arbitration and finance centers, investing heavily in e-discovery and contract analytics.
India has a large and growing legal industry and has been increasing the use of electronic filing and management of cases, thus requiring research and workflow management tools. Australia already has a matured market with adoption of cloud practice systems. Global companies work with local resellers in these regions and even develop regional language models. Courts across the region are testing AI assistants for case summaries and scheduling, and local start-ups build language-specific models for Chinese, Japanese, and Hindi legal text. Taiwan also contributes.
Latin America Legal Technology Market
Latin America accounted for 5.46% of the market in 2025, led by Brazil, followed by Mexico, Argentina, Chile, and Colombia. Brazil is known to be one of the countries with the highest number of cases filed and therefore its electronic courts require solutions such as case management, case analytics, and document automation. Legal departments in the banking and retail industry utilize contract and compliance solutions. Development in the fintech and e-commerce industry contributes towards increasing workload on compliance and contracts in regional corporate legal departments.
Local legal technology start-ups focus on process automation and litigation analytics, and international vendors enter through partnerships with regional firms. Mexico is expanding digital contracting and compliance services linked to trade with North America. Currency volatility and uneven internet infrastructure moderate adoption. Regional bar associations are promoting digital skills and several large firms are piloting AI research tools, which should widen adoption among mid-sized practices over the forecast period. Brazil also hosts active legal tech associations and incubators that connect start-ups with large law firms.
Middle East & Africa Legal Technology Market
The Middle East and Africa held a 5.66% share of the market in 2025. The Gulf region leads in terms of demand, where UAE has the highest share in terms of country, followed by Saudi Arabia and Qatar. Investments in such tools will be driven by the need for case management, contracts, and research. This is evidenced by the creation of commercial courts and arbitration centers in Saudi Arabia through national economic programs, thereby making investment in such tools possible.
Africa's most developed market is that of South Africa, where cloud practice management is being used by established businesses. Growing interest in cloud practice management can be seen in Nigeria, Kenya, and Egypt as their courts embrace technology and there is an increase in corporate legal teams. The importance of partnering with local providers due to the presence of Arabic language content and local regulations cannot be ignored for foreign vendors. Nigeria also hosts several legal technology incubators that train developers.
Competitive Landscape
The Legal Technology Market is fragmented. Global information providers, document and workflow software companies, e-discovery specialists, and fast-growing AI start-ups all serve legal buyers, and no single provider holds a large share of total spending. Large content owners compete through proprietary data and brand trust, while specialists compete on workflow depth and speed of innovation.
Vendors follow three main strategic lines. First, they embed generative AI assistants into research, drafting, and document platforms. Second, they acquire content, workflow, and data companies to build integrated suites. Third, they form partnerships with contract, e-signature, and enterprise software providers so that legal work connects with the rest of the business.
Legal Technology Market Industry Leaders
1. Thomson Reuters: Offers CoCounsel Legal, Westlaw, and Practical Law for AI-assisted research and drafting.
2. RELX: Provides Lexis+ with Protege through its LexisNexis Legal and Professional business.
3. Wolters Kluwer: Delivers Libra, a legal AI workspace built on trusted content from its legal and regulatory business.
4. Clio: Supplies cloud practice management software and legal research through its vLex acquisition.
5. Relativity: Sells RelativityOne and aiR tools for e-discovery and investigations.
Companies Covered in this Report
-
Thomson Reuters
-
RELX
-
Wolters Kluwer
-
Clio
-
Relativity
-
Harvey
-
Epiq
-
Litera
-
Intapp
-
NetDocuments
-
Everlaw
-
Filevine
-
DISCO
Recent Developments
-
November 2025: Clio completed its acquisition of vLex and announced a USD 500 million Series G funding round, adding a research library covering more than 110 jurisdictions.
-
March 2026: Everlaw expanded its Deep Dive AI product with transcripts and fact management features after rapid adoption on hundreds of cases.
-
July 2026: Litera relaunched as a legal AI platform built around a single agent that connects practice and business of law functions.
-
August 2026: Relativity announced claiR, a conversational AI assistant over RelativityOne matter data, in advanced access with three law firms.
-
August 2026: Thomson Reuters made the next generation of CoCounsel Legal generally available in the United States.
-
August 2026: Wolters Kluwer introduced a new version of its Libra legal AI workspace with a knowledge graph that links laws, rulings, and commentary.
-
September 2026: Harvey raised USD 550 million at a USD 15.5 billion valuation to expand its legal AI platform.
Scope and Research Methodology
The study defines the Legal Technology Market as software and associated services used by law firms, corporate legal departments, courts, and other legal users to manage legal work. Covered offerings include e-discovery platforms, contract lifecycle management, practice and document management, legal research and analytics, compliance and risk tools, and implementation and managed services delivered through cloud, on-premises, and hybrid environments. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. General business software, consumer legal document services, and legal process outsourcing without a technology platform are excluded. Hardware, general office suites, and legal publishing sold only in print are also outside the definition, and services are counted only where they support the deployment of legal software.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations, court and bar association publications, regulatory filings, trade association surveys, and peer-reviewed and industry literature. Primary research consists of structured interviews and surveys with law firm technology heads, general counsel, legal operations leaders, and vendor executives across the value chain. These discussions validate assumptions on adoption, pricing, and license mix. Interview findings are weighted by the relevance and seniority of each respondent, and conflicting inputs are checked against company disclosures and published court and bar association data.
Market engineering follows a bottom-up build from vendor revenue, user counts, and subscription values, cross-checked top-down against legal services spending and corporate legal budgets. Triangulation between the two methods helps reduce discrepancies prior to settling on the values. The forecasts take into account factors like AI adoption, documents, and regulations. The regional values are coordinated in such a way that when added up, their sum will be equal to the total regional value, and each forecast is subject to quality control by an analyst prior to being published. Sensitivity tests the impact of variations in AI adoption, prices, and regulations on each segment.
Legal Technology Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 32.57 Billion |
| Market Size by 2035 | USD 88.08 Billion |
| CAGR | CAGR of 10.46% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Services) • By Application (E-Discovery, Contract Lifecycle Management, Practice and Document Management, Legal Research and Analytics, Compliance and Risk Management, and Others) • By End User (Law Firms, Corporate Legal Departments, Government and Regulatory Bodies, and Others) • By Deployment (Cloud, On-Premises, and Hybrid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | RELX, Wolters Kluwer, Clio, Relativity, Harvey, Epiq, Litera, Intapp, NetDocuments, Everlaw, Filevine, DISCO |

Frequently Asked Questions
The market was valued at USD 32.57 Billion in 2025 and is projected to reach USD 88.08 Billion by 2035 at a CAGR of 10.46%.
North America led the market with a 40.63% share in 2025, supported by a large legal services sector and early adoption of cloud practice tools.
Asia Pacific is expected to grow the fastest, at a CAGR of 12.19% from 2026 to 2035.
Software, e-discovery, law firms, and cloud deployment hold the largest shares in their segments.
Services, contract lifecycle management, corporate legal departments, and hybrid deployment are the fastest growing segments.
Major players include Thomson Reuters, RELX, Wolters Kluwer, Clio, and Relativity.
Confidentiality concerns, AI accuracy risk, billable-hour pricing, and integration cost limit faster growth.
