
Marine Insurance Market Report Scope & Overview:
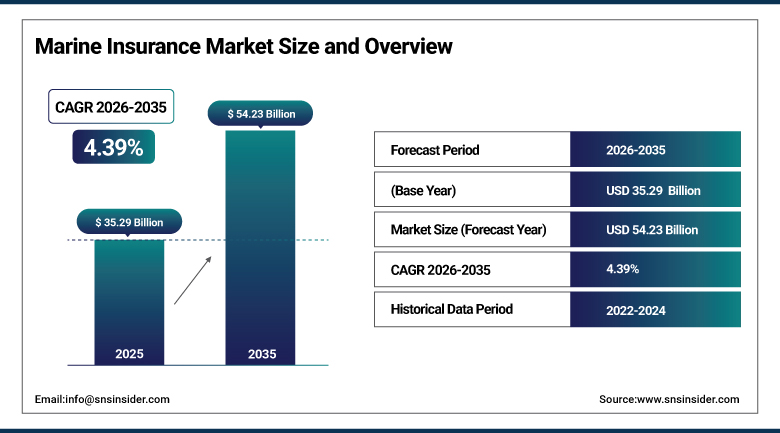
The Marine Insurance Market was valued at USD 35.29 Billion in 2025 and is expected to reach USD 54.23 Billion by 2035, growing at a CAGR of 4.39% from 2026-2035.
The Marine Insurance Market is expanding as seaborne trade, vessel values and geopolitical exposure rise together. Insurers are repricing risk on every major trade lane. War risk cover has moved from an optional add-on to a core underwriting line. Brokers still control most placements while digital platforms gain share in cargo and small-fleet business. Europe anchors global premium through the Lloyd's market and the International Group of P&I Clubs. Asia Pacific is the growth engine as shipowners and traders add capacity. Climate losses, sanctions screening and cyber exposure are reshaping policy wordings. Capacity remains ample but selective. Underwriters reward well-run fleets with stable terms and penalize opaque operators with higher deductibles and tighter limits.
⮞In July 2026, the ICC International Maritime Bureau reported 38 piracy and armed robbery incidents worldwide in the first half of the year. The low count shows that physical attack risk is easing even as political and war risks push pricing higher on specific trade lanes.
To Get more information Marine Insurance Market - Request Free Sample Report
Marine Insurance Market Trends
-
Insurers are building dedicated war risk capacity for Gulf and Black Sea transits.
-
Digital placement platforms are moving cargo and small-fleet cover away from paper broking.
-
P&I clubs are merging to widen capital bases and global servicing reach.
-
Sanctions screening and shadow fleet exposure are reshaping underwriting and policy wordings.
-
Decarbonization rules and alternative-fuel vessels are creating new hull and liability risk models.
U.S. Marine Insurance Market Outlook
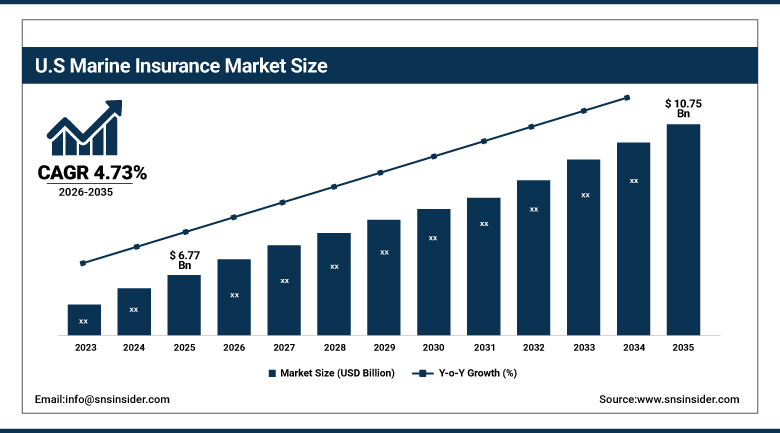
The U.S. Marine Insurance Market was valued at USD 6.77 Billion in 2025 and is expected to reach USD 10.75 Billion by 2035, growing at a CAGR of 4.73% from 2026-2035.
The U.S. Marine Insurance Market benefits from deep import and export volumes through Gulf Coast, East Coast and West Coast gateways. Energy exports and project cargo keep demand for cargo and marine liability cover high. U.S. carriers compete with London and European underwriters on large accounts. Soft pricing in cargo has pushed insurers toward disciplined risk selection. Federal programs now back Gulf shipping through reinsurance support. Port automation and offshore wind construction are widening policy needs. Surplus lines carriers and managing general agents are expanding marine appetite. Brokers dominate placements for large fleets while digital quoting gains ground in smaller cargo accounts. Regulators keep the focus on sanctions compliance and claims transparency.
⮞In September 2026, the International Union of Marine Insurance reported that the U.S. marine cargo loss ratio was about 40% in 2025. The figure points to healthy margins for cargo writers, although the union cautioned that under-reporting may explain part of the improvement.
Marine Insurance Market Segment Analysis
-
By Coverage Type, the Cargo segment dominated the Marine Insurance Market with approximately 50.84% share in 2025, while the War and Political Risks segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Policy Type, the Time Policy segment dominated the Marine Insurance Market with approximately 44.15% share in 2025, while the Floating Policy segment is the fastest growing with a CAGR of approximately 5.22%.
-
By Distribution Channel, the Brokers segment dominated the Marine Insurance Market with approximately 67.17% share in 2025, while the Digital Distribution segment is the fastest growing with a CAGR of approximately 7.36%.
-
By End User, the Shipping Companies segment dominated the Marine Insurance Market with approximately 44.13% share in 2025, while the Freight Forwarders segment is the fastest growing with a CAGR of approximately 5.01%.
By Coverage Type, Cargo Dominates the Marine Insurance Market and War and Political Risks Grows Fastest
Cargo cover anchors the marine insurance book because every container, bulk shipment and project load needs protection from loading to delivery. Exporters, importers and traders buy it to satisfy letters of credit and sales contracts. Volume growth in e-commerce and energy trade keeps insured values climbing. Insurers price cargo on commodity type, packaging, route and carrier quality. Loss ratios have stayed favorable in recent years, which attracted new capacity and encouraged competitive pricing. Claims often arise from fire, container loss, theft and temperature damage, so surveyors and tracking technology play a growing role in underwriting decisions.
War and political risks cover has gained urgency because sanctions, conflict zones and chokepoint disruption now shape routing decisions. Shipowners and charterers buy short-notice war cover when vessels enter listed areas. Premiums are quoted as a percentage of vessel value per transit, so repricing follows any major incident. Lloyd's syndicates, P&I clubs and specialist facilities are launching dedicated capacity for the Gulf and the Black Sea. Blocking and trapping, detention and political violence extensions are being added to many policies. The line is smaller than cargo but is expanding quickly as buyers treat it as a standing budget item.
⮞In March 2026, Gard issued a notice of cancellation of war risk cover under 21 Gard covers for Iran and the wider Gulf region, effective 5 March 2026. The notice shows how quickly insurers withdraw and reprice war cover, which sustains demand for specialist capacity.
By Policy Type, Time Policy Dominates the Marine Insurance Market and Floating Policy Grows Fastest
Time policies remain the default for hull and P&I business because shipowners want continuous annual protection for a vessel or an entire fleet. The structure aligns with the February P&I renewal cycle and with annual hull placements in London and Scandinavia. Underwriters assess fleet age, flag, class record and trading pattern before setting terms. Fixed policy periods simplify budgeting and support financing covenants that require evidence of continuous cover. Renewal talks now center on deductibles, sanctions clauses and war risk exclusions. Large fleets increasingly bundle hull, machinery and liability cover into multi-year relationships with a few lead insurers.
Exporters and trading houses ship goods continuously, so floating policies appeal as a single master contract that replaces many voyage covers. The cargo is declared within a stipulated limit, thus reducing administrative burden and accelerating the certificate process. Digital declaration systems and integration with logistics systems are improving the efficiency of the system. The insurance companies get visibility on the flow of cargos and can change rates even after issuing a policy. Flexibility in such times of uncertain transportations is important for commodity traders and manufacturers. The increasing trade complexities will continue to favor the usage of this system.
⮞Lockton reported in February 2026 that the mean general increase requested across International Group P&I clubs was 6% for the 2026 renewal. The annual renewal cycle illustrates the time-based structure that continues to anchor premium flows.
By Distribution Channel, Brokers Dominates the Marine Insurance Market and Digital Distribution Grows Fastest
Brokerage placement is common due to the complexity of marine risks and the dispersion of capacity across Lloyd’s, company markets, and mutual clubs. Large owners of ships and cargoes depend upon brokers to formulate programs and negotiate wordings as well as to argue on behalf of their claims. The world's top brokerage firms have dedicated marine departments which allow them to benchmark pricing across carriers. Their information about loss experience and sanctions risk enables their clients to set limits and deductibles. Intermediaries have become central during war risk disruption because they track listed area changes and arrange short-notice quotes. Competition among brokers now rests on analytics, risk engineering support and claims performance.
Small and mid-sized shippers want instant quotes and certificates without lengthy broking cycles, which is lifting digital distribution. Embedded insurance inside freight forwarding and e-commerce platforms is bringing cargo cover to new buyers. Application programming interfaces let platforms issue cover at the point of booking. Parametric triggers for delay or temperature excursion are being tested to speed settlements. Insurers are investing in underwriting engines that price shipments automatically from route, commodity and carrier data. The model lowers acquisition cost for low-value consignments. Regulatory acceptance of electronic documents is further supporting adoption across Asia Pacific and Europe.
⮞In December 2025, Marsh reported that the cost of war risk cover for Russian Black Sea port calls had more than tripled from a base of 0.25% to 0.3% of ship value. Rapid repricing of this kind keeps brokers at the center of placement for high-risk voyages.
By End User, Shipping Companies Dominates the Marine Insurance Market and Freight Forwarders Grows Fastest
Shipping companies purchase the widest bundle of cover because they carry hull, machinery, P&I, war and loss-of-hire exposure at the same time. Fleet owners and operators use insurance to satisfy lenders, charterers, port states and flag requirements. Tight tonnage supply and high newbuilding costs have lifted vessel values, which raises insured sums and premiums. Age of vessels and larger container ships create a higher risk of fires and casualties. Companies have to manage sanctions screening, cyber risk, and carbon compliance. Large owners negotiate with carriers through high-deductible, captive structures. Claims management is one of the key underwriter competencies in this sector.
Freight forwarders and logistics providers are adding marine cover as they take on contractual liability for cargo they do not own. Non-vessel operating carriers need liability limits that match customer contracts. E-commerce and multimodal supply chains increase the number of shipments each forwarder handles. Forwarders buy cargo legal liability, stock throughput and contingent cover through master policies. Many also resell cargo insurance to shippers, so they act as a distribution partner as well as a buyer. Digital forwarding platforms embed insurance at the booking stage. Disruption to Suez and Red Sea routings has heightened awareness of delay and rerouting costs in customer contracts.
⮞Allianz Commercial's Safety & Shipping Review 2026 reported 43 total losses of large vessels in 2025, based on data available at its June 2026 release. The low count supports stable pricing for owners while fleet values and routing risks keep insured exposure high.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
United Kingdom |
31.64% |
|
Asia Pacific |
China |
34.87% |
|
North America |
United States |
86.80% |
|
Latin America |
Brazil |
38.52% |
|
Middle East and Africa |
United Arab Emirates |
27.19% |
Europe Marine Insurance Market Insights
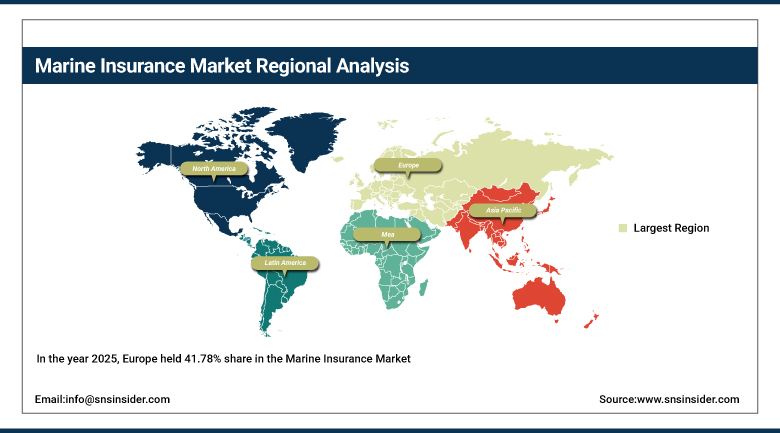
In the year 2025, Europe held 41.78% share in the Marine Insurance Market had due to Lloyd’s Market of London, hull underwriting experts from Nordic countries, and the International Group of P&I Clubs. The UK continues to be the biggest national market due to syndicates of Lloyd's, brokers and expertise in marine claims. Germany and Norway have contributed in terms of large fleets and specialized underwriters. France and Italy have provided cargo and yacht business. Many tonnages of the world are owned by European owners and therefore, premium flows remain high in Europe. Wordings across the world are decided by London war committees and Brussels sanctions regulations.
Regulation shapes underwriting behavior across the region. EU sanctions packages require rigorous vessel screening, and insurers face stricter due diligence on shadow fleet exposure. The extension of emissions trading to shipping adds cost and compliance questions for owners. Consolidation among clubs and specialist managing agents is reshaping competition. Investment in digital underwriting and claims analytics is strongest in the United Kingdom and the Nordic markets. Rotterdam, Hamburg and Antwerp generate steady cargo volumes that sustain open cover demand and keep European carriers close to the largest trade flows. A deep pool of surveyors, adjusters and maritime lawyers in London and Oslo speeds complex claims.
⮞In July 2026, the Council of the European Union adopted its 21st Russia sanctions package, which designated 41 additional vessels for supporting the shadow fleet. The measure raises screening duties for marine underwriters and P&I clubs operating in the region.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Marine Insurance Market Insights
Asia Pacific is projected to expand at a CAGR of 4.97% from 2026-2035, the fastest pace among all regions. The world's busiest container ports in China, Singapore and South Korea generate huge cargo exposure. China leads through Shanghai, Ningbo and Shenzhen while Japan, India and Southeast Asia add shipowning and trading demand. Rising shipbuilding output and growing fleets lift hull and machinery premiums. Regional traders are adopting floating policies and digital certificates faster than many peers. Local insurers are expanding Lloyd's style capacity at home to retain business that once flowed to London.
Singapore and Hong Kong operate as regional hubs for hull, cargo and P&I placement, supported by brokers, clubs and law firms. Japanese insurers and Korean carriers serve large home-based fleets and increasingly write business abroad. India is building capacity under port modernization programs and rising export volumes. Climate exposure from typhoons and flooding adds catastrophe loading to cargo accumulation in coastal hubs. Underwriters in the region also watch Strait of Malacca and South China Sea risk closely, since congestion and political tension can raise claims frequency. Rapid growth in intra-Asian trade keeps regional cargo programs expanding.
⮞In January 2026, Singapore's Senior Minister of State for Transport announced that the port handled 44.66 million TEU in 2025. The volume underlines the cargo and hull exposure concentrated in regional transshipment hubs.
North America Marine Insurance Market Insights
North America covers the United States and Canada and ranks as a mature market with strong energy, grain and container flows. Gulf Coast crude and LNG exports, Pacific Northwest grain shipments and Great Lakes bulk trade create diverse cargo and hull exposure. Canadian ports at Vancouver, Prince Rupert and Montreal handle growing Asia-linked volumes. The Jones Act fleet and inland waterways sustain coastal hull and liability demand. Large commercial carriers write ocean and inland marine alongside property lines, so marine often forms part of broader account negotiations. Rail and truck connections to ports extend cargo policies into inland transit.
Offshore wind construction, port electrification and automation projects are adding builders' risk and marine liability needs along the East Coast. Soft cargo pricing has encouraged carriers to tighten risk selection and focus on technical underwriting. Surplus lines carriers and managing general agents fill gaps for hard-to-place vessels and cargo. Federal support for Gulf shipping has opened a path for American carriers to write war-related cover alongside the London market. Cyber and sanctions compliance rules continue to shape policy language and claims handling for exporters.
⮞In March 2026, the U.S. International Development Finance Corporation selected Chubb to lead a reinsurance plan of about USD 20 billion for Gulf shipping covering hull and machinery and cargo. The program shows how public capital is being used to keep trade lanes insured during conflict.
MEA and Latin America Marine Insurance Market Insights
Middle East and Africa is shaped by Gulf energy exports and by the Suez Canal and Red Sea corridor. The United Arab Emirates serves as the regional marine hub through Dubai ports and a growing insurance center, while Saudi Arabia and Egypt add logistics and canal exposure. War risk premiums and listed area changes dominate underwriting discussions. Africa's port expansion in Morocco, Kenya and South Africa is creating new cargo demand. Local insurers depend heavily on reinsurance and Lloyd's capacity, which makes the region sensitive to global pricing cycles and to political developments affecting key straits.
⮞In March 2026, Windward reported that Strait of Hormuz traffic fell by 80% within 24 hours of the late-February strikes on Iran. The disruption increased demand for war risk cover and strengthened the role of Gulf-based underwriting hubs.
Latin America is led by Brazil, with Mexico and Chile contributing through grain, copper and automotive exports. Panama Canal operations sit at the center of regional cargo and hull risk. Mexico forms part of this regional scope. Loss experience on cargo has been more volatile than in Europe because of theft, port congestion and inland transit hazards. Insurers are investing in tracking tools and regional claims teams to manage these losses. Growth in agricultural exports and nearshoring trade with North America is expected to support steady demand for cargo programs.
⮞In April 2026, the Panama Canal Authority reported 6,288 transits in the first half of fiscal 2026. The steady transit volume sustains cargo and hull exposure across Latin American trade routes.
Growth Drivers: War risk exposure and volatile trade lanes are raising demand for specialist marine cover
Seaborne trade carries most of the world's merchandise by volume, and every disruption on a major lane changes the risk profile of the vessels and cargo moving through it. Conflict in the Gulf and the Black Sea, sanctions enforcement and Red Sea diversions have pushed owners and charterers to buy war risk cover more often and for longer periods. Insurers respond with short-notice quotations and listed area surcharges that lift premium income per voyage. Brokers are expanding war desks to serve shipowners whose routings change within days. Each new corridor under threat adds fresh demand for quotations and capacity.
Fleet value inflation adds a second layer of demand. Newbuilding prices and scarce tonnage raise insured sums on hull and machinery policies, and shipowners also expand limits to match rising replacement costs and lender requirements. Aging vessels and larger container ships increase the severity of fire and casualty losses and sustain premium adequacy. Cargo digitization and parametric triggers broaden access to cover. Decarbonization rules create liability and machinery risks linked to alternative fuels and new engine technology. Together these factors support steady premium growth even when benign loss years soften pricing in cargo.
⮞In March 2026, the Joint War Committee added five countries to its listed areas in circular JWLA-033. The expansion widens the territory where additional war risk premiums apply and so lifts demand for dedicated cover.
Restraints: Regulatory uncertainty and soft pricing are limiting premium growth
Soft pricing is compressing margins in cargo and parts of the hull market. Ample capacity from Lloyd's syndicates, commercial carriers and new managing agents keeps competition intense, and benign loss years encourage buyers to push for lower rates. Reinsurance concentration also affects results, because a small group of reinsurers supports many marine portfolios and sets terms for capacity. When rates fall faster than inflation in vessel values, underwriters face thinner margins and tighter combined ratios across broad segments of the market. Buyers with strong loss records often secure multi-year terms at lower rates, which pressures insurers further.
Regulatory complexity adds cost and delay. Owners and insurers must follow SOLAS and MARPOL rules, sanctions regimes and anti-money-laundering checks, and each requirement can slow claims and renewals. Data gaps on autonomous vessels and cyber events make pricing difficult for new risks. Uncertainty over international decarbonization rules also complicates long-term investment in vessels and the policy terms attached to them. Claims delays after large casualties further test client relationships and raise the administrative burden on smaller carriers. Smaller insurers feel this pressure most because they lack the scale to absorb compliance costs. Slow settlements can also strain relationships with shippers.
⮞In October 2025, International Maritime Organization member states voted 57 to 49, with 21 abstentions, to adjourn adoption of the Net-Zero Framework for one year. The delay extends uncertainty over future fuel and compliance costs that insurers must price into hull and liability cover.
Opportunities: Route recovery, war risk facilities and digital placement are opening new premium pools
Recovery of the Suez route, new war risk facilities and the growth of offshore energy are widening premium pools. As carriers move services back toward Suez, insurers can write more transit cover and cargo programs tied to Asia-Europe flows. Dedicated facilities backed by Lloyd's syndicates and commercial carriers create room for new capacity in the Gulf and Black Sea. Offshore wind installation and LNG transport need builders' risk, marine liability and cargo cover that few traditional programs address in full. Port electrification and automation projects add further construction and liability exposure that needs specialist engineering knowledge.
Digital placement and data-led underwriting offer cost savings and new customer segments. Parametric cargo delay cover, cyber-linked marine liability and cover for alternative-fuel vessels are emerging product lines. Autonomous shipping and Internet of Things monitoring open the way for usage-based pricing. Insurers that combine technical skill with fast quoting can win business from small shippers and forwarders that are underserved by traditional broking. These shifts reward carriers that invest early in analytics, tracking partnerships and flexible policy wordings. Partnerships between insurers and logistics technology firms can accelerate adoption, and early movers build data advantages that improve loss ratios over time.
⮞In October 2026, BIMCO reported that the weekly container throughput through the Suez Canal had averaged 753,000 TEU for the first two weeks of the month. The resumption of some of the capacity is an example of how recovery of a route helps recover transit cover volume.
Recent Developments:
-
In September 2026, Maersk moved four additional services, AE5, AE11, AE12 and ME2, from the Cape of Good Hope back to the Suez Canal route alongside Hapag-Lloyd, joining AE15 and AE19. The shift depends on Red Sea stability and reopens transit cover opportunities for cargo and hull insurers.
-
In April 2026, Beazley announced its intent to launch a Lloyd's marine war consortium with up to USD 1 billion of capacity, split evenly between hull war and cargo war, for vessels and cargoes transiting the Strait of Hormuz. The consortium adds dedicated capacity to a lane where cover is scarce.
-
In April 2026, Optio Group agreed to acquire Gardian Marine, a London managing general agent specializing in builders' risk, ship repairers' liability and voyage and towage insurance. The transaction follows the group's 2025 purchase of Norwegian hull specialist S Insurance and deepens its marine product range.
-
In June 2025, Markel completed its acquisition of The MECO Group, a marine managing general agent with offices in London, Dubai, Shanghai and Hamburg. The deal extends Markel's marine reach across Europe, the Middle East and Asia.
Marine Insurance Market Key Players
-
Gard
-
NorthStandard
-
Skuld
-
The Swedish Club
-
American Club
-
UK P&I Club
-
Britannia P&I
-
Steamship Mutual
-
West of England P&I Club
-
Chubb
-
AXA XL
-
Zurich Insurance Group
-
AIG
-
Berkshire Hathaway Specialty Insurance
-
Sompo International
-
QBE Insurance
-
MS Amlin
-
Hiscox
Marine Insurance Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 35.29 Billion |
| Market Size by 2035 | USD 54.23 Billion |
| CAGR | CAGR of 4.39% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Coverage Type (Cargo, Hull and Machinery, Marine Liability, War and Political Risks, Offshore Energy, and Others) • By Policy Type (Time Policy, Voyage Policy, Floating Policy, Valued Policy, Fleet Policy, and Blanket Policy) • By Distribution Channel (Brokers, Wholesalers, Direct Sales, and Digital Distribution) • By End User (Shipping Companies, Freight Forwarders, Cargo Owners, Ports and Terminals, and Offshore Energy Companies) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Gard, NorthStandard, Skuld, The Swedish Club, American Club, London P&I Club, UK P&I Club, Britannia P&I, Steamship Mutual, West of England P&I Club, Chubb, AXA XL, Allianz Commercial, Zurich Insurance Group, AIG, Berkshire Hathaway Specialty Insurance, Sompo International, QBE Insurance, MS Amlin, Hiscox |

Frequently Asked Questions
Leading companies in the Marine Insurance Market include Gard, NorthStandard, Skuld, Chubb, AXA XL, Allianz Commercial, Zurich Insurance Group, AIG, Sompo International, and QBE Insurance, among others.
Key opportunities include dedicated war risk facilities for Gulf and Black Sea transits, recovery of Suez Canal traffic, offshore wind and LNG project cover, and parametric and cyber-linked marine products.
The major growth factor is expanding war risk and geopolitical exposure on key trade lanes combined with rising vessel values and seaborne trade volumes. Conflict, sanctions and route disruption increase demand for specialist cover and lift premium per voyage.
The Cargo segment dominated the Marine Insurance Market in 2025 with approximately 50.84% share. Its lead reflects the need for protection on every container, bulk and project shipment, supported by letters of credit requirements and growing e-commerce and energy trade volumes.
Europe dominated the Marine Insurance Market in 2025 with approximately 41.78% share. The region is anchored by the Lloyd's market, Nordic hull specialists and the International Group of P&I Clubs, which concentrate underwriting expertise and premium flows.
