
Medical Waste Containers Market Report Scope & Overview:
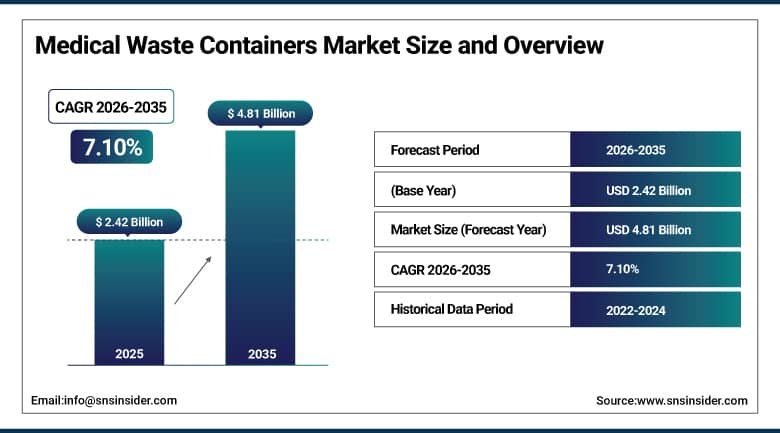
The Medical Waste Containers Market was valued at USD 2.42 Billion in 2025 and is expected to reach USD 4.81 Billion by 2035, growing at a CAGR of 7.10% from 2026-2035.
Medical waste containers are specialised, safety-engineered vessels used for the secure segregation, storage, and transport of hazardous and non-hazardous materials generated within healthcare settings, spanning everything from small sharps containers mounted at a patient bedside through large biohazard bins used in hospital central sterile processing departments. These containers are essential for preventing cross-contamination and protecting healthcare personnel, patients, and waste handlers from exposure to infectious agents, sharp injuries, or toxic substances, and they sit at the intersection of infection control, occupational safety, and environmental regulation in a way few other pieces of healthcare equipment do. U.S. hospitals alone generate over 14,000 tons of medical waste daily, equivalent to approximately 33.8 pounds per patient, a figure that underscores just how much specialised containment capacity a modern healthcare system genuinely requires every single day.
In June 2025, Daniels Healthcare Ltd. launched the 24-litre SHARPSGUARD eco container, an innovative sharps container made from recycled healthcare waste, incorporating up to 80% post-consumer recycled plastic with up to 40% sourced directly from the company's own take-back and recycling programs, aiming to transition healthcare facilities away from conventional virgin-plastic single-use containers.
To Get More Information On Medical Waste Containers Market - Request Free Sample Report
Medical Waste Containers Market Trends:
-
Rising adoption of reusable, washable sharps container systems reducing plastic waste and disposal cost.
-
Growing integration of smart, IoT-enabled containers offering real-time fill-level and location tracking.
-
Expanding use of recycled and bio-based plastics in disposable container manufacturing to meet sustainability goals.
-
Increasing demand for cytotoxic and chemotherapy waste containers reflecting rising global cancer treatment volumes.
-
Rising outsourcing of medical waste collection to specialised route-optimised, technology-enabled service providers.
-
Growing consolidation among waste management providers expanding directly into container manufacturing and design.
U.S. Medical Waste Containers Market Overview:
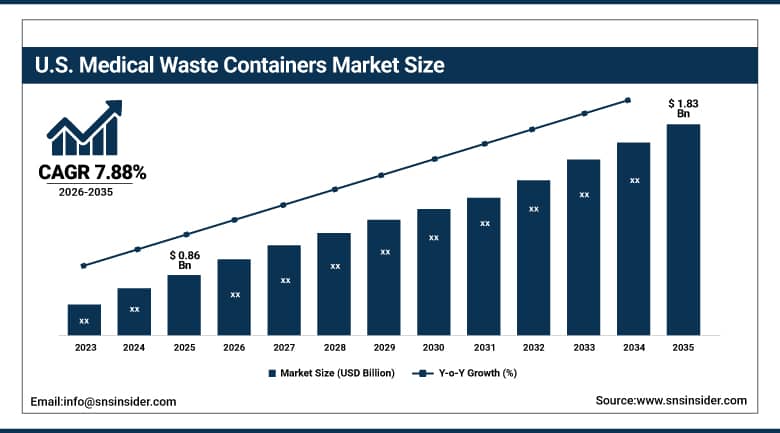
The U.S. Medical Waste Containers Market was valued at USD 0.86 Billion in 2025 and is expected to reach USD 1.83 Billion by 2035, growing at a CAGR of 7.88% from 2026-2035.
The U.S. Medical Waste Containers Market benefits from a vast hospital and healthcare facility network generating substantial daily waste volumes, stringent federal and state biomedical waste disposal regulation, and the presence of leading waste management and container manufacturing companies headquartered in the country that continue to compete on safety design, sustainability, and total service cost. Recent industry consolidation has reshaped the competitive landscape meaningfully, with major waste management companies acquiring established medical waste specialists and continuing to modernise legacy container portfolios that historically spanned well over a hundred distinct product types down to a much smaller, more standardised range. Growing hospital and health system focus on sustainability commitments continues to drive interest in reusable container systems as an alternative to traditional single-use disposal, particularly among larger health systems with dedicated environmental and infection prevention programs.
Stericycle, now operating as WM Healthcare Solutions following its acquisition by Waste Management, launched reengineered Safedrop sharps mail-back and CSRX controlled substance wastage containers using 40 percent less plastic than prior designs, continuing a broader container modernisation strategy that has reduced the company's container portfolio from more than 150 distinct types to fewer than 20 standardised designs.
Medical Waste Containers Market Segment Analysis:
-
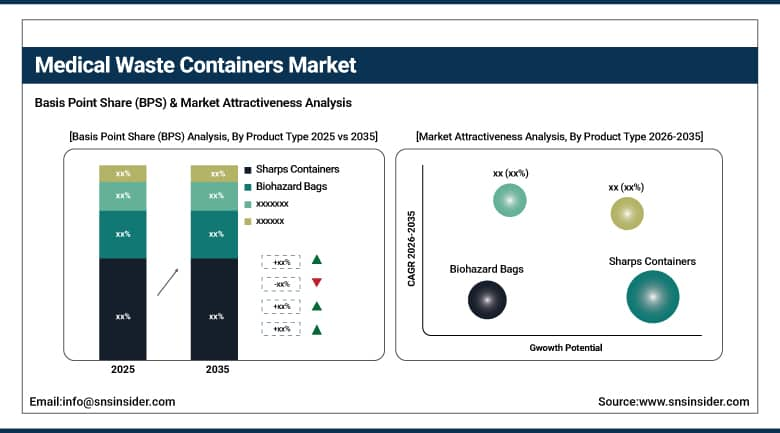
By Product Type, the Sharps Containers segment dominated the market with a 38.60% share in 2025, while the Smart and IoT-Enabled Containers segment is the fastest growing with a CAGR of 11.32% during 2026-2035.
-
By Waste Type, the General Medical Waste segment dominated the market with a 37.95% share in 2025, while the Infectious Medical Waste segment is the fastest growing with a CAGR of 8.35% during 2026-2035.
-
By Material, the Disposable Containers segment dominated the market with a 64.75% share in 2025, while the Reusable Containers segment is the fastest growing with a CAGR of 7.65% during 2026-2035.
-
By End User, the Hospitals and Private Clinics segment dominated the market with a 55.78% share in 2025, while the Veterinary Hospitals and Clinics segment is the fastest growing with a CAGR of 9.49% during 2026-2035.
By Product Type, Sharps Containers Dominates the Market and Smart and IoT-Enabled Containers Grows Fastest
Sharps containers dominated the market in 2025 with a 38.60% share, reflecting the sheer universality of needle and sharps disposal across virtually every healthcare setting worldwide, from large acute-care hospitals through single-provider outpatient clinics and home healthcare settings where patients or caregivers administer injections themselves. Regulatory requirements mandating puncture-resistant, leak-proof sharps disposal are among the most consistently enforced medical waste rules globally, and this near-universal compliance requirement, combined with the sheer volume of needles, syringes, and other sharp instruments generated across the healthcare system every single day, continues to anchor sharps containers as the clear largest product category by a considerable margin over every other container type.
Smart and IoT-enabled containers are projected to be the fastest-growing product category over the forecast period, registering a CAGR of 11.32%, as hospitals increasingly adopt real-time monitoring technology that tracks container fill levels, location, and collection status across large, multi-building healthcare campuses. These connected systems help facilities optimise collection routes, reduce unnecessary early pickups, and strengthen regulatory reporting accuracy, and growing evidence that this technology meaningfully reduces both labour cost and container loss continues to accelerate adoption among larger health systems seeking measurable operational efficiency gains beyond simple containment compliance.
By Waste Type, General Medical Waste Dominates the Market and Infectious Medical Waste Grows Fastest
General medical waste dominated the market in 2025 with a 37.95% share. This broad waste category, encompassing non-hazardous materials generated throughout routine healthcare delivery, continues to represent the largest volume of overall medical waste generated across hospitals and clinics worldwide, and the sheer scale of routine, non-infectious healthcare waste generated during ordinary patient care continues to anchor this category as the clear leading waste type by both volume and overall container revenue.
Infectious medical waste is projected to be the fastest-growing waste type over the forecast period, registering a CAGR of 8.35%, as heightened attention to healthcare-associated infection control, reinforced by tightening regulatory requirements governing the segregation and disposal of potentially contaminated materials, continues to expand demand for properly rated infectious waste containment capacity. Rising global emphasis on infection prevention protocols within hospitals and outpatient facilities alike continues to drive above-market growth for this waste type relative to the broader general-waste-dominated category mix.
By Material, Disposable Containers Dominates the Market and Reusable Containers Grows Fastest
Disposable containers dominated the market in 2025. Single-use design continues to represent the established default standard across the overwhelming majority of medical waste disposal applications, valued for its simplicity, low upfront cost, and the genuine infection control confidence that comes from a container that never needs to be cleaned, transported back to a facility, and reintroduced into circulation, sustaining disposable containers' position as the largest material category across the broader market.
Reusable containers are projected to be the fastest-growing material category over the forecast period, registering a CAGR of 7.65%, as growing hospital sustainability commitments and mounting evidence linking reusable, washable container systems to meaningfully reduced sharps injury rates continue to drive adoption among health systems willing to invest in the collection logistics and industrial washing infrastructure these systems require. Published clinical studies documenting reduced needlestick injury rates alongside genuine plastic waste reduction continue to strengthen the business and clinical case for reusable systems among increasingly sustainability-conscious hospital administrators.
By End User, Hospitals and Private Clinics Dominates the Market and Veterinary Hospitals and Clinics Grows Fastest
Hospitals and private clinics dominated the market in 2025 with a 55.78% share. These facilities continue to generate the overwhelming majority of overall medical waste volume given their scale, patient throughput, and the breadth of clinical procedures performed on any given day, and this fundamental role as the primary point of healthcare delivery continues to anchor hospitals and private clinics as the clear largest end-user category across the broader medical waste containers market by a wide margin over every alternative healthcare setting.
Veterinary hospitals and clinics are projected to be the fastest-growing end-user category over the forecast period, registering a CAGR of 9.49%, as rising pet ownership rates and growing willingness among pet owners to pursue advanced veterinary medical care continue to expand veterinary procedure volumes worldwide. Veterinary practices increasingly face regulatory scrutiny comparable to human healthcare facilities regarding proper medical waste segregation and disposal, and this tightening regulatory environment, combined with genuine procedure volume growth, continues to drive above-market growth for this end-user category relative to the broader hospital-dominated end-user mix.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 |
|
North America |
United States |
81.45% |
|
Europe |
Germany |
26.85% |
|
Asia Pacific |
China |
34.70% |
|
Latin America |
Brazil |
22.15% |
|
Middle East & Africa |
United Arab Emirates |
19.40% |
North America Medical Waste Containers Market Insights
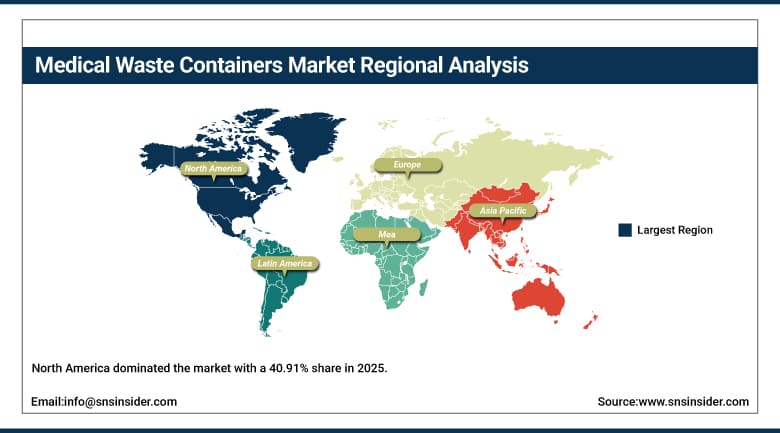
North America dominated the market with a 40.91% share in 2025. A vast, well-established hospital and healthcare facility network, stringent Resource Conservation and Recovery Act and state-level biomedical waste disposal regulation, and the concentration of leading waste management and container manufacturing companies headquartered within the region continue to anchor this leadership position across every major product and waste type category. The scale of U.S. healthcare delivery alone, with hospitals generating over 14,000 tons of waste daily nationwide, continues to sustain enormous underlying demand for properly engineered containment capacity across every care setting from major academic medical centres through small rural clinics.
Canada contributes meaningful incremental regional demand through its own publicly funded healthcare system and comparable regulatory framework governing biomedical waste disposal. Continued industry consolidation among major North American waste management providers, combined with sustained hospital sustainability investment in reusable and smart container technology, is expected to keep North America in the lead through the forecast period, even as its growth rate trails the faster-scaling markets developing across Asia Pacific over the coming decade.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Medical Waste Containers Market Insights
Asia Pacific is projected to be the fastest-growing region over the forecast period, registering a CAGR of approximately 8.93%, buoyed substantially by hospital construction and healthcare infrastructure expansion across China, India, and ASEAN member states. Rapid healthcare facility buildout across the region continues to create genuinely new demand for medical waste containment capacity in markets that historically lacked the formalised, regulated waste management infrastructure common across more established healthcare systems, and this infrastructure gap represents a substantial and still largely untapped growth opportunity for container manufacturers entering these markets early.
China anchors regional demand through its enormous and rapidly expanding hospital network, supported by sustained government healthcare infrastructure investment across both public and private facility construction. India contributes substantial regional growth as its own healthcare system continues to formalise medical waste management practices under tightening national regulation, while Japan and South Korea add mature, technology-oriented demand through established healthcare systems increasingly adopting smart, connected containment technology.
Europe Medical Waste Containers Market Insights
Europe holds a significant share of the global market, anchored by Germany's substantial hospital sector and its position as home to several of the region's leading medical waste management and container manufacturing companies with deep regulatory compliance expertise built over decades of operating under some of the world's most stringent biomedical waste rules.
The United Kingdom, France, and the Nordic countries add consistent regional demand as national health systems continue extending sustainability-focused waste management practices, including growing adoption of reusable sharps container systems supported by published clinical evidence of reduced needlestick injury rates. Continued European regulatory tightening around single-use plastic reduction is expected to sustain steady growth in reusable container adoption across the broader European market through the forecast period.
MEA and Latin America Medical Waste Containers Market Insights
The Middle East and Africa region is supported by growing healthcare infrastructure investment across the United Arab Emirates and Saudi Arabia, where regional governments continue expanding hospital capacity and formalising medical waste management regulation as part of broader healthcare modernisation and public health strategies targeting rapidly growing, increasingly urbanised regional populations.
Latin America is anchored by Brazil, where a growing domestic healthcare sector and expanding regulatory enforcement of proper medical waste segregation continue to sustain steady demand for compliant containment solutions. Mexico contributes further incremental growth as regional healthcare access and regulatory formalisation continue to expand gradually across both public and private facility networks throughout the broader region.
Market Dynamics:
Growth Drivers: Healthcare Activity Growth and Tightening Waste Regulation
Increasing healthcare activities worldwide stand as the primary growth driver, as rising hospital admissions, outpatient procedure volumes, and diagnostic testing activity continue to generate correspondingly higher volumes of medical waste requiring proper containment and disposal across every major healthcare system globally. U.S. hospitals alone generate over 14,000 tons of waste daily, a figure that continues to climb alongside population growth, an ageing patient base requiring more frequent medical intervention, and expanding healthcare access across previously underserved populations in both developed and emerging economies.
Tightening biomedical waste disposal regulation represents a second major driver, as governments worldwide continue strengthening requirements governing the segregation, containment, and disposal of infectious, hazardous, and radioactive medical waste. Growing global emphasis on safe medical waste management practices continues to reinforce sustained investment in compliant containment infrastructure, and healthcare facilities that fail to meet increasingly stringent regulatory standards face genuine financial and reputational risk that continues to keep compliance-driven container purchasing a consistent, non-discretionary line item across healthcare facility operating budgets.
Restraints: High Compliance Costs and Regulatory Complexity
High costs associated with regulatory compliance remain a genuine restraint, as smaller healthcare facilities and clinics in emerging economies can struggle to absorb the capital and ongoing operational expense that properly engineered, regulation-compliant medical waste containment systems require, particularly when weighed against other pressing healthcare infrastructure investment priorities competing for the same limited facility budgets.
Regulatory complexity presents a further restraint, as biomedical waste disposal rules continue to vary considerably between countries, and in some cases between individual states or provinces within the same country, creating genuine operational complexity for healthcare systems and multinational container manufacturers alike that must navigate an inconsistent, continuously evolving patchwork of local, national, and international waste management requirements across every market they serve.
Opportunities: Smart Container Technology and Sustainable Material Innovation
Continued development of smart, IoT-enabled container technology represents a substantial opportunity, as manufacturers that can deliver genuinely reliable real-time fill-level monitoring and route optimisation capability stand to capture demand from larger health systems seeking measurable operational efficiency gains and improved regulatory reporting accuracy beyond simple containment compliance alone.
Continued expansion into emerging economies experiencing rapid hospital construction offers a further avenue for growth, despite ongoing challenges including high upfront costs and regulatory complexity in some of these markets, as manufacturers that can establish early distribution relationships and support local regulatory formalisation efforts are positioned to capture substantial long-term demand from healthcare systems still in the relatively early stages of building out formal medical waste management infrastructure.
Recent Developments:
-
2026, Sharpak Healthcare and Tradebe Environmental Services Healthcare entered into a long-term partnership to deploy Sharpak’s reusable Zero sharps containers together with Tradebe’s NOLOSS automated sanitisation system. The service is intended to support reusable sharps-container programs for NHS healthcare customers across England, Wales, and Scotland.
-
2026, Orion Medical Supplies acquired Vernacare’s Harm Reduction business, while entering an exclusive partnership under which Orion will source its sharps containers from Vernacare. The transaction strengthens Orion’s harm-reduction portfolio while allowing Vernacare to focus on infection prevention and clinical waste-management solutions.
-
2025, Daniels Healthcare launched its 24L SHARPSGUARD eco container, manufactured using up to 80% post-consumer recycled plastic, with up to 40% sourced directly from NHS clinical waste. The product represents a closed-loop approach to sharps-container manufacturing and is designed to reduce reliance on virgin plastic.
-
2026, WM highlighted Stericycle’s reusable sharps-container service following Stericycle’s integration into WM. The service uses a collection, treatment, cleaning, and return cycle to reduce reliance on single-use sharps containers and support more circular medical-waste management.
Medical Waste Containers Market Key Players:
-
Stericycle, Inc. (WM Healthcare Solutions)
-
Daniels Health Inc.
-
Sharps Compliance, Inc.
-
Medline Industries, LP
-
Waste Management, Inc.
-
Republic Services, Inc.
-
Clean Harbors, Inc.
-
Veolia Environmental Services
-
Suez Environmental Services
-
Remondis SE & Co. KG
-
Becton, Dickinson and Company
-
Thermo Fisher Scientific Inc.
-
Bondtech Corporation
-
MedPro Disposal, LLC
-
Curtis Bay Medical Waste Services
-
Sage Products, LLC (Stryker)
-
Cardinal Health, Inc.
-
Simple Waste Solutions, LLC
-
Tri-State Bio-Medical Waste
-
GRIF Manufacturing, Inc.
Medical Waste Containers Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.42 Billion |
| Market Size by 2035 | USD 4.81 Billion |
| CAGR | CAGR of 7.10% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Sharps Containers, Biohazard Bags, Pharmaceutical Waste Containers, General Medical Waste Containers, and Smart and IoT-Enabled Containers) • By Waste Type (General Medical Waste, Infectious Medical Waste, Hazardous Medical Waste, and Radioactive Medical Waste) • By Material (Disposable Containers and Reusable Containers) • By End User (Hospitals and Private Clinics, Diagnostic Laboratories, Veterinary Hospitals and Clinics, and Home Healthcare Settings) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Stericycle, Inc. (WM Healthcare Solutions), Daniels Health Inc., Sharps Compliance, Inc., Medline Industries, LP, Waste Management, Inc., Republic Services, Inc., Clean Harbors, Inc., Veolia Environmental Services, Suez Environmental Services, Remondis SE & Co. KG, Becton, Dickinson and Company, Thermo Fisher Scientific Inc., Bondtech Corporation, MedPro Disposal, LLC, Curtis Bay Medical Waste Services, Sage Products, LLC (Stryker), Cardinal Health, Inc., Simple Waste Solutions, LLC, Tri-State Bio-Medical Waste, GRIF Manufacturing, Inc. |

Frequently Asked Questions
Key players include Stericycle, Inc., Daniels Health Inc., Sharps Compliance, Inc., Medline Industries, LP, and Waste Management, Inc., among other medical waste management companies.
Continued development of smart, IoT-enabled container technology and continued expansion into emerging economies experiencing rapid hospital construction represent the primary opportunities.
Growth is primarily driven by increasing healthcare activities worldwide, combined with tightening biomedical waste disposal regulation.
By Product Type, Sharps Containers dominated the market with a 38.60% share in 2025, reflecting the near-universal requirement for puncture-resistant sharps disposal.
North America dominated the market with a 40.91% share in 2025, supported by a vast healthcare facility network and stringent biomedical waste regulation.
