
Microinsurance Market Report Scope & Overview:
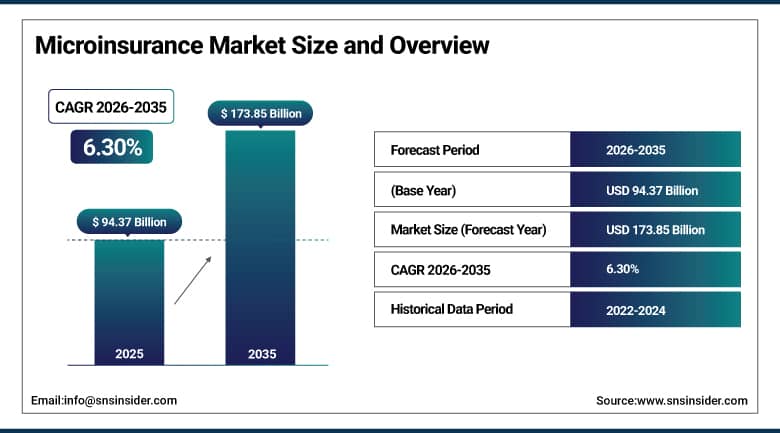
The Microinsurance Market was valued at USD 94.37 Billion in 2025 and is expected to reach USD 173.85 Billion by 2035, growing at a CAGR of 6.30% from 2026-2035.
The Microinsurance Market is scaling as mobile money, government schemes and insurer partnerships reach households that formal cover never served. Premium tickets are small but policy volumes are very large. Life and accident covers lead today. Health and parametric crop covers are growing faster. Telecom operators, microfinance lenders and fintech platforms now sell cover at the point of payment. Regulators are creating inclusive product rules and lighter filing paths. Insurers are using satellite data and automated claims to cut cost per policy. Asia Pacific holds the largest customer base while Africa and Latin America add the most new products. Climate shocks and informal employment keep demand rising.
⮞In November 2025, GSMA reported that only 12% of the target population for microinsurance was covered in 2023. The gap shows how much room remains for mobile-enabled distribution to extend cover to unserved households.
To Get More Information On Microinsurance Market - Request Free Sample Report
Microinsurance Market Trends
-
Mobile wallets and telecom operators are becoming the primary sales channel for low-cost cover.
-
Parametric and index products are replacing loss assessment in agriculture and climate-exposed trades.
-
Regulators are creating dedicated microinsurance licenses and capped-charge product rules.
-
Embedded cover inside loans, ride platforms and e-commerce checkouts is widening the buyer base.
-
Hospital cash and telemedicine bundles are moving health microinsurance beyond single-benefit plans.
U.S. Microinsurance Market Outlook
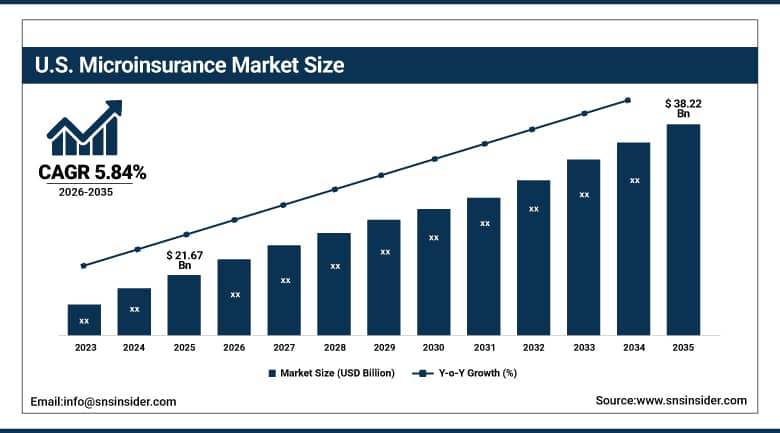
The U.S. Microinsurance Market was valued at USD 21.67 Billion in 2025 and is expected to reach USD 38.22 Billion by 2035, growing at a CAGR of 5.84% from 2026-2035.
The U.S. Microinsurance Market is tiny compared to developing countries, but is picking up steam due to small coverages offered to gig economy workers, renters, and financially underserved consumers. Households have no savings and no access to formal sources of credit. Insurtechs offer protection on a trip, shift, or day basis via mobile apps. Community Development Financial Institutions and credit unions combine low-cost life and accident coverage with small loans. Protection of gig workers is now being provided by employers and platform providers at their expense. The carriers view microinsurance as a way to expand into new market segments and gain additional behavioral insights. Regions at risk of disasters are experimenting with parameter-based payouts for small businesses and lower-income homeowners.
⮞In November 2024, the Federal Deposit Insurance Corporation reported that 4.2% of U.S. households were unbanked in 2023. The unbanked population forms a core target group for low-cost protection products and digital onboarding.
Microinsurance Market Segment Analysis
-
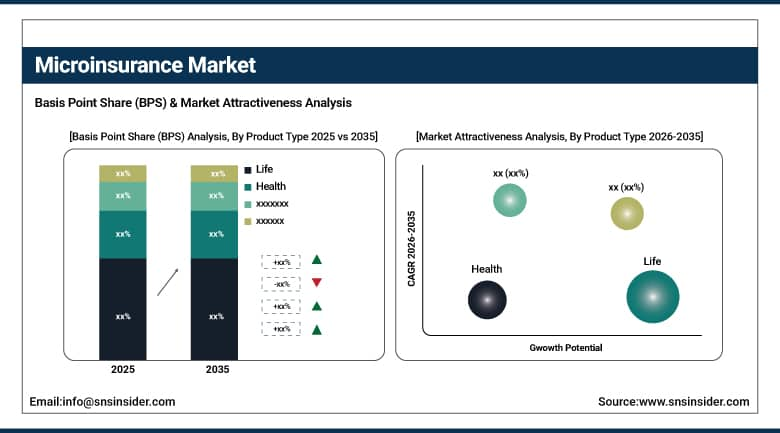
By Product Type, the Life segment dominated the Microinsurance Market with approximately 44.41% share in 2025, while the Health segment is the fastest growing with a CAGR of approximately 7.18%.
-
By Provider, the Commercially Viable segment dominated the Microinsurance Market with approximately 65.57% share in 2025, and is also the fastest growing with a CAGR of approximately 7.17%.
-
By Model Type, the Partner Agent segment dominated the Microinsurance Market with approximately 43.58% share in 2025, and is also the fastest growing with a CAGR of approximately 8.70%.
-
By Distribution Channel, the Financial Institutions segment dominated the Microinsurance Market with approximately 33.00% share in 2025, while the Digital Channels segment is the fastest growing with a CAGR of approximately 7.77%.
By Product Type, Life Dominates the Microinsurance Market and Health Grows Fastest
Life and accident covers lead microinsurance because they are simple to price and easy to explain to first-time buyers. Credit life attached to microloans gives lenders and borrowers an obvious reason to buy. Funeral and accidental death products match the immediate cash needs of low-income families. Group structures reduce underwriting cost since no medical exam is needed. Government schemes in India and other countries enrol tens of millions of people in accident and life plans at very low premiums. Insurers value the predictable claims patterns and long distribution relationships with lenders and cooperatives. Product simplicity also supports mobile sales through USSD menus and agent networks.
Health cover is advancing quickly as out-of-pocket medical costs push families into debt. Hospital cash, outpatient and telemedicine bundles are replacing single-benefit designs. Now that digital means of verification have been implemented in mobile health platforms and clinics, payment time is reduced. There is increasing targeting of women and informal employees since they face more risks associated with their health uninsured. Public-private models ensure wider access to insurance benefits via premium subsidy and risk pooling mechanisms. Insurance companies rely on data contained in the mobile wallets for pricing and renewal of insurance policies without much bureaucracy.
⮞As of March 2025, the Government of India reported 50.54 crore cumulative enrolments in the Pradhan Mantri Suraksha Bima Yojana accident insurance scheme. The enrolment base shows the scale that low-premium accident and life covers can reach through bank accounts.
By Provider, Commercially Viable Dominates the Microinsurance Market and Also Grows Fastest
Commercially viable providers lead because insurers, microfinance lenders and fintech platforms can fund growth from premiums rather than subsidies. Their products are priced to cover claims, distribution and administration costs at scale. Banks and telecom operators provide customer data and payment rails that cut acquisition costs. Regulators in several markets now license dedicated microinsurers with reduced capital requirements, which encourages new entrants. Reinsurers support commercial portfolios with capacity for catastrophe and agricultural risk. Product design focuses on low cost per policy, automated enrolment and digital claims. Investors see a path to profit where volumes are high and loss ratios are managed through technology.
Government-supported and donor-financed systems are still key in rural healthcare and crop insurance, but commercial models are catching up in those. Subsidies on premiums now go hand in hand with private underwriting and delivery to broaden coverage. Mutual and cooperative organizations bring community confidence and inexpensive distribution into play. Commercial designs enable public finance to reduce the cost for farmers, while insurance companies bear the risks. Performance-linked financing and index triggers streamline administration. With better data availability, an increasing number of schemes shift to commercial viability over time.
⮞The ICMIF Foundation and the Microinsurance Network started mapping exercise in January 2026 following their findings that less than 20 out of 294 organizations in the 2024 Landscape of Microinsurance were either mutual, cooperative, or community-owned institutions. The data deficiency clearly indicates the domination of the market by commercial institutions.
By Model Type, Partner Agent Dominates the Microinsurance Market and Also Grows Fastest
Partner-agent models dominate because insurers rely on lenders, retailers and telecom operators that already hold customer trust. The insurer underwrites while the partner enrols customers and collects premiums. The bundling of loans, mobile top-ups, and wallet payments reduces costs and increases renewal rates. Embedded sales involve insuring customers during their daily transactions like taxi journeys or even buying of data packages. The insurance companies retain risk skills while marketing and customer services are left to the partners. The model scales quickly across countries that have similar partner networks.
Growth is strongest where partners can sell through digital channels and automate claims. Application interfaces connect insurers to wallets and super-apps so enrolment takes minutes. Embedded cover for gig workers, farmers and small traders expands the addressable base. Partners increasingly share data that improves pricing and fraud detection. Full-service insurers and community-based mutuals continue to serve specific groups yet often use partner links for distribution. Regulators are clarifying agent conduct rules to protect customers in these arrangements. The model is expected to anchor product launches across Africa, South Asia and Latin America.
⮞Britam reported in March 2025, at the launch of Britam Connect in Kenya, that more than 4 million Kenyans were insured through its microinsurance business. The embedded model with transport and telecom partners shows how partner channels extend reach.
By Distribution Channel, Financial Institutions Dominates the Microinsurance Market and Digital Channels Grows Fastest
Financial institutions anchor distribution because banks, microfinance lenders and cooperatives hold the customer relationship and the repayment data. Cover is attached to loans and savings accounts, which lowers acquisition cost. The branch staff and loan officers describe the products using the local languages. The premium collection happens via the already existing payment schedules, thus maintaining a low lapse rate. There is also profit for the lenders in the form of credit protection that ensures that any losses in case of defaults remain minimal. The insurance companies appreciate the consistency of volume and the reliability brought about by long-term clients.
Digital channels are expanding as smartphones, USSD menus and mobile wallets reach remote households. Customers can buy, renew and claim without visiting a branch. Telecom operators bundle cover with airtime and data. Micromodules have been incorporated into the super-apps and e-commerce apps during the time of transaction. Chatbots and the verification process are used by insurance firms in order to reduce service costs. The use of satellite and weather information makes it feasible for instantaneous index payment to farmers through mobile money. Trust and digital literacy remain a concern but declining data costs improve coverage.
⮞In April 2026, MAPFRE reported a target of 250,000 customers by the end of 2026 for its A Tu Lado microinsurance program in Brazil, Colombia and Peru. Microfinance institutions support distribution, which illustrates the role of financial institutions in reaching new buyers.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
India |
48.73% |
|
North America |
United States |
87.90% |
|
Europe |
Germany |
38.46% |
|
Latin America |
Brazil |
41.82% |
|
Middle East and Africa |
South Africa |
33.19% |
Asia Pacific Microinsurance Market Insights
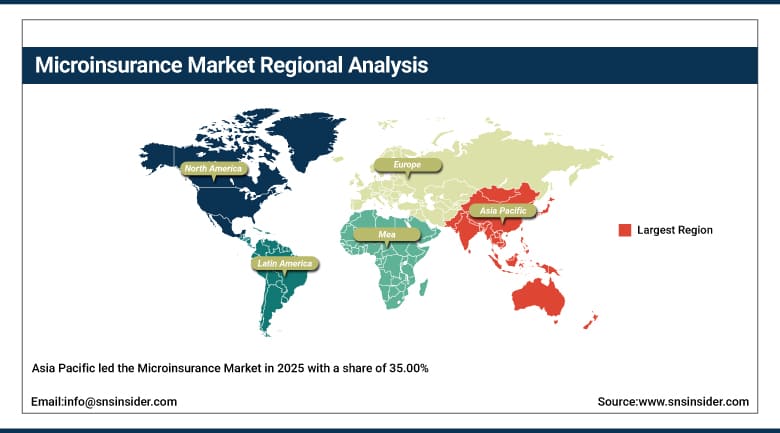
Asia Pacific led the Microinsurance Market in 2025 with a share of 35.00%, supported by the largest base of low-income households and strong state sponsorship. India dominates regional demand through government accident and life schemes and microfinance-linked cover. The Philippines is a hub for mutual benefit associations that serve millions of members. Indonesia, Bangladesh and Vietnam add mobile and agricultural products. Rapid smartphone adoption lets insurers sell through wallets and super-apps. Insurers and lenders work with regulators to create simplified product rules. Climate exposure to floods and cyclones keeps parametric and crop covers on policy agendas.
It is also the most rapidly growing region, at an expected CAGR of 6.75% between 2026 and 2035. The regulators have been relaxing the process of filing and have capped the fees to ensure that the insurance products remain affordable. Digital identity technology and real-time payment systems reduce onboarding and claims costs. The mutual and cooperative business models like those in the Philippines are expanding their trust-based network. Large insurers in India and Southeast Asia are launching group micro plans with lenders. Remaining challenges include low awareness, rural connectivity gaps and uneven claims service quality across smaller providers.
⮞In January 2025, the Insurance Commission of the Philippines issued Circular Letter 2025-01, which caps premiums and charges for inclusive micro products at 7.5% of the Metro Manila non-agricultural daily minimum wage. The rule sets an affordability benchmark for insurers serving low-income buyers.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Microinsurance Market Insights
North America is a developed market where microinsurance appears as small-ticket protection for gig workers, renters, immigrants and the underbanked. The United States accounts for the bulk of regional demand while Canada adds community-based credit union programs. Insurtechs sell per-use accident and income protection through apps. Community development lenders and nonprofits bundle low-cost life and disability cover with small loans. Employers and platform companies fund cover for independent contractors. Regulators focus on disclosure and fair pricing for low-limit products. Growth depends on trust, easy digital onboarding and partnerships with community organizations.
Disaster exposure creates a second use case. Hurricanes, floods and wildfire parametric payouts are effective at helping poor households and small businesses to recover fast without delays in claim processing. Reinsurers and development finance organizations invest in pilot projects which will be replicated later. Insurance companies look at microinsurance as an opportunity to gain knowledge about underserved markets and collect information on the behavior of different people. Cross-border remittance systems are experimenting with bundling insurance into packages for migrants. Lower cost of premium collection is facilitated by using fintech wallets and payroll cards.
⮞In May 2026, the Federal Reserve Board reported that 63% of U.S. adults would cover a USD 400 emergency expense using cash or its equivalent in 2025. The thin savings buffer supports demand for low-cost protection against sudden shocks.
Europe Microinsurance Market Insights
Europe is a mature but selective market where microinsurance supports migrants, refugees, microentrepreneurs and low-income households at risk of poverty. Germany, the United Kingdom and France host the largest insurers and nonprofit programs. The European Union backs inclusive finance through the European Investment Bank and the European Commission, which fund guarantees and technical assistance for microfinance providers. Mutuals and cooperatives bring trust-based distribution in southern and eastern Europe. Insurers also use European platforms to design products for partner markets in Africa and Asia.
Regulation shapes the market. Solvency rules and conduct standards raise compliance costs for small covers, so many European players act as reinsurers or partners to emerging-market programs. Digital insurance companies try out pay-per-use insurance for freelancers and micro-businesses. Social inclusion initiatives and local authorities help develop affordable insurance products for disadvantaged groups. The impact of climate change raises the demand for affordable insurance for floods and storms among micro-businesses. Competition from social welfare programs limits the transaction volume, although innovations continue in digital underwriting and open finance.
⮞As Eurostat reported in April 2025, 93.3 million people across the European Union, or 21.0% of its population, were at risk of poverty and social exclusion in 2024. The large vulnerable population underpins demand for low-cost protection and inclusive insurance products.
MEA and Latin America Microinsurance Market Insights
Middle East and Africa is led by South Africa, Kenya, Nigeria, Ghana and Egypt. Mobile money drives sales of funeral, health and agricultural covers. Telecom operators partner with insurers to enrol customers through wallets and USSD menus. Index insurance protects smallholder farmers from drought. Regulators at the national level are developing micro-insurance licenses and capital requirements, while Egypt has thrown open the door to specialized micro-insurers. Premium subsidies and pilot projects are funded by development organizations and reinsurers. The informal sector has significant representation, and this increases the need for insurance products that are affordable.
⮞In October 2025, Pula Advisors reported that five Ethiopian insurers formed the Agricultural Insurance Consortium of Ethiopia with a commitment to scale index-based insurance to 3 million smallholder farmers by 2026. The commitment shows how consortium models are expanding agricultural microinsurance in Africa.
Latin America is led by Brazil, with Mexico, Colombia and Peru adding growth through microfinance-linked and parametric covers. Banks, cooperatives and microfinance institutions distribute life, health and funeral products. Peru has set premium caps for microinsurance products and other regulators are following with simplified rules. Climate exposure drives agricultural and weather index covers. Mexico forms part of this regional scope. Insurers invest in mobile channels and community agents to reach rural households. Low insurance penetration and informal work leave a large unserved population.
⮞In August 2026, the Insurance Development Forum reported that parametric cover issued in Colombia protects 14,402 smallholder farmers against drought and excess rainfall. The program shows how public and private partners are scaling climate microinsurance in the region.
Growth Drivers: Financial inclusion programs and mobile distribution are expanding the insured base
Government inclusion programs and bank account expansion create the base for microinsurance sales. Low-premium accident, life and health schemes enrol large populations through payment and savings accounts. Digital identity and real-time payments cut enrolment time and claims friction. Inclusivity is brought about by the regulator through proper product design, reduction of filing costs, and adjustments of charges. The insurance company works together with the lender to include insurance coverage in the loan package, thus widening coverage within a short time. The development organization helps to increase premiums and technical assistance to the new buyer.
Technology increases the reach even further, as telecom organizations sell insurance products via airtime and wallets. Satellite and weather data assist in index insurance products that payout fast after drought and floods. Climate shocks and informal employment raise the cost of unprotected risk, which strengthens demand among farmers and small traders. Reinsurers provide capacity that lets insurers price small-ticket covers sustainably. Together these forces move microinsurance from pilots to national programs and give insurers the volume needed to cover fixed costs.
⮞In July 2025, the Reserve Bank of India reported that its Financial Inclusion Index stood at 67.0 for March 2025. The index reflects wider access to accounts and payments that supports microinsurance enrolment.
Restraints: Low awareness, trust gaps and thin margins are limiting microinsurance penetration
Low awareness and lack of trust hinder penetration by first-time purchasers. Most families are without policies and do not believe their claims would be honored. Insurance fraud by unauthorized agents and delays in settling claims contribute to the problem of distrust. Premiums are too small to generate sufficient revenue for marketing and administration; hence insurers require enormous sales volume to break even. Lack of actuarial information on poor segments adds difficulty to pricing.
There is increased cost from regulatory fragmentation. The capital requirement, licensing structure, and data privacy regulations are different in each nation, thereby impeding the growth of regional markets. Gaps in rural connections constrain the potential for online transactions and claims. Losses are likely to be concentrated due to climate change incidences in a limited portfolio, meaning there is continued reliance on reinsurance. There is no payment of premiums beyond the first year, thereby reducing the lifetime value of a customer.
⮞In August 2026, CGAP reported that only 23% of Mexican adults held any insurance in 2024. The low coverage shows the awareness and access barriers that limit microinsurance penetration.
Opportunities: Parametric climate cover and embedded digital products are creating new premium pools
Parametric and index-based insurance provides quick claim payouts without the need to assess damages, which is ideal for farmers, fishermen and street vendors. Premiums for climate resilience are paid by governments and development banks, thus providing predictable volume. Use of satellite and weather information makes triggers more precise and reduces basis risk. Capacity for catastrophe insurance is provided by reinsurance companies and climate funds. Examples from the Caribbean and Africa show how regional pools can bring down costs.
Embedded and digital distribution opens large untapped groups. Gig workers, women entrepreneurs and informal traders can buy cover through apps and wallets. There is a ready market available to telecommunications and fintech companies. The combination of health microinsurance, telemedicine, and cashless admission to hospitals will assist in controlling the rising cost of medical care. Cyber and small business insurance is the emerging insurance product from the micro-insurance market. Companies that can integrate affordable technology with community trust will attract new customers.
⮞The CCRIF SPC introduced the CCRIF Microinsurance Facility in July 2025 and began its first parametric Livelihood Protection Policy in five Caribbean nations. This demonstrates how regional pooling facilities can expand climate microinsurance to small farmers and traders.
Recent Developments:
-
In July 2026, CIC Insurance Group launched CIC Impact, a dedicated microinsurance subsidiary in Kenya designed to offer affordable cover to informal-sector workers. The subsidiary gives the group a focused vehicle for low-ticket products and extends cover to households that mainstream insurers rarely reach.
-
In August 2026, EIB Global announced a grant with the World Food Programme to support index-based microinsurance in Ethiopia, which is expected to cover 210,000 smallholder farmers. The scheme includes a Premium Guarantee Fund and works with private insurers, which strengthens climate-risk protection for rural households.
-
In October 2026, Turaco and VisionFund International signed a memorandum of understanding to sell insurance through VisionFund's microfinance network, with Kenya and Uganda as anchor markets. Turaco's existing products in those markets have covered about 250,000 people, and expansion to Tanzania, Ghana, Zambia and Rwanda is under consideration.
-
In January 2025, Bancamia and SBS Seguros Colombia launched a microinsurance portfolio for microentrepreneurs covering life, health, funeral, critical illness and parametric damage to productive units. The parametric component uses satellite-triggered payouts for excess rain, drought and earthquakes, which gives small business owners faster protection.
Microinsurance Market Key Players
-
MAPFRE
-
Hollard
-
CARD Pioneer Microinsurance (CARD MBA)
-
Life Insurance Corporation of India
-
Tata AIA Life Insurance
-
Bajaj Life Insurance
-
Shriram Life Insurance
-
SBI Life Insurance
-
HDFC Life
-
Jubilee Health Insurance
-
Turaco
-
Pula Advisors
-
ACRE Africa
-
BIMA
Microinsurance Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 94.37 Billion |
| Market Size by 2035 | USD 173.85 Billion |
| CAGR | CAGR of 6.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Life, Health, Property, Index, Accidental Death and Disability, and Others) • By Provider (Commercially Viable, Aid or Government Support, and Others) • By Model Type (Partner Agent, Full-Service, Provider Driven, and Community-Based) • By Distribution Channel (Direct Sales, Financial Institutions, Digital Channels, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CIC Insurance Group, MAPFRE, Hollard, CARD Pioneer Microinsurance (CARD MBA), Britam Holdings, Life Insurance Corporation of India, Tata AIA Life Insurance, Bajaj Life Insurance, Shriram Life Insurance, SBI Life Insurance, HDFC Life, Jubilee Health Insurance, Turaco, Pula Advisors, ACRE Africa, BIMA |

Frequently Asked Questions
The major growth factor is the expansion of financial inclusion programs and mobile distribution, which bring low-income and informal workers into formal insurance. Digital identity, real-time payments and telecom partnerships cut enrolment and claims costs and make small-ticket covers viable at scale.
The Life segment dominated the Microinsurance Market in 2025 with approximately 44.41% share. Its lead reflects simple pricing, credit-linked life and funeral covers, and government accident and life schemes that enrol very large numbers of low-income households.
