
Natural Language Understanding Market Report Scope & Overview:
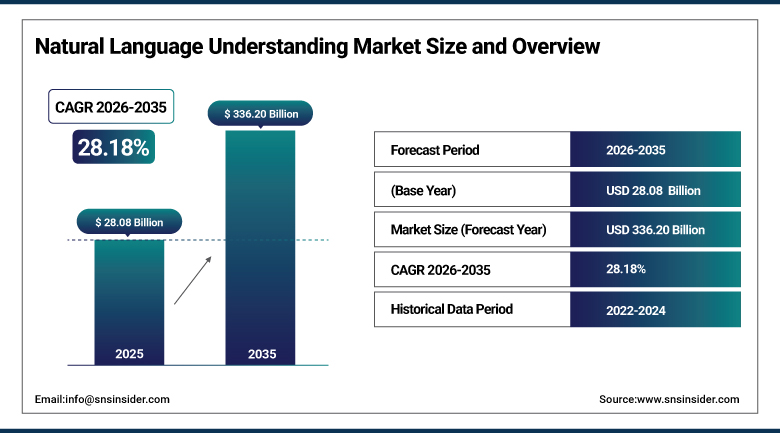
The Natural Language Understanding Market was valued at USD 28.08 Billion in 2025 and is expected to reach USD 336.20 Billion by 2035, growing at a CAGR of 28.18% from 2026-2035.
The Natural Language Understanding Market is growing as software learns to read intent, entities, sentiment and context in text and speech. Large language models have replaced rule-based parsers in many products, and companies now use them to power chatbots, virtual agents, search, document processing and translation. Contact centers, banks and software vendors are the heaviest buyers. Cloud application programming interfaces make the technology available to small teams, while enterprises build governed agent platforms around it. Multilingual support is widening use in markets beyond English.
⮞In January 2026, the OECD reported that more than one-third of people across its member countries used generative AI tools in 2025. Wide public use is training users to speak and write to software in natural language.
To Get more information Natural Language Understanding Market - Request Free Sample Report
Natural Language Understanding Market Trends
-
Large language models replacing rule-based and statistical parsers
-
Agentic platforms that act on user intent across business systems
-
Voice and text understanding combined in single multimodal models
-
Multilingual and low-resource language support
-
Domain-tuned models for finance, health and customer service
U.S. Natural Language Understanding Market Outlook
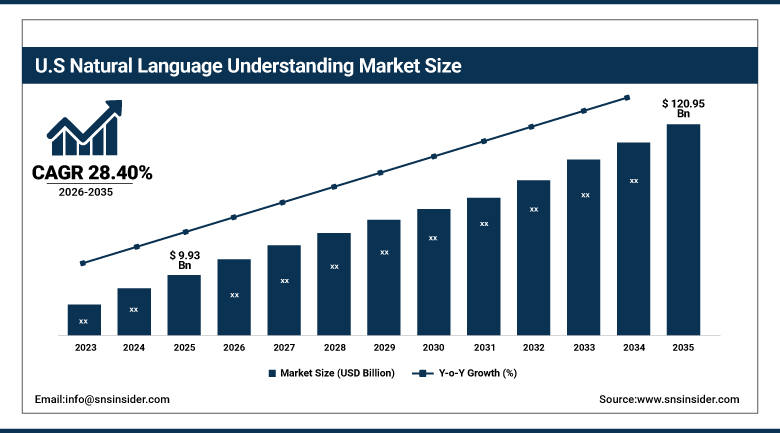
The U.S. Natural Language Understanding Market was valued at USD 9.93 Billion in 2025 and is expected to reach USD 120.95 Billion by 2035, growing at a CAGR of 28.40% from 2026-2035.
The U.S. Natural Language Understanding Market is the largest national market, supported by the headquarters of leading model developers and cloud providers, deep venture funding and early enterprise adoption. Banks, insurers, retailers and healthcare systems deploy virtual agents and document understanding at scale. Federal agencies are adding conversational tools for public services. Competition among platform vendors is pushing rapid releases. State and federal rules on AI transparency are shaping deployment choices.
⮞In February 2026, the Pew Research Center surveyed U.S. adults and found that 44% say they use ChatGPT, up from 18% in 2023. Public familiarity with conversational AI supports wider use of language understanding in consumer and workplace products.
Natural Language Understanding Market Segment Analysis
-
By Component, the Solutions segment dominated the Natural Language Understanding Market with approximately 78.65% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 30.68%.
-
By Deployment, the Cloud segment dominated the Natural Language Understanding Market with approximately 61.50% share in 2025 and is also the fastest growing with a CAGR of approximately 30.18%.
-
By Application, the Chatbots and Virtual Assistants segment dominated the Natural Language Understanding Market with approximately 31.50% share in 2025, while the Machine Translation segment is the fastest growing with a CAGR of approximately 32.50%.
-
By Vertical, the BFSI segment dominated the Natural Language Understanding Market with approximately 33.30% share in 2025, while the Healthcare and Life Sciences segment is the fastest growing with a CAGR of approximately 31.40%.
By Component, Solutions Dominates the Natural Language Understanding Market and Services Grows Fastest
Solutions lead because platforms, application programming interfaces and prebuilt models are the core product that buyers license. Vendors package intent detection, entity extraction, sentiment scoring and summarization for specific uses such as customer service and document review. Usage-based pricing lets teams start small and scale as volumes rise.
The services segment grows the fastest during the forecast period. This is due to enterprises need help in preparing data, designing quickly, integrating, evaluating and governing. Companies do not have any language specialists internally and hence have to depend on third party suppliers for designing the agents. Managed services for monitoring accuracy and safety are increasing.
⮞In 2026, the Japanese Ministry of Internal Affairs and Communications reported in its white paper that 86.4% of surveyed Japanese companies use generative AI for some work. Broad use is raising demand for tools and for support to run them.
By Deployment, Cloud Dominates the Natural Language Understanding Market and Is Also the Fastest Growing
Cloud leads because language models need large compute capacity and frequent updates that most organizations cannot run themselves. Hosted application programming interfaces give quick access to new models, and pay-as-you-go pricing suits uneven demand. Contact center and software vendors embed these services directly in their cloud products.
Cloud is also the fastest growing as new model features arrive first on hosted platforms. Regional data centers, private endpoints and confidential computing are reducing concerns in regulated industries. On-premises use persists where data cannot leave controlled sites, but it grows mainly through smaller open models that run on local hardware.
⮞In August 2025, the U.S. General Services Administration said FedRAMP would prioritize 20x authorization of cloud AI services that offer conversational AI engines for routine use by federal workers. Government priority is clearing a path for hosted language tools.
By Application, Chatbots and Virtual Assistants Dominates the Natural Language Understanding Market and Machine Translation Grows Fastest
Chatbots and virtual assistants lead because customer service, internal help desks and voice bots depend on understanding what users want. Companies deploy them to deflect routine contacts and shorten wait times. Large language models now handle open conversation, which widens the range of questions that can be answered without a human.
The development of machine translation technology comes fast because the multilingual model can be used for an increasing number of languages. Organizations apply machine translation for translating tickets, marketing content, business meetings, and documents for compliance. Real-time translation of speech is becoming common in call centers and tourism industry while governments invest in linguistic technologies for under-resourced languages.
⮞In January 2026, the UK Department for Science, Innovation and Technology reported that 85% of businesses already using AI use natural language processing and text generation, the most common AI type among adopters. Text understanding is the entry point for many firms.
By Vertical, BFSI Dominates the Natural Language Understanding Market and Healthcare and Life Sciences Grows Fastest
BFSI leads because banks and insurers handle huge volumes of customer messages, contracts, claims and regulatory text. Virtual assistants answer account questions, and language models extract terms from documents and flag risk in communications. Strict recordkeeping and large budgets support early investment in governed language platforms.
Growth of healthcare and life sciences happens most quickly as healthcare professionals and drug manufacturers implement language comprehension capabilities in the processing of their clinical notes, coding, patient communications, and scientific literature. The tools of ambient documentation convert the conversation into documentation, while payers rely on language comprehension to process claims and authorizations.
⮞In May 2026, the U.S. Census Bureau reported that 39.7% of firms in the information sector and 33.9% of those in finance and insurance currently use AI, against about 14% in retail. Information-heavy sectors lead adoption.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
88.00 |
|
Europe |
Germany |
22.50 |
|
Asia Pacific |
China |
33.60 |
|
Latin America |
Brazil |
46.80 |
|
Middle East & Africa |
Saudi Arabia |
28.90 |
North America Natural Language Understanding Market Insights
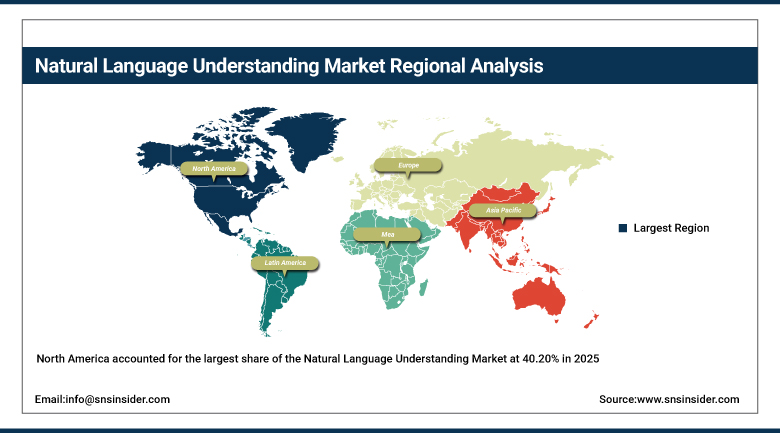
North America accounted for the largest share of the Natural Language Understanding Market at 40.20% in 2025, led by the United States and followed by Canada. The region is home to most leading model developers and cloud platforms, and enterprises there adopt conversational agents early. Banks, retailers and healthcare systems are the heaviest users.
Venture funding and large technology budgets support rapid product releases. Demand for document understanding and agent platforms is rising in government and professional services. Concerns over data privacy, model errors and emerging state rules slow some deployments and raise the cost of compliance.
⮞In September 2025, Statistics Canada reported that 12.2% of Canadian businesses used AI in the second quarter of 2025, up from 6.1% a year earlier, and that 34.8% of businesses planning to adopt AI intend to use virtual agents or chatbots. Planned use points to continued demand.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Natural Language Understanding Market Insights
Europe held significant share of the Natural Language Understanding Market in 2025, led by Germany, the United Kingdom, France, Italy and Spain. Multilingual needs across the region support translation and understanding tools, and local developers build models for European languages.
The AI Act and data protection law steer buyers toward transparent, auditable systems with regional hosting. Public sector programs and banking use cases drive demand. Shortages of AI skills and cautious procurement slow adoption among smaller firms.
⮞In December 2025, Eurostat reported that 19.95% of EU enterprises used at least one AI technology, up 6.47 percentage points, with text mining the most used type at 11.75%. Language analysis is already the leading entry point.
Asia Pacific Natural Language Understanding Market Insights
Asia Pacific is projected to be the fastest growing region in the Natural Language Understanding Market, at a CAGR of 30.70% over 2026-2035. China, Japan, India, South Korea and Australia lead. Large user bases and many languages create strong demand.
Chinese technology groups build large models for local languages, while Japanese and Korean firms deploy domain-tuned tools in manufacturing and finance. India is adding government-backed language infrastructure. Language diversity raises development costs, and data rules differ across countries.
⮞In September 2026, the China Internet Network Information Center reported more than 700 million generative AI users in China at the end of June 2026, up from 602 million at the end of 2025. Growth in users widens the base for language interfaces.
MEA & Latin America Natural Language Understanding Market Insights
Latin America and the Middle East and Africa together hold the modest share of the Natural Language Understanding Market. In Latin America, Brazil, Mexico, Argentina and Colombia lead, driven by banks, telecom operators and retailers adding Spanish and Portuguese virtual agents.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar, Egypt and South Africa lead. Gulf states fund Arabic language models and national AI programs, while limited data for African languages and uneven connectivity restrain adoption elsewhere.
⮞In 2025, the UN Economic Commission for Latin America and the Caribbean reported that the region accounts for 14% of global visits to AI solutions while holding 11% of global internet users. Regional use of AI tools outpaces its share of internet users.
Growth Drivers: Large Language Model Adoption and Enterprise Automation Drive Growth in the Natural Language Understanding Market
Large language model adoption is the main driver. These models understand intent and context far better than older rule-based systems, and they work across tasks and languages with little retraining. Vendors have packaged them as application programming interfaces, so product teams can add language understanding quickly, and costs per request have fallen.
Enterprise automation adds momentum. Companies use language understanding to route requests, answer customers, read contracts and summarize meetings. Agent platforms connect understanding to action in business systems, which turns language models into workers rather than tools. Labor costs and customer expectations push contact centers and service desks to automate more.
⮞In April 2026, the Stanford Institute for Human-Centered AI reported in its AI Index that 88% of organizations now use AI, up from 71% the year before. Wide adoption is carrying language understanding into daily operations.
Restraints: Skills Shortages and Regulatory Uncertainty Restrain Growth in the Natural Language Understanding Market
Shortage of skills hampers growth. Development of accurate language-based solutions requires experts in data, evaluation and security, and most firms are unable to recruit these people. Development usually gets stuck between the piloting stage and implementation due to difficulties in assessing the accuracy, expense and security of language models.
Uncertainty with respect to regulation adds constraints. Regulatory standards for AI transparency, data protection and liability vary from region to region, and the rules themselves keep changing. Business firms postpone the deployment of AI products in critical applications until regulations are set, and the work on compliance increases expenses.
⮞In December 2025, Eurostat reported that among EU enterprises that considered using AI, 70.89% cited lack of relevant expertise, 52.52% unclear legal consequences and 48.83% data protection concerns. Skills and legal clarity remain the main barriers.
Opportunities: Multilingual Models and Agentic Platforms Create Opportunities in the Natural Language Understanding Market
Multilingual models offer a major opportunity. Most of the world speaks languages that older tools served poorly, and governments are funding datasets and models for them. Vendors that support regional languages and dialects can enter call centers, public services and education in markets that were closed to English-only products.
Agentic platforms offer further potential. Language understanding that triggers actions, such as booking, refunds or record updates, moves buyers from experiments to measurable savings. Platform vendors can sell governance, monitoring and connectors, and industry-specific agents for banking, health and telecom open new contracts.
⮞In January 2025, India's Ministry of Electronics and Information Technology reported that its Bhashini language platform handled over 100 million inferences a month, offered more than 300 AI models and supported 17 of 22 scheduled languages. Public language infrastructure creates demand for local understanding tools.
Recent Developments:
-
In July 2025, NiCE agreed to acquire Cognigy, a conversational and agentic AI company, for USD 955 million, with closing expected in the fourth quarter of 2025. The deal adds a language understanding and agent platform to a large contact center software provider.
-
In May 2026, Kore.ai launched Artemis, a new agent platform for building, governing and optimizing enterprise AI agents, available first on Microsoft Azure. The platform is designed to coordinate several agents across business processes.
-
In November 2025, Amazon Web Services announced that Amazon Lex supports large language models as the primary option for natural language understanding in voice and chat bots. The change applies in all commercial regions where Amazon Connect and Lex operate.
Natural Language Understanding Market Key Players
-
Google LLC
-
Amazon Web Services, Inc.
-
International Business Machines Corporation
-
NICE Ltd. (Cognigy)
-
Kore.ai, Inc.
-
SoundHound AI, Inc.
-
Rasa Technologies GmbH
-
Yellow.ai
-
ServiceNow, Inc. (Moveworks)
-
Zendesk, Inc.
-
Oracle Corporation
-
Verint Systems Inc.
-
Expert.ai S.p.A.
-
LivePerson, Inc.
-
Salesforce, Inc.
Natural Language Understanding Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 28.08 Billion |
| Market Size by 2035 | USD 336.20 Billion |
| CAGR | CAGR of 28.18% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions and Services) • By Deployment (Cloud and On-Premises) • By Application (Chatbots and Virtual Assistants, Sentiment Analysis, Machine Translation, Text Analytics, and Others) • By Vertical (BFSI, Retail and E-commerce, Healthcare and Life Sciences, IT and Telecom, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Google LLC, Amazon Web Services, Inc., Microsoft Corporation, International Business Machines Corporation, NICE Ltd. (Cognigy), Kore.ai, Inc., SoundHound AI, Inc., Rasa Technologies GmbH, Cohere Inc., Yellow.ai, ServiceNow, Inc. (Moveworks), Zendesk, Inc., Oracle Corporation, Verint Systems Inc., Expert.ai S.p.A., LivePerson, Inc., Salesforce, Inc. |

Frequently Asked Questions
Key players include Google, Amazon Web Services, Microsoft, IBM, NICE (Cognigy), Kore.ai, SoundHound AI, Rasa, Cohere, Yellow.ai, ServiceNow (Moveworks), Zendesk, Oracle, Verint, Expert.ai, LivePerson and Salesforce.
Key opportunities include multilingual and regional language models, agentic platforms that act on user intent, domain-tuned models for healthcare and finance, and fast-growing Asia Pacific demand.
Adoption of large language models and enterprise automation of customer service and document work is the main growth factor.
By Component, the Solutions segment dominated the market in 2025 with an estimated 78.65% share, supported by licensed platforms and application programming interfaces.
North America dominated the market with a share of 40.20% in 2025, driven by the concentration of model developers, cloud platforms and early enterprise adopters.
