
NLP in Healthcare and Life Sciences Market Report Scope & Overview:
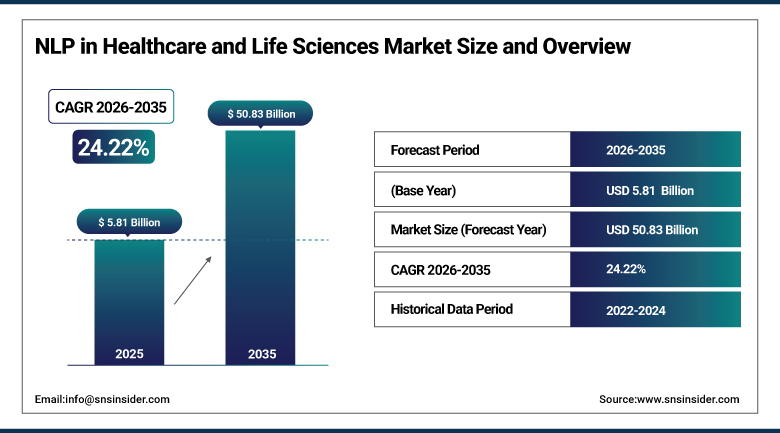
The NLP in Healthcare and Life Sciences Market was valued at USD 5.81 Billion in 2025 and is expected to reach USD 50.83 Billion by 2035, growing at a CAGR of 24.22% from 2026-2035.
The NLP in Healthcare and Life Sciences Market is expanding as hospitals and drug developers turn unstructured text and speech into usable data. Most clinical information sits in notes, letters and reports that older systems cannot read. Ambient scribes now draft visit notes from conversation, and coding tools suggest billing codes with supporting text. Large language models are improving summarization and question answering. Drug developers use language tools to mine literature, match trial patients and track safety signals. Clinician burnout and staff shortages push providers to adopt documentation tools quickly. Accuracy, privacy and integration with records remain hurdles. The market is expected to grow at a fast pace as adoption spreads.
⮞In March 2026, the American Medical Association reported that 81% of physicians use artificial intelligence professionally, more than double the 2023 rate. The survey shows that clinicians are ready to use language-based tools in daily practice.
To Get more information NLP in Healthcare and Life Sciences Market - Request Free Sample Report
NLP in Healthcare and Life Sciences Market Trends
-
Ambient clinical documentation that drafts visit notes from patient conversations
-
Large language models for summarization, coding support and clinical question answering
-
Agentic AI workflows for scheduling, coding and patient communication
-
Language tools for clinical trial matching, pharmacovigilance and literature mining
-
Governance, accuracy testing and privacy controls for clinical language models
U.S. NLP in Healthcare and Life Sciences Market Outlook
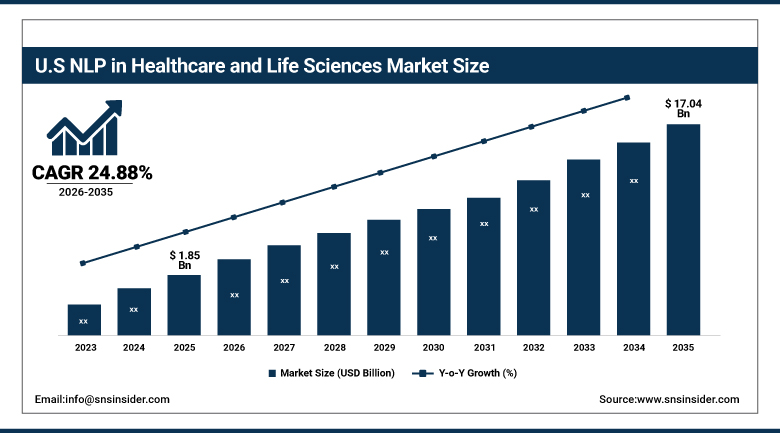
The U.S. NLP in Healthcare and Life Sciences Market was valued at USD 1.85 Billion in 2025 and is expected to reach USD 17.04 Billion by 2035, growing at a CAGR of 24.88% from 2026-2035.
The U.S. NLP in Healthcare and Life Sciences Market is the largest national market, supported by near-universal electronic record use and heavy documentation loads. Physicians spend hours on notes, and health systems are buying ambient scribes to relieve that burden. Revenue cycle teams use language tools to find missed codes and support claims. Pharmaceutical firms apply the same tools to trials and safety reports. The Food and Drug Administration is also using generative tools internally. Health systems are building governance rules for model accuracy and bias. Privacy duties under HIPAA and integration cost remain hurdles. Growth is expected to stay strong as adoption deepens.
⮞In September 2025, the Office of the National Coordinator for Health IT reported that 71% of non-federal acute care hospitals used predictive artificial intelligence integrated with their electronic health records in 2024, up from 66% in 2023. The rise shows growing comfort with embedding algorithms in clinical systems.
NLP in Healthcare and Life Sciences Market Segment Analysis
-
By Component, the Software segment dominated the NLP in Healthcare and Life Sciences Market with approximately 52.81% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 26.10%.
-
By Deployment, the Cloud-Based segment dominated the NLP in Healthcare and Life Sciences Market with approximately 60.47% share in 2025, while the Hybrid segment is the fastest growing with a CAGR of approximately 26.62%.
-
By Application, the Clinical Documentation segment dominated the NLP in Healthcare and Life Sciences Market with approximately 34.53% share in 2025, while the Patient Engagement and Conversational AI segment is the fastest growing with a CAGR of approximately 28.67%.
-
By End User, the Healthcare Providers segment dominated the NLP in Healthcare and Life Sciences Market with approximately 45.17% share in 2025, while the Pharmaceutical and Biotechnology Companies segment is the fastest growing with a CAGR of approximately 31.03%.
By Component, Software Dominates the NLP in Healthcare and Life Sciences Market and Services Grows Fastest
Software leads because buyers license platforms, engines and application programming interfaces that extract meaning from clinical text and speech. Products for documentation, coding, search and analytics are sold as subscriptions, which creates recurring revenue for vendors. Large technology firms embed language models in electronic record systems, and specialist vendors sell tuned medical models. Health systems prefer products that connect to existing records and workflows. Continuous model updates and new features keep customers on the same platform. These traits give software the largest share of spending across providers and life science firms.
Services are the fastest growing component because language tools rarely work well without customization. Providers need help with integration, model tuning, accuracy testing and clinician training. Life science firms need support to build pipelines that read trial documents, safety reports and publications. Managed services, annotation and governance support are growing as organizations worry about hallucination and bias. Consultancies and system integrators package these tasks with software, and vendors add implementation teams. As deployments move from pilots to enterprise rollouts, spending on services rises faster than license fees.
⮞In March 2026, Amazon Web Services announced general availability of Amazon Connect Health with five launch agents, including ambient documentation and patient verification. The launch shows cloud providers packaging language tools as managed healthcare services.
By Deployment, Cloud-Based Dominates the NLP in Healthcare and Life Sciences Market and Hybrid Grows Fastest
Cloud deployment is most popular due to the fact that language models require substantial computational capacity, which most hospitals do not have. Vendors update the models centrally, thus users get all the latest functionalities without software installation. Subscription fees minimize up-front costs and allow small clinics to benefit from ambient technology. Cloud vendors offer healthcare-compliant clouds with relevant security certificates, assuring compliance officers. One more benefit of cloud deployment is speed: in a few weeks after ordering the service, it is already up and running. This set of advantages makes cloud delivery default for the new deployment in care and research.
Hybrid deployments are the most rapidly growing category because organizations strive for cost-efficiency, privacy, and performance at the same time. Hospitals store their sensitive information locally, and only less sensitive functions are processed in the cloud. In countries that impose data residency laws, the buyers are forced to select cloud deployment in the country where they operate. Pharmacies employ private models for their proprietary texts and cloud models for generic functions. Edge computation enables speech recognition in the examination rooms almost without latency.
⮞In August 2026, Wolters Kluwer Health reported that about 2,500 U.S. hospitals and health systems have adopted UpToDate Expert AI, over 90% of its enterprise customers. The uptake shows how quickly clinical language tools reach large provider networks.
By Application, Clinical Documentation Dominates the NLP in Healthcare and Life Sciences Market and Patient Engagement and Conversational AI Grows Fastest
Clinical documentation leads because notes consume a large share of clinician time and the benefit is easy to measure. Ambient scribes listen to visits and draft notes for review, which shortens charting and lowers after-hours work. Hospitals report better clinician satisfaction and faster note completion. Documentation tools also feed coding, orders and billing, so they sit at the center of the record. Nursing documentation is the next target, since nurses spend a large part of each shift on administrative tasks. These factors keep documentation the largest use.
Patient engagement and conversational AI is growing fastest as providers deploy virtual assistants for scheduling, triage, reminders and follow-up. Patients expect messaging in plain language and in many languages, and language models make that affordable. Call centers use voice agents for verification and routine questions, which cuts wait times. Medical coding and billing, clinical trial matching and drug discovery are also expanding, supported by tools that read charts and publications. Pharmacovigilance teams use language processing to screen case reports for safety signals.
⮞In October 2025, Microsoft reported that more than 25% of a nurse's shift goes to documentation and administrative tasks while extending Dragon Copilot to nurses. The share shows the size of the time burden that language tools aim to reduce.
By End User, Healthcare Providers Dominates the NLP in Healthcare and Life Sciences Market and Pharmaceutical and Biotechnology Companies Grows Fastest
Healthcare providers lead because hospitals, clinics and physician groups hold the records and carry the documentation burden. Health systems buy language tools to reduce burnout, improve coding accuracy and capture revenue. Large integrated networks negotiate enterprise contracts, and small practices adopt through electronic record partners. Shortages of clinicians raise the value of any tool that frees time for patient care. Payers form a smaller group that uses language processing to review claims, appeals and prior authorization requests. Together these buyers account for the largest share of spending.
Pharmaceutical and biotechnology companies are growing fastest as they apply language models across the development chain. Teams use them to mine literature, extract data from trial documents, draft regulatory submissions and monitor safety reports. Matching patients to trials from clinical notes can shorten enrollment. Contract research organizations add similar tools to speed study start-up. Spending is rising as firms move from pilots to platforms with governance and audit trails, and investment in agentic assistants is widening the set of tasks they handle.
⮞In March 2026, IQVIA reported that 19 of the top 20 pharmaceutical companies have begun using its AI agents, with more than 150 agents deployed. The adoption shows how quickly life science firms are putting language-driven agents to work.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
77.80 |
|
Europe |
Germany |
22.17 |
|
Asia Pacific |
China |
33.04 |
|
Latin America |
Brazil |
51.36 |
|
Middle East & Africa |
Saudi Arabia |
28.43 |
North America NLP in Healthcare and Life Sciences Market Insights
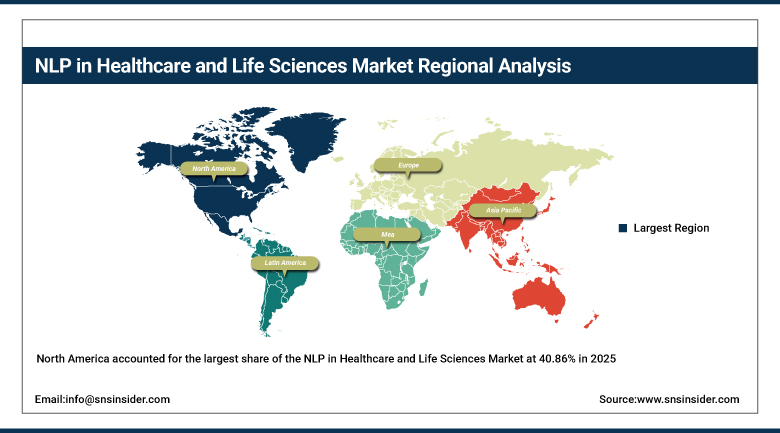
North America accounted for the largest share of the NLP in Healthcare and Life Sciences Market at 40.86% in 2025, led by the United States. Near-universal electronic record use, high clinician workloads and strong venture funding support adoption. Technology leaders such as Microsoft, Amazon, Oracle and Google compete with specialist vendors such as Suki, Abridge, Commure and John Snow Labs. Large health systems run enterprise ambient programs, and pharmaceutical headquarters in the region drive demand for life science language tools. Canada adds demand through provincial digital health programs. Mexico adds demand through private hospital groups.
Regulation and payment shape the market. Documentation tools that do not make diagnoses generally face lighter oversight, while tools that influence care are drawing closer attention from the Food and Drug Administration. HIPAA sets strict duties on data handling, and breaches carry heavy cost. Health systems are forming governance committees to test accuracy and bias before rollout. Payers and providers are also using language models for coding and prior authorization, which raises questions about audit and appeal. Competition among vendors is pushing prices down for basic scribe features.
⮞In January 2026, Suki reported that clinicians on athenaOne produce about 500,000 clinical notes a month with its tools, with usage up 50% in six months. The company-reported volume shows how fast ambient documentation is scaling in ambulatory care.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe NLP in Healthcare and Life Sciences Market Insights
Europe is the second largest region and is led by Germany, the United Kingdom, France, Italy and Spain. National health systems are digitizing records, and clinical language tools are being tested in hospitals and general practice. European vendors such as Corti, Averbis, Nabla and expert.ai supply multilingual products, and the need to handle many languages favors specialist models. Smaller national vendors serve local language needs that global firms address slowly. The pharmaceutical sector in Switzerland, Germany and the United Kingdom adds demand for literature mining and regulatory document tools.
Data protection rules shape deployment. The General Data Protection Regulation and national health data laws limit how patient text may be processed, so many buyers prefer in-country hosting. The Medical Device Regulation and the European Union Artificial Intelligence Act add duties for tools that support clinical decisions. In the United Kingdom, health service guidance and regulatory letters are setting expectations for ambient voice products. Procurement frameworks are helping trusts buy validated tools, and integration with national record platforms is a key task. Cross-border research collaborations also encourage shared standards for clinical text.
⮞In April 2026, Germany's gematik and the Federal Ministry of Health reported that more than 100 million documents were uploaded to the electronic patient record in its first year after nationwide launch. The volume expands the pool of digital text that language tools can structure.
Asia Pacific NLP in Healthcare and Life Sciences Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 27.47% during 2026-2035. China, Japan, India, Australia and South Korea lead regional demand. Governments are building digital health infrastructure, and large patient volumes create heavy documentation loads. Australian health services are rolling out AI scribes at scale, and Indian speech technology firms offer products tuned to local accents. Japanese and Korean hospitals are testing language models for records written in complex scripts. Singapore and South Korea also run national pilots that link hospitals to shared data platforms.
Language diversity is both a challenge and an opportunity. Models must handle many languages and dialects, which favors local developers with regional data. India is linking health records to digital identities, which produces structured data for analytics, and China is promoting hospital artificial intelligence under national programs. Data localization rules vary, and regulators in Australia and Singapore have issued guidance on scribe tools. Cost sensitivity in public hospitals favors cloud subscriptions and open-source models. Telehealth growth adds spoken consultations that scribes can capture.
⮞In May 2026, India's Ayushman Bharat Digital Mission reported that over 100 crore health records are linked to ABHA identifiers, double the level of February 2025. The scale creates a foundation for language-based analytics across the health system.
MEA & Latin America NLP in Healthcare and Life Sciences Market Insights
In Latin America, Brazil is the largest market, followed by Mexico, Argentina and Colombia. Private hospital groups are adopting ambient documentation and virtual assistants, and public systems are digitizing records. Portuguese and Spanish language models are improving, which reduces the need to depend on English-only products. Surveys by regional health bodies show that most health professionals have already tried an artificial intelligence tool, though few have formal training. Budget limits and uneven connectivity slow public sector adoption. International vendors are partnering with local integrators to speed rollouts.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Israel and South Africa lead demand. Gulf governments are funding national digital health strategies, and hospitals are buying scribes that can handle Arabic dialects as well as English. Training programs are building local skills. In much of Africa, limited records and connectivity restrain use, though mobile-based tools and donor-funded programs are opening early projects. Regional vendors and global firms are forming alliances to localize products. Language coverage for Arabic, Swahili and Afrikaans is improving.
⮞In January 2025, the Department of Health Abu Dhabi reported that its Global AI Healthcare Academy, run with MBZUAI, had trained more than 3,750 healthcare professionals. The program shows investment in the workforce skills needed to use clinical language tools.
Market Dynamics
Growth Drivers: Clinician Burnout and Unstructured Data Volume Drive Growth in the NLP in Healthcare and Life Sciences Market
Clinician burnout and documentation burden are the strongest drivers. Physicians and nurses spend long hours on notes, and shortages of staff make that time hard to recover. Ambient tools that draft notes from conversation offer a measurable benefit, which supports quick purchasing decisions. Health systems also gain from more complete documentation, which supports coding and revenue. Early users report shorter charting time and better job satisfaction, and those results encourage peers to follow. Vendors are also adding coding prompts that lift revenue capture.
The volume of unstructured data adds demand. Most clinical information sits in free text, and electronic records are now widespread, so the supply of text keeps growing. Large language models improve the ability to summarize charts, answer questions and draft messages. Drug developers use the same advances to read trial documents and publications, and regulators are testing generative tools in their own work. Cloud platforms and application programming interfaces make adoption easier for smaller organizations with limited technical staff. Falling inference costs make features such as summarization affordable at scale.
⮞In December 2025, the U.S. Food and Drug Administration reported that more than 70% of its staff had voluntarily used its Elsa generative artificial intelligence tool. The uptake inside a regulator signals growing acceptance of language models in health and life science work.
Restraints: Data Privacy Risk and Accuracy Concerns Restrain Growth in the NLP in Healthcare and Life Sciences Market
Clinical text comprises identifiers and confidential information, so any leak will incur legal and reputational damages. Management of consent, data residency and access by third parties differs depending on the country. Security departments take time to assess model hosting and data retention. Small vendors are unable to conduct such assessment because of the limited number of personnel, thus they postpone projects. Healthcare facilities frequently experience breaches that keep their boards wary. Vendors counteract these measures by implementing encryption, redaction and auditing, yet all additions increase costs.
Questions about accuracy and integration pose additional constraints. Language models can make up facts or skip some information, hence clinicians need to check every generated text. Responsibility in case of errors is uncertain. Connecting tools to the old record system and claims platform entails additional expenses and delays. Domain-specific training data is unavailable in some languages and specialties. The high costs of computing for big models and clinician resistance against automated clinical notes may impede adoption too. Smaller organizations usually lack time to test the tools.
⮞In December 2025, HIPAA Journal reported, from data published by the U.S. Department of Health and Human Services Office for Civil Rights, 697 breaches of 500 or more records in 2025 affecting 60,976,942 individuals. The count illustrates the privacy exposure facing organizations that process clinical text.
Opportunities: Life Science Applications and Public Sector Scribe Programs Create Opportunities in the NLP in Healthcare and Life Sciences Market
Life science applications offer high-value opportunities. Language tools can read thousands of papers, extract targets and relationships, and support regulatory writing. Clinical trial matching from records can speed enrollment, a major cost in drug development. Pharmacovigilance teams can screen case narratives automatically. Rare disease and behavioral health are less served areas where tailored models can win share. Partnerships with contract research organizations and academic centers can speed validation. Pharmaceutical firms are willing to pay for tools that cut development time, and vendors that offer validated workflows can charge premium prices.
Public sector programs and new markets add further potential. Governments are funding AI scribes for large clinician groups, which creates scale contracts. Multilingual models open markets where English-only products fail. Payers can use language tools to speed prior authorization and appeals. Sovereign cloud offerings address data residency concerns, and agentic assistants that act on documentation, such as ordering follow-up or drafting referrals, widen the revenue pool. Hospitals in emerging markets can leapfrog legacy systems by adopting cloud-first language tools. Partnerships with record vendors can lower integration cost. Reimbursement for digital documentation tools remains limited.
⮞In July 2026, New South Wales Health committed AUD 38.7 million in its 2026-27 budget for AI scribes for up to 6,000 clinicians. The funding shows public health systems turning scribe pilots into large programs.
Recent Developments:
-
In December 2025, Clarivate launched the Cortellis Regulatory Intelligence AI Assistant for all customers of its regulatory intelligence product after a beta. The agentic tool gives cited answers, multilingual support and document summaries, and it compares draft and final guidance side by side.
-
In March 2026, Oracle made its Clinical AI Agent note generation available in U.S. inpatient and emergency departments. The tool drafts admit and progress notes for clinician review and is designed to reduce documentation time in acute care.
-
In May 2026, Commure announced that Willis Knighton Health selected it as the enterprise ambient AI partner across four hospitals on the MEDITECH Expanse record. The choice followed a seven-specialty pilot and shows rising demand for enterprise-scale scribes.
-
In May 2026, Corti launched Symphony for Speech-to-Text, a speech recognition model built for clinical conversations. The release extends the company's clinical language API and targets ambient voice use in hospitals and general practice.
NLP in Healthcare and Life Sciences Market Key Players
-
Microsoft Corporation (Nuance)
-
Amazon Web Services, Inc.
-
IQVIA Holdings Inc.
-
Oracle Corporation (Oracle Health)
-
John Snow Labs Inc.
-
Suki AI, Inc.
-
Abridge AI, Inc.
-
Commure, Inc.
-
Nabla
-
Clarivate Plc
-
Corti ApS
-
Averbis GmbH
-
Wolters Kluwer Health
-
Tempus AI, Inc.
-
Ambience Healthcare, Inc.
-
expert.ai
-
Heidi Health
-
Veradigm Inc.
NLP in Healthcare and Life Sciences Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.81 Billion |
| Market Size by 2035 | USD 50.83 Billion |
| CAGR | CAGR of 24.22% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Software and Services) • By Deployment (Cloud-Based, Hybrid, and On-Premises) • By Application (Clinical Documentation, Patient Engagement and Conversational AI, Medical Coding and Billing, Clinical Trial Matching, Drug Discovery, Pharmacovigilance, and Others) • By End User (Healthcare Providers, Payers, Pharmaceutical and Biotechnology Companies, Contract Research Organizations, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Microsoft Corporation (Nuance), Amazon Web Services, Inc., IQVIA Holdings Inc., Oracle Corporation (Oracle Health), John Snow Labs Inc., Suki AI, Inc., Abridge AI, Inc., Commure, Inc., Nabla, Clarivate Plc, Corti ApS, Averbis GmbH, Wolters Kluwer Health, Tempus AI, Inc., Ambience Healthcare, Inc., expert.ai, Heidi Health, Veradigm Inc. |

Frequently Asked Questions
Key players include Microsoft, Amazon Web Services, IQVIA, Oracle Health, John Snow Labs, Suki, Abridge, Commure, Nabla, Clarivate, Corti, Averbis, Wolters Kluwer Health, Tempus AI, Ambience Healthcare, expert.ai, Heidi Health and Veradigm.
Key opportunities include life science applications such as trial matching and pharmacovigilance, public sector scribe programs, multilingual models and agentic assistants
Clinician burnout and documentation burden, together with the rapid growth of unstructured clinical data and large language models, are the main growth factors.
By Component, the Software segment dominated the market in 2025 with an estimated 52.81% share, supported by subscription platforms for documentation, coding and analytics.
North America dominated the market with a share of 40.86% in 2025, driven by near-universal electronic record use, high clinician workloads and strong venture funding.
