
Oil Storage Market Report Scope & Overview:
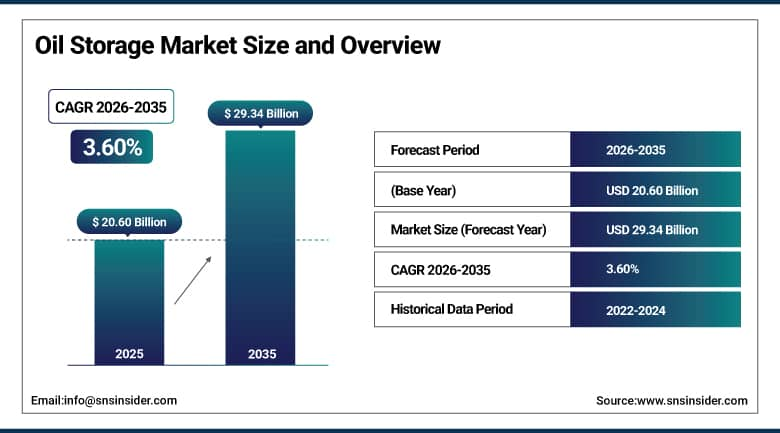
The global Oil Storage Market was valued at USD 20.60 Billion in 2025 and is expected to reach USD 29.34 Billion by 2035, growing at a CAGR of 3.60% from 2026 to 2035.
Oil storage infrastructure infrastructure holds a crucial position in maintaining energy security, helping in the safe storage, transportation, and distribution of crude oil, petrochemicals, and strategic petroleum reserves. Market growth is still being influenced by the expansion of strategic petroleum reserves owing to the growing geopolitical uncertainties, the growing industrialization of emerging economies, and the increasing investments in digital technologies for increasing the efficiency of operations at the terminals.
Vopak implemented Honeywell Forge analytics at its terminals in Singapore and Rotterdam in 2025, decreasing the amount of unplanned downtime by 18% and increasing the annual tariff income by USD 12 million, indicating that the leading tank terminals have been increasingly investing in digital technology to increase their efficiency.
Market Size and Forecast
-
Market Size in 2026E: USD 21.34 Billion
-
Market Size by 2035: USD 29.34 Billion
-
CAGR: 3.60% from 2026 to 2035
-
Fastest Growing Region: Asia Pacific
-
Largest Region: North America
To Get More Information On Oil Storage Market - Request Free Sample Report
Oil Storage Market Trends
-
Growing expansion of strategic petroleum reserve initiatives is driving government-backed inventory build-up amid persistent geopolitical instability.
-
Rising deployment of digital-twin platforms and predictive-maintenance software is reducing truck-loading queues and minimizing costly demurrage charges.
-
Expanding integration of embedded storage capacity into new refinery designs is streamlining crude and product logistics at major processing complexes.
-
Increasing retrofit of vapor recovery systems and secondary containment is addressing tightening methane emission and environmental compliance standards.
-
Growing performance gap between Tier-1 operators with large technology budgets and smaller independents is reshaping competitive dynamics industry-wide.
U.S. Oil Storage Market Outlook
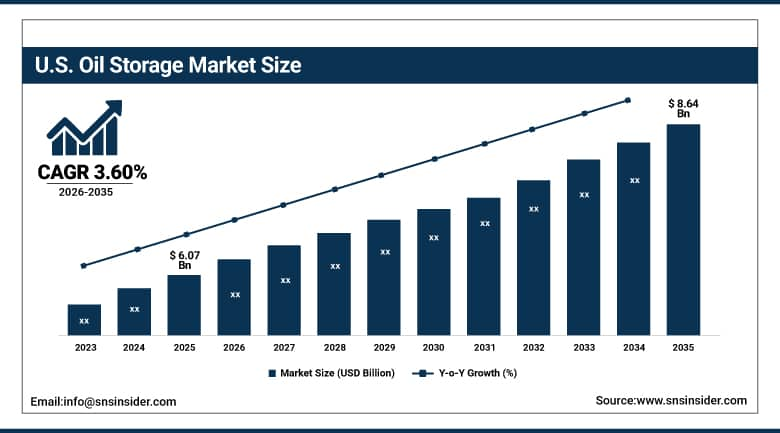
The U.S. Oil Storage Market was valued at USD 6.07 Billion in 2025 and is projected to reach USD 8.64 Billion by 2035, growing at a CAGR of 3.60% during 2026-2035.
Continued Strategic Petroleum Reserve replenishment by the government, along with well-equipped Gulf Coast storage facilities, will go on to sustain market expansion throughout the nation. Terminal companies are increasing their use of digital technology to meet their efficiency and safety needs. Increasing investments in storage facilities geared towards exports, driven by the nation’s status as one of the largest exporters of crude oil and refined products globally, will go on to drive continued infrastructure investment nationwide.
In 2024, the U.S. Department of Energy signed contracts for 3.5 million barrels of crude oil to be delivered to the Bayou Choctaw Strategic Petroleum Reserve storage facility, sustaining the continued momentum behind government-supported inventory accumulation as the nation tries to replenish its stockpiles lost in the past due to supply disruptions.
Oil Storage Market Segment Analysis
-
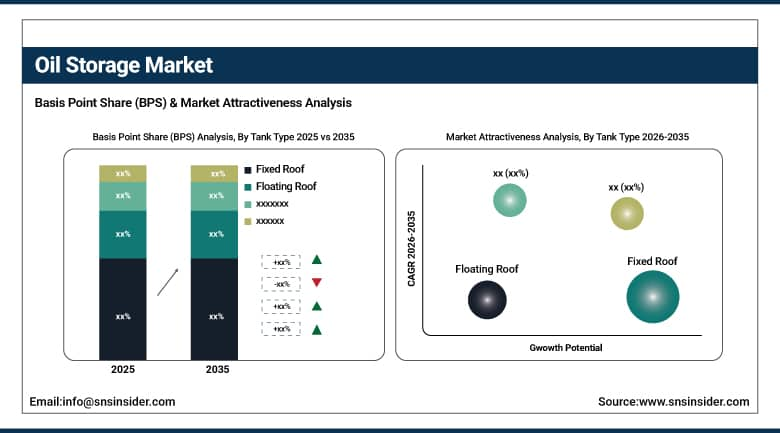
By Tank Type, Fixed Roof led the Oil Storage Market with a 47.70% share in 2025, while Floating Roof is the fastest-growing tank type segment with a CAGR of 5.50% from 2026-2035.
-
By Storage Type, Crude Oil led the Oil Storage Market with a 58.60% share in 2025, while Refined Petroleum Products is the fastest-growing storage type segment with a CAGR of 6.20% from 2026-2035.
-
By Ownership, Commercial led the Oil Storage Market with a 68.60% share in 2025, while Strategic/Government is the fastest-growing ownership segment with a CAGR of 6.80% from 2026-2035.
By Tank Type, Fixed Roof Dominated the Market While Floating Roof Is the Fastest-Growing Segment
The Fixed Roof tank held the largest revenue share of 47.70% in the Oil Storage Market in 2025 due to the simple structure, low costs, and viability of these tanks for onshore bulk oil storage purposes across refining plants, strategic petroleum reserve facilities, oil terminals, and distribution facilities. The easy installation process and low capital costs compared to more complex tanks still drive the adoption of fixed roof tanks, especially in emerging nations where there is growth in storage capacity.
The Floating Roof tank segment will grow at the highest CAGR of 5.50% from 2026 to 2035 owing to the increasing need for the reduction in vapor loss and evaporation associated with volatile crude oil and petroleum products storage. Stringent environmental regulation related to the emission of methane and volatile organic compounds is driving the use of floating roof tanks especially at terminals that upgrade their fixed roof infrastructure.
By Storage Type, Crude Oil Dominated the Market While Refined Petroleum Products Is the Fastest-Growing Segment
The Crude Oil segment led the Oil Storage Market with a revenue share of 58.60% in 2025, reflecting refineries', national oil companies', and commercial traders' reliance on large-scale storage facilities to manage supply fluctuations, price volatility, and logistical constraints. Crude oil storage represents the foundational infrastructure layer within the global oil supply chain, reinforcing this storage type's dominant position across the broader oil storage market worldwide.
The Refined Petroleum Products segment is expected to register the fastest CAGR of 6.20% during the forecast period 2026-2035, driven by growing downstream refining capacity investment and expanding distribution network requirements across emerging markets. Rising aviation fuel, diesel, and gasoline consumption across rapidly industrializing economies continues to reinforce this segment's above-average growth trajectory relative to upstream crude oil storage.
By Ownership, Commercial Dominated the Market While Strategic/Government Is the Fastest-Growing Segment
The Commercial Segment dominated the Oil Storage Market with 68.60% revenue share in 2025 due to the large amount of capacity owned by the private terminal operators, refineries, and traders in order to meet the requirements of commercial oil business operations. The commercial storage segment has continued its dominance since it constitutes the largest ownership type due to the huge quantity of crude oil and refined products handled on a daily basis.
The Strategic/Government segment would witness the fastest CAGR of 6.80% during the forecast period from 2026-2035 owing to the efforts made by countries to increase energy security due to political instability through maintaining their strategic petroleum reserves. Strategic petroleum reserve build-up activities carried out by the government, including the program for buying to refill the inventory which was depleted in the past, continue to contribute to the above average growth in the segment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.60% |
|
Europe |
Netherlands |
26.40% |
|
Asia Pacific |
China |
38.60% |
|
Middle East & Africa |
Saudi Arabia |
32.60% |
|
Latin America |
Brazil |
24.60% |
North America Oil Storage Market Insights
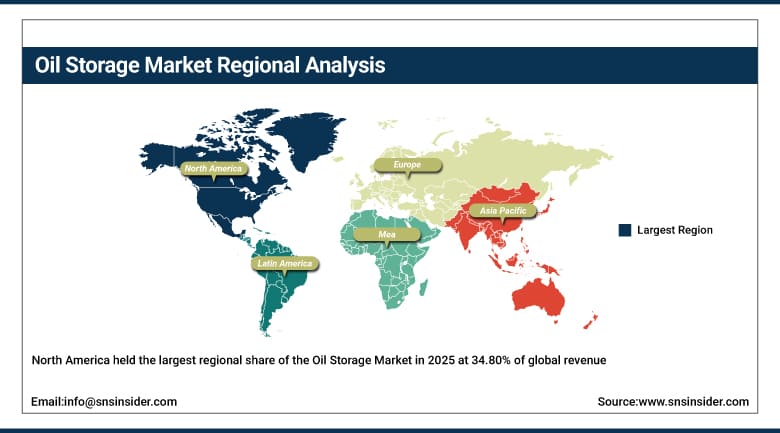
North America held the largest regional share of the Oil Storage Market in 2025 at 34.80% of global revenue, supported by the nation's position as the world's third-largest oil importer alongside substantial Strategic Petroleum Reserve infrastructure and Gulf Coast commercial storage capacity. Continued government-backed inventory build-up and export-oriented terminal investment continue to reinforce the region's leadership position across the broader oil storage landscape.
The United States accounted for approximately 84.60% of the North American market in 2025, reflecting its extensive Strategic Petroleum Reserve network and substantial Gulf Coast commercial terminal infrastructure. Canada is contributing to regional growth through steady crude oil storage investment and growing export-oriented terminal capacity across its major oil-producing provinces.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Oil Storage Market Insights
In 2025, the European region was an important part of the Global Oil Storage Market, owing to the presence of Rotterdam, which is one of the biggest oil trading and storage centers in the world. Moreover, the use of advanced digital technology by the prominent operators of terminal has resulted in consistent demand for modern storage facilities.
The Netherlands occupied 26.40% of the European market share in 2025 due to its prominence as the largest oil trading and storage center in Europe along with having headquarters for prominent independent tank terminal operators. In addition to this, Germany, UK, and Belgium have also contributed significantly to the growth of the region owing to the presence of modern terminals in them.
Asia Pacific Oil Storage Market Insights
Asia Pacific is projected to register the fastest CAGR during the forecast period 2026-2035, driven by rapid urbanization and industrialization continuing to expand oil consumption and storage infrastructure requirements across China and India. Growing strategic petroleum reserve expansion and private refinery buildouts, particularly in India, continue to accelerate regional storage construction activity.
China accounted for approximately 38.60% of the Asia Pacific market in 2025, supported by its massive industrial base and rapidly expanding domestic refining and storage infrastructure. India and Japan are also contributing meaningfully to regional growth, with India's strategic petroleum reserve expansion and private refinery buildouts accelerating storage construction to meet growing import dependency.
Middle East & Africa and Latin America Oil Storage Market Insights
The Middle East and Africa regions are still retaining their significant shares in terms of global storage volume due to the considerable presence of large national oil companies with extensive crude oil production and export facilities in the Gulf states. The Latin American region is also experiencing the effect of growing investment in refining and storage capacity, due to the considerable offshore production of Brazil.
In 2025, Saudi Arabia was the leader of the Middle East and Africa market in terms of 32.60% regional share due to its status as one of the leading countries in terms of crude oil production and exports and, therefore, in need of extensive storage infrastructure. In 2025, Brazil had a share of 24.60% in the Latin American market due to its considerable offshore oil production.
Market Dynamics
Growth Drivers: Energy Security Initiatives and Industrialization Driving Market Growth
The Oil Storage Market is being driven primarily by expansion of Strategic Petroleum Reserve initiatives as nations aggressively bolster energy security in response to geopolitical instability, rapid industrialization and urbanization across emerging economies driving higher consumption of crude oil and refined petroleum products, and growing embedded storage capacity integration into new refinery designs. Refineries, national oil companies, and commercial traders continue to rely on large-scale storage facilities to manage supply fluctuations, price volatility, and logistical constraints inherent to global oil trade.
Growing government-led accumulation programs continue to utilize available terminal capacity even during periods of lower commercial demand, ensuring facilities remain operational and generating sustained infrastructure investment. Rising deployment of digital-twin platforms and predictive-maintenance software is reducing operational inefficiencies and demurrage costs. Expanding retrofit of vapor recovery systems and secondary containment is further reinforcing sustained capital investment as operators navigate tightening environmental compliance standards.
Restraints: High Capital Expenditure and Environmental Regulation Limiting Market Expansion
Even with the presence of a favorable demand environment, there exist several challenges within the market, including high investments that would be incurred during the erection of facilities, making it challenging for small players in terms of the size of the investment that would be required. Environmental regulations related to emissions and safety become increasingly expensive for terminal operators, especially when dealing with the legacy fixed roof facilities which require retrofitting investment.
The growing gap in performance between the Tier-1 companies with budgets for technology investments and the independents without budgets for digital investments continues to define competitive dynamics in the market. There are continuing labor challenges in terms of welders and corrosion engineers, making it challenging to define construction schedules in the oil storage terminal market.
Opportunities: Digital Technology Integration and Emerging Market Infrastructure Creating New Growth Avenues
Substantial opportunity exists in continued deployment of digital monitoring and predictive-maintenance platforms capable of delivering measurable downtime reduction and tariff revenue improvement. Terminal operators that successfully scale advanced analytics systems stand to capture significant competitive advantage, though currently only operators with access to substantial technology budgets are positioned to fully capitalize on this opportunity.
Growing strategic petroleum reserve expansion and private refinery buildouts across emerging markets, particularly India, represent a further significant growth avenue, as nations prioritize energy security amid ongoing geopolitical uncertainty. Continued embedded storage capacity integration into new refinery complex designs also represents meaningful opportunity for terminal operators and engineering firms serving the expanding global refining infrastructure base.
Recent Developments:
-
2025: Vopak deployed Honeywell Forge analytics across its Singapore and Rotterdam terminals, trimming unplanned downtime by 18% and boosting annual tariff revenue by USD 12 million.
-
2026: Kinder Morgan piloted a digital-twin platform at the Houston Ship Channel, lowering truck-loading queues by 22 minutes per transaction.
-
2024: The U.S. Department of Energy finalized contracts for 3.5 million barrels of crude oil for delivery to the Bayou Choctaw Strategic Petroleum Reserve storage site.
-
2026: VTTI confirmed a final investment decision for rail infrastructure at its Amsterdam terminal and launched an open season for its Zeeland Energy Terminal.
Oil Storage Market key players are:
-
Royal Vopak N.V.
-
Kinder Morgan, Inc.
-
Oiltanking GmbH (Marquard & Bahls AG)
-
NuStar Energy L.P.
-
Buckeye Partners, L.P.
-
ONEOK, Inc.
-
Vitol Group
-
VTTI B.V.
-
Trafigura Group Pte. Ltd.
-
PetroChina Company Limited
-
Saudi Aramco
-
Sinopec (China Petroleum & Chemical Corporation)
-
Shell plc
-
ExxonMobil Corporation
-
Chevron Corporation
-
Enterprise Products Partners L.P.
-
Enbridge Inc.
-
Belco Manufacturing Co., Inc.
-
Zenith Energy Ltd.
-
HES International B.V.
Oil Storage Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 20.60 Billion |
| Market Size by 2035 | USD 29.34 Billion |
| CAGR | CAGR of 3.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Tank Type (Fixed Roof, Floating Roof, Bullet Tank, Spherical Tank) • By Storage Type (Crude Oil, Refined Petroleum Products, Strategic Petroleum Reserve) • By Ownership (Commercial, Strategic/Government) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Royal Vopak N.V., Kinder Morgan, Inc., Oiltanking GmbH (Marquard & Bahls AG), NuStar Energy L.P., Buckeye Partners, L.P., ONEOK, Inc., Vitol Group, VTTI B.V., Trafigura Group Pte. Ltd., PetroChina Company Limited, Saudi Aramco, Sinopec (China Petroleum & Chemical Corporation), Shell plc, ExxonMobil Corporation, Chevron Corporation, Enterprise Products Partners L.P., Enbridge Inc., Belco Manufacturing Co., Inc., Zenith Energy Ltd., HES International B.V. |
Frequently Asked Questions
The Oil Storage Market is expected to grow at a CAGR of 3.60% from 2026 to 2035.
The Oil Storage Market was valued at USD 20.60 Billion in 2025.
The market is driven by expansion of Strategic Petroleum Reserve initiatives, rapid industrialization and urbanization across emerging economies, and embedded storage capacity integration into new refinery designs.
The Fixed Roof segment dominated the Oil Storage Market in 2025, accounting for approximately 47.70% market share.
The North America region dominated the Oil Storage Market in 2025, accounting for approximately 34.80% market share.
