
Open Banking Market Report Scope & Overview:
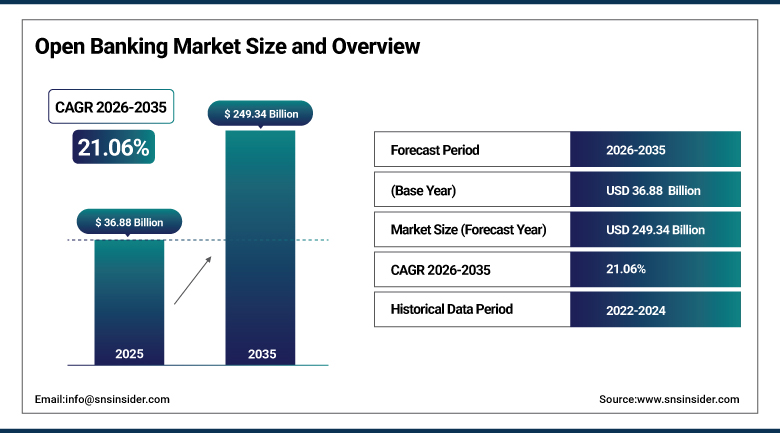
The Open Banking Market was valued at USD 36.88 Billion in 2025 and is expected to reach USD 249.34 Billion by 2035, growing at a CAGR of 21.06% from 2026-2035.
The Open Banking Market is expanding as regulators and industry bodies require banks to share customer-permissioned data through secure application programming interfaces, which allows licensed third parties to build account aggregation, payment initiation and lending services. Adoption began in Europe under payment services rules and has spread to India, Brazil, Australia, the Gulf and the United States through a mix of mandates and market-led standards. Providers are moving from data access toward account-to-account payments, variable recurring payments and embedded finance, which carry clearer revenue models. Security, consent management and fair data-access pricing remain the central policy questions. Europe holds the largest share today, while Asia Pacific is expected to grow fastest as digital public infrastructure matures.
⮞In September 2025, Open Banking Limited reported that the United Kingdom had 15 million active open banking users in July 2025, almost one in three UK adults. The user base demonstrates how quickly permissioned data sharing can reach mass adoption once payment use cases are established.
To Get more information Open Banking Market - Request Free Sample Report
Open Banking Market Trends
-
Pay-by-bank account-to-account payments are gaining acceptance among large online merchants.
-
Variable recurring payment schemes are extending open banking into subscriptions and utility billing.
-
Regulators are shifting from access mandates toward consent dashboards, liability rules and fee frameworks.
-
Open banking is evolving into open finance covering savings, pensions, insurance and investments.
-
Aggregators are consolidating through acquisitions by card networks and private equity owners.
U.S. Open Banking Market Outlook
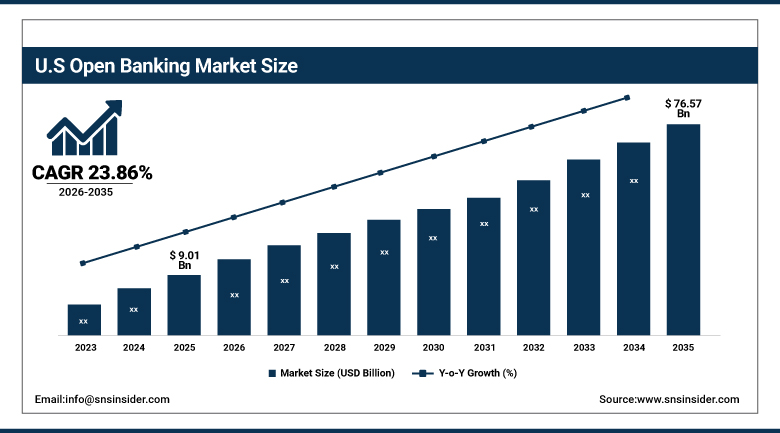
The U.S. Open Banking Market was valued at USD 9.01 Billion in 2025 and is expected to reach USD 76.57 Billion by 2035, growing at a CAGR of 23.86% from 2026-2035.
The U.S. Open Banking Market is developing through a market-led model in which data aggregators, large banks and industry standards bodies negotiate access, while federal rulemaking defines the legal framework. Aggregators connect tens of millions of consumers to budgeting, lending, payments and wealth applications, and fintech companies depend on them for account verification and cash-flow underwriting. Banks are seeking cost recovery for data access and stronger fraud controls, which has produced commercial agreements and public disputes. The sector is also adopting a common data standard that reduces the number of bilateral integrations. Growth is supported by demand for instant payments, lower-cost payment acceptance and credit decisions based on real-time account data.
⮞In August 2025, the Consumer Financial Protection Bureau published an advance notice of proposed rulemaking on its Personal Financial Data Rights rule, seeking comment on who may act as a consumer representative, whether data providers may charge fees, and information security and privacy. The notice reopened core questions about access terms for the U.S. market.
Open Banking Market Segment Analysis
-
By Service Type, the Banking and Capital Markets segment dominated the Open Banking Market with approximately 39.97% share in 2025, while the Payments segment is the fastest growing with a CAGR of approximately 22.84%.
-
By Deployment Model, the Cloud-Based segment dominated the Open Banking Market with approximately 68.94% share in 2025, and is also the fastest growing with a CAGR of approximately 22.41%.
-
By Distribution Channel, the App Markets segment dominated the Open Banking Market with approximately 38.27% share in 2025, and is also the fastest growing with a CAGR of approximately 22.71%.
-
By End User, the Banks and Traditional Financial Institutions segment dominated the Open Banking Market with approximately 39.05% share in 2025, while the Fintech and Third-Party Providers segment is the fastest growing with a CAGR of approximately 24.56%.
By Service Type, Banking and Capital Markets Dominates the Open Banking Market and Payments Grows Fastest
Banking and capital markets services lead because financial institutions were the first adopters of shared data interfaces and apply them to account aggregation, onboarding, credit assessment and wealth management. Institutions use permissioned transaction data to verify income, personalize product offers and reduce manual document checks, which shortens lending decisions and lowers acquisition cost. Regulatory mandates covering current accounts ensure that a broad data set is available, and established vendors integrate these interfaces into core banking platforms. Large banks also publish their own developer portals, which creates a steady base of integration and consulting work around internal and partner use cases.
Payments services are advancing fastest as merchants and consumers adopt pay-by-bank flows that settle directly between accounts. Account-to-account transfers avoid card scheme fees, reduce chargeback exposure and can confirm funds instantly, which attracts online retailers, travel companies and public bodies. Variable recurring payment frameworks extend the model to subscriptions and utility billing. Partnerships between payment platforms and open banking providers are widening coverage across European countries, while new instant payment rails in other regions support similar propositions. Digital currencies and value-added services such as financial wellness tools form smaller but growing additions.
⮞In July 2025, Stripe extended Pay by Bank to France and Germany, adding Ryanair as an adopting merchant. The expansion shows large online merchants testing account-to-account payments in new markets.
By Deployment Model, Cloud-Based Dominates the Open Banking Market and Also Grows Fastest
Cloud-based deployment leads because open banking traffic is variable, requires high availability and benefits from the elastic scaling that public cloud infrastructure provides. Providers run consent management, token services, data enrichment and developer sandboxes as hosted services, which allows banks to meet regulatory performance expectations without building new data centers. Security certifications held by major cloud vendors assist compliance reviews, and managed identity services simplify strong customer authentication. Fintech firms, which form most of the third-party base, are cloud native and prefer to consume interfaces as services. Vendors also deliver updates centrally as standards change.
The model continues to gain share as data volumes grow. Big ecosystems now deal with billions of data requests, and all of them require architectures with fast scaling during peak shopping periods. There is still use for hybrid setups in big banks with sensitive systems being located at the corporate office while exposed via cloud gateways. The regulatory bodies in several states have specified their stance towards outsourcing and resilience, thus lowering the level of ambiguity of the hosted services. In addition, open source gateways and API specifications make the creation of cloud-based environments cheaper.
⮞In September 2026, Sahamati reported that India's Account Aggregator network had enabled more than 2.8 billion financial accounts for data sharing and had processed more than 6 billion data fetches. The volumes illustrate the scale at which hosted consent infrastructure now operates.
By Distribution Channel, App Markets Dominates the Open Banking Market and Also Grows Fastest
App markets and developer platforms account for the largest share because they give third-party providers a single point of access to many institutions. Instead of negotiating connections bank by bank, developers use marketplace portals, sandboxes and common documentation to integrate quickly. Banks benefit as they gain a controlled channel for onboarding partners and monitoring usage. Standardized contracts and certification processes reduce legal friction. Large technology and payment companies operate the most visible marketplaces, and their reach among merchants and software vendors helps new services reach customers without large direct sales teams.
Growth is strongest where marketplace features expand beyond data access to include payments, identity verification and analytics. Developers can combine several capabilities in a single integration and pay on a usage basis. Bank channels continue to play a role for institution-led propositions, while distributors and aggregators serve smaller banks that lack integration resources. New schemes for recurring payments are creating further demand for shared infrastructure that coordinates banks and merchants. The competitive emphasis is moving toward developer experience, coverage and uptime, which favors providers with broad connections.
⮞In June 2026, Erste Bank Oesterreich and Raiffeisen became shareholders in the European Payments Initiative to bring the Wero account-to-account wallet to Austria. The move shows banks building their own distribution channel for pay-by-bank services.
By End User, Banks and Traditional Financial Institutions Dominates the Open Banking Market and Fintech and Third-Party Providers Grows Fastest
Banks and traditional financial institutions hold the largest share because they are both the data holders obligated to open their interfaces and the buyers of platforms, consulting and integration services needed to comply. Spending covers developer portals, consent dashboards, fraud monitoring and customer authentication, and many institutions now treat these capabilities as products rather than compliance projects. Leading banks use the interfaces to aggregate accounts held elsewhere, launch lending services based on real-time cash flow data and offer payment initiation to corporate clients. Their balance sheets allow multi-year technology programs that smaller entrants cannot match.
Fintech and third-party providers are growing fastest because they build the customer-facing applications that make open data valuable. Budgeting tools, lenders, wealth platforms, payroll services and merchant acquirers rely on permissioned access to deliver faster onboarding and lower costs. Venture funding and acquisitions by card networks and private owners have strengthened the largest aggregators. Corporate and small business users are another expanding group, drawn by automated reconciliation and cash-flow forecasting. Consumers benefit indirectly, and consumer-facing consent controls are becoming a differentiator as regulators strengthen transparency rules.
⮞In January 2026, Commercial Bank of Dubai became the first United Arab Emirates bank to fully activate Open Finance for live use, covering retail current and savings accounts. The activation shows banks moving from compliance pilots to commercial open finance services.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
United Kingdom |
31.58% |
|
North America |
United States |
85.26% |
|
Asia Pacific |
India |
28.43% |
|
Latin America |
Brazil |
63.71% |
|
Middle East and Africa |
Saudi Arabia |
34.89% |
Europe Open Banking Market Insights
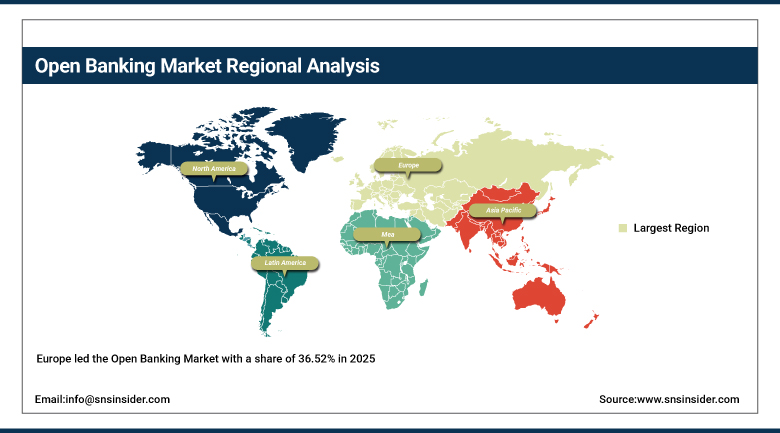
Europe led the Open Banking Market with a share of 36.52% in 2025, reflecting the region's early regulatory mandate and the maturity of its provider base. The United Kingdom has the most active user base, followed by Germany, France, the Netherlands and the Nordic countries. Banks have built interfaces under payment services rules, and licensed third parties now offer account information and payment initiation across the single market. Competition among aggregators, payment institutions and bank-owned schemes is intense, and investors continue to back pay-by-bank propositions for retail and public-sector payments.
Policy attention is shifting from access toward quality and liability. Lawmakers have agreed to update the payments framework, and a pending set of rules will require data-access dashboards, prohibit obstacles to access and clarify fraud liability. Wallets built by banking consortia aim to give European consumers a regional alternative to international card schemes, which increases interest in account-to-account rails. Open finance initiatives extend the model to savings, pensions and insurance. Fragmented national implementation and uneven interface performance remain challenges that regulators continue to address.
⮞In November 2025, the European Council and Parliament reached a provisional agreement on the payments package covering the revised Payment Services Directive and a new Payment Services Regulation. The agreement lists prohibited barriers to data access and requires customer dashboards for managing permissions.
Get Customized Report as per Your Business Requirement - Enquiry Now
North America Open Banking Market Insights
North America accounts for a substantial share of the Open Banking Market, led by the United States with Canada developing a consumer-driven banking framework. U.S. activity is led by aggregators, large banks and fintech companies that rely on account data for verification, payments and credit. Industry bodies have promoted common data standards, and the adoption of those standards by data holders has expanded steadily. Canadian authorities have set out a phased framework with accreditation requirements, which gives vendors a clearer regulatory roadmap. The region has the deepest venture ecosystem for data and payments start-ups.
Negotiations on a commercial level between the banks and aggregators are driving the marketplace. Large banks are imposing access fees and increased security requirements, thus increasing the cost of financial technology software and causing debates about the financing of the infrastructure. Other solutions, including partnering directly with the banks and tokenized access, are emerging. There is also the demand from real-time payments network services, where merchants are trying out pay-by-bank systems in order to avoid the charges associated with card payments.
⮞In April 2025, the Financial Data Exchange reported that FDX-aligned application programming interfaces carried about 114 million customer connections, up 50% from a year earlier. The growth shows steady adoption of a common standard among North American data holders.
Asia Pacific Open Banking Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 24.37% from 2026-2035, supported by public digital infrastructure, rapid smartphone adoption and regulatory programs in India, Australia, Singapore, Hong Kong and Japan. India's consent-based data sharing network connects regulated entities across banking, insurance and securities and has become a model for other emerging economies. Australia's consumer data right extends beyond banking toward energy and other sectors, while Singapore and Hong Kong promote application programming interface standards and shared data utilities for businesses.
However, market structure varies from one country to another. The Japanese financial sector operates using bank collaboration and licensing of e-payment service providers, while South East Asian countries such as Indonesia, Thailand, and Vietnam are developing instant payment networks and data layer systems. Banks and super apps are competing for customers, and lenders utilize account information to provide services to informal businesses. Challenges include differing technical standards, privacy rules and limited commercial incentives for data holders. Even so, the region's population and digital public rails make it the principal source of incremental growth.
⮞In June 2025, Australia's Consumer Data Right program reported average application programming interface availability above 99% for major data holders, with median response times falling to 680 milliseconds from 950 milliseconds. The performance data shows steady technical maturity in a framework now extending to action initiation.
MEA and Latin America Open Banking Market Insights
The Middle East and Africa is led by the Gulf states, where central banks are building regulated frameworks and national platforms. Saudi Arabia has moved from sandbox testing to formal licensing, while the United Arab Emirates operates a shared open finance infrastructure with licensed providers. Bahrain was an early adopter of mandatory standards. In Africa, Nigeria has issued a framework based on standardized interfaces, and South Africa and Kenya are active through fintech and mobile money providers. Regional banks are using open data to support lending to small businesses and to reach customers who lack branch access.
⮞In March 2026, the Saudi Central Bank announced that open banking had moved from sandbox testing to a formal licensing regime, with Lean Technologies named as the first firm to secure a license. The regime sets requirements for interface performance, data security and consent management.
Latin America is led by Brazil, whose open finance system has become one of the world's largest by consent volume, with Mexico, Colombia and Chile developing their own rules. Mexico forms part of this regional scope. The instant payment system in Brazil allows automatic payments. The Open Finance initiative in Brazil allows banks and fintech firms to share data on loans, investments, and insurance. This information helps fintech lenders and wealth managers to provide the right price of credit services. The challenges to implementing Open Finance in Brazil are consumer awareness, lack of involvement from banks, and trust.
⮞In January 2025, Febraban reported that Brazil's open finance consents had risen from 43 million to 62 million over twelve months, an increase of 44%. The growth shows how quickly consumers adopt data sharing when instant payments and lending use cases are available.
Growth Drivers: Central Bank Frameworks and Standardized Interfaces Drive Growth in the Open Banking Market
Central banks in emerging economies are issuing national frameworks that define technical standards, consent rules and licensing requirements, which gives banks and third parties a stable basis for investment. Standardized interfaces reduce the number of bilateral integrations and let smaller institutions participate without building bespoke systems. Public digital identity and instant payment infrastructure supply the authentication and settlement layers that open banking services require, and governments often pair these programs with financial inclusion goals that encourage adoption by under-served groups. Early results from mandated markets show that clear rules accelerate the arrival of new services.
Providers benefit from the network effect that follows standardization. Each new bank connected expands the audience for existing applications, and each new application increases the value of participation for banks. The specifications can be reused between nations, thus reducing the costs associated with expanding regionally. In addition, there is an implementation of performance measurement and reporting by regulators, thus increasing reliability and consumer confidence. With the maturing of frameworks, focus is now being placed on applications with higher value, including automated lending, wealth accumulation, and corporate payments.
⮞In October 2025, KPMG Nigeria reported that the Central Bank of Nigeria had rolled out a framework for open banking built on standardized application programming interfaces. The framework gives one of Africa's largest economies a defined route to data sharing.
Restraints: Data Access Fees and Fraud Liability Disputes Restrain Growth in the Open Banking Market
There are disagreements over who should foot the bill for access to the data. Banks claim that the aggregators’ usage creates a burden on their networks and increases their exposure to fraud. In turn, fintech companies argue that such fees would add costs to users and reduce competition. Where regulation does not settle the question, bilateral negotiations determine pricing, which favors the largest aggregators and disadvantages smaller entrants. The result is slower product launches and, in some cases, reduced coverage of particular institutions.
Security and liability concerns add further friction. Fraud associated with account-to-account transfers is hard to undo, and consumers might have no clue as to who should be blamed for this issue. There is the creation of new liability regulations that could cause shifting costs either between banks and payment providers. Privacy and good authentication increase the cost of operations; different levels of technical execution from one bank to another impact conversion rates. Consumers are still hesitant when it comes to the sharing of personal data.
⮞In July 2025, JPMorgan Chase introduced fees for access to consumer bank account data, and a leading aggregator subsequently signed a renewed agreement to pay for access that had historically been free. The change illustrates the commercial pressure on aggregator business models.
Opportunities: Recurring Account-to-Account Payments Create Opportunities in the Open Banking Market
Recurring payment schemes allow customers to authorize payments up to agreed limits without approving every transaction, which makes open banking suitable for subscriptions, utilities, insurance premiums and public sector charges. These payments carry lower processing cost than cards and reduce failed collections caused by expired credentials. Merchants gain predictable cash flow and banks retain the customer relationship. Industry-led schemes are now moving from pilots to commercial rollout, and large retailers and technology platforms are evaluating adoption as a way to lower payment acceptance cost.
The opportunity extends to adjacent segments. Open finance widens the data set to pensions, savings and insurance, enabling advice and switching services. Small business lending based on live account and accounting data can reach borrowers excluded by traditional underwriting. Corporate treasury tools that consolidate balances across banks are another growth area. The providers who provide reliable coverage, consent management, and liability are most well-suited for the market. Interoperability of cross border schemes at the national level would provide another demand aspect during the forecasted period.
⮞In June 2026, the UK Payments Initiative launched an open banking scheme for recurring account-to-account payments, announced at Money20/20 Amsterdam, aimed at recurring and automated payments to businesses and government. The scheme advances the commercial rollout of variable recurring payments.
Recent Developments:
-
In February 2026, eBay took a strategic investment in TrueLayer, the open banking payments provider, as large retailers evaluated pay-by-bank for checkout. The investment links a major marketplace with an account-to-account payment network and signals confidence in retail adoption of the technology.
-
In June 2026, Adyen was selected as the new payment services provider for GOV.UK Pay, covering card and pay-by-bank payments for non-Crown organizations and replacing the earlier provider for the affected services. The award gives a global payments platform a prominent public-sector pay-by-bank reference.
-
In February 2026, Plaid reached a valuation of USD 8 billion in an employee liquidity round, according to reports citing Bloomberg, as it expanded into credit scoring. The valuation reflects investor confidence in data aggregation after recent fee agreements with large banks.
-
In September 2025, STG completed its acquisition of Yodlee from Envestnet, which then refocused on wealth technology. The transaction gives the data aggregator a new private owner and separates the business from its former parent.
Open Banking Market Key Players
-
Plaid
-
TrueLayer
-
Yodlee
-
Finicity
-
MX Technologies
-
Salt Edge
-
Yapily
-
Trustly
-
Akoya
-
Belvo
-
Volt
-
Finastra
-
Fiserv
-
Jack Henry & Associates
-
Ozone API
-
Raidiam
-
Brite Payments
Open Banking Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 36.88 Billion |
| Market Size by 2035 | USD 249.34 Billion |
| CAGR | CAGR of 21.06% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Banking and Capital Markets, Payments, Digital Currencies, and Value-Added Services) • By Deployment Model (Cloud-Based, On-Premises, and Hybrid) • By Distribution Channel (Bank Channels, App Markets, Distributors, and Aggregators) • By End User (Banks and Traditional Financial Institutions, Fintech and Third-Party Providers, SMEs and Enterprises, and Consumers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Plaid, Tink, TrueLayer, Yodlee, Finicity, MX Technologies, Salt Edge, Yapily, GoCardless, Trustly, Akoya, Belvo, Volt, Finastra, Fiserv, Jack Henry & Associates, Ozone API, Raidiam, Brite Payments |

Frequently Asked Questions
Key opportunities include variable recurring payments, pay-by-bank checkout, open finance covering pensions and insurance, and small business lending based on live account data. Embedded finance and cross-border interoperability also open new revenue pools for aggregators and banks.
The major growth factor is the introduction of regulatory and central bank frameworks that require standardized data sharing, supported by instant payment systems and digital identity. These frameworks reduce integration cost and give fintech and banks a stable basis for new services.
