
Opto Semiconductors Market Report Scope & Overview:
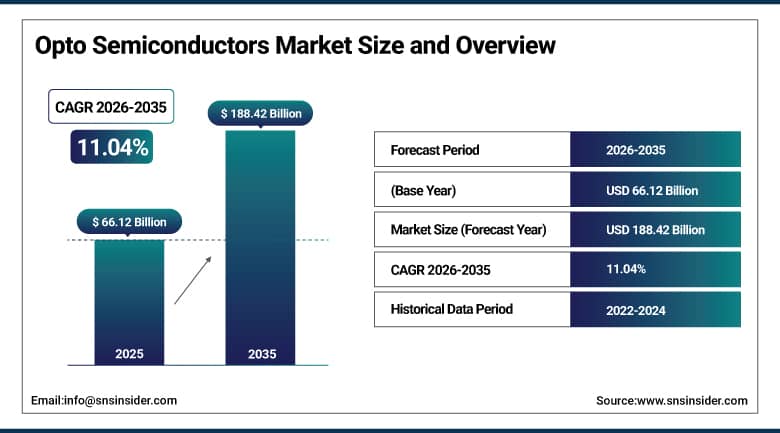
The Opto Semiconductors Market was valued at USD 66.12 Billion in 2025 and is estimated at USD 73.42 Billion in 2026. The market is projected to reach USD 188.42 Billion by 2035, expanding at a CAGR of 11.04% from 2026 to 2035. Opto semiconductors convert electricity into light or light into electrical signals, and they include LEDs, image sensors, infrared components, optocouplers, and laser diodes. They are used in lighting, cameras, vehicles, factories, and data links, so demand follows several large technology cycles at the same time. These uses keep demand diverse.
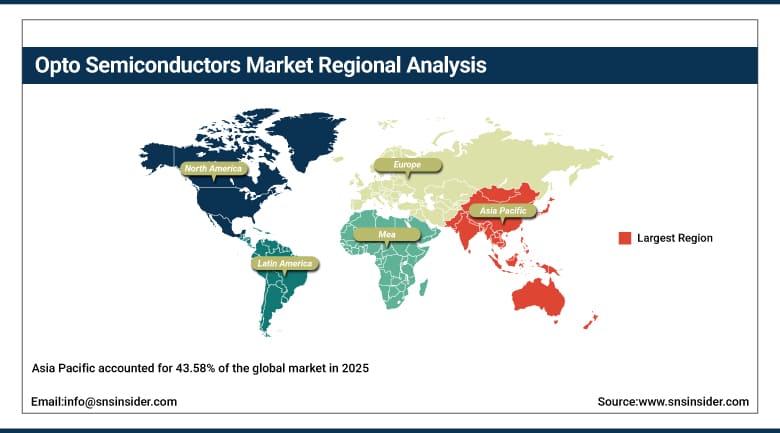
Asia Pacific held the maximum market share in 2025 with a market share of 43.58%. This region has assembled a major part of the smartphones, televisions, and automobiles in the world along with being the producer of LED and sensors. In addition to that, they have been increasing the production capacity for compound semiconductors. The government of these countries has been encouraging the production of chips within the region and due to high local demand for cameras and lighting, the plants remain busy throughout the year.
To Get More Information On Opto Semiconductors Market - Request Free Sample Report
Key Report Takeaways
- By type, LEDs held a 30.74% share in 2025, while image sensors are the fastest growing.
- By material, silicon held a 41.26% share in 2025, while gallium nitride is the fastest growing.
- By application, residential and commercial held a 54.36% share in 2025, while industrial is the fastest growing.
- By region, Asia Pacific held a 43.58% share in 2025 and is also the fastest growing.
Market Trends and Insights
Cameras with higher resolution, wider dynamic range, and depth sensing are being added to phones, cars, and security systems, which lifts demand for advanced image sensors and time-of-flight modules.
Micro-LED and mini-LED structures are moving from demonstrations to products, as makers combine thousands of tiny emitters in one chip for adaptive headlights, displays, and augmented reality light engines.
Vertical cavity lasers and photodiode arrays are being scaled for optical links inside data centers, because artificial intelligence clusters need much higher bandwidth between servers at low power.
Lighting buyers are shifting toward smart, tunable, and human-centric LED systems, while government efficiency rules continue to phase out older lamp technologies in many countries.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Automotive Lighting, ADAS, and LiDAR Adoption |
+3.21% |
Global |
Short term (2 years or less) |
|
Smartphone Cameras and 3D Sensing |
+2.87% |
Asia Pacific, North America |
Short term (2 years or less) |
|
Energy-Efficient and Smart Lighting |
+2.44% |
Global |
Medium term (2 to 4 years) |
|
Industrial Automation and Machine Vision |
+2.12% |
Europe, Asia Pacific |
Medium term (2 to 4 years) |
|
Micro-LED and Advanced Display Development |
+1.68% |
Asia Pacific, North America |
Long term (4 years or more) |
|
Optical Interconnects for Data Centers |
+1.39% |
North America, Asia Pacific |
Long term (4 years or more) |
Automotive Lighting, ADAS, and LiDAR Adoption
Modern vehicles use LEDs for headlamps and cabin lighting, image sensors for cameras, infrared devices for driver monitoring, and laser diodes for LiDAR. Safety rules and consumer demand are pushing advanced driver assistance into mainstream models. In January 2026, Hesai reported that it had delivered more than 1.6 million LiDAR units in 2025, which shows how quickly automotive sensing is moving from pilot programs to volume production. Automakers also use infrared and camera modules inside the cabin to monitor drivers, which adds further devices per vehicle.
Smartphone Cameras and 3D Sensing
Smartphones carry several cameras, proximity sensors, ambient light sensors, and depth modules, so each device contains many opto components. Brands compete on camera quality, face unlock, and low-light performance, which supports upgrades to larger sensors. In January 2026, China's Ministry of Industry and Information Technology reported output of 1.27 billion smartphones in 2025, a base that keeps sensor demand high. Foldable phones and wearables add more sensors, and under-display designs push suppliers to develop smaller and more sensitive light detectors.
Energy-Efficient and Smart Lighting
Fluorescent lamps as well as incandescent lighting products are being replaced by LED technology to reduce consumption of electrical power and to lower maintenance costs. The newer lighting devices also incorporate dimming and color tuning capabilities as well as wireless controls, which increases the worth of the devices. Other applications such as street lighting, horticulture, and commercial building retrofitting will increase production volumes, while efficiency per watt will ensure faster payback periods for operators of large buildings.
Industrial Automation and Machine Vision
Factories, warehouses, and logistics centers use image sensors, photoelectric switches, and optocouplers to inspect products, guide robots, and isolate control circuits. Growth in automation and quality inspection is increasing the number of optical channels per installation. Industrial customers value rugged parts with long life, which supports stable pricing and design wins that can last for many years. Semiconductor and electronics makers also use vision systems for inspection of boards and wafers, and logistics operators deploy optical sensors across sorting lines.
Micro-LED and Advanced Display Development
Micro-LED and mini-LED technology offers high brightness, long life, and fine control of light, and it is being developed for televisions, wearables, augmented reality glasses, and adaptive vehicle lighting. Manufacturers are investing in epitaxy, transfer methods, and testing equipment to improve yield. As costs fall, these emitters should open new categories for LED makers beyond conventional lighting and backlights. Companies such as display and lighting makers are also forming partnerships with equipment suppliers to speed up pilot lines and shorten the path to commercial products.
Optical Interconnects for Data Centers
Artificial intelligence clusters need very high bandwidth between processors, and optical links using lasers and photodiodes can carry more data at lower power than copper. Suppliers are developing arrays of vertical cavity lasers and matched photodiodes for short-reach connections. As operators build larger clusters, orders for these components are expected to grow, giving laser diode makers a new high-value outlet. Hyperscale operators are also testing co-packaged optics, which places lasers and detectors next to switching chips and increases device counts.
Restraints Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Export Controls on Critical Materials |
-1.12% |
Global |
Short term (2 years or less) |
|
Price Erosion and Overcapacity in Standard LEDs |
-0.88% |
Asia Pacific, Global |
Medium term (2 to 4 years) |
|
High Capital Cost and Thermal Efficiency Limits |
-0.41% |
Global |
Medium term (2 to 4 years) |
|
Supply Chain Concentration |
-0.26% |
Global |
Long term (4 years or more) |
Export Controls on Critical Materials
Gallium, germanium, and their associated products are used in LEDs, lasers, and infrared applications, and there is very high concentration in production. Export licenses may increase costs and delay lead times. As of November 2025, the Ministry of Commerce of China lifted the ban on exportation of gallium, germanium, and similar dual-use items to the United States until November 27, 2026. Manufacturers are creating stockpiles and trying recycling and new sources.
Price Erosion and Overcapacity in Standard LEDs
General lighting LEDs are largely standardized, and many producers have expanded capacity, which has pushed prices down year after year. Smaller manufacturers struggle to earn acceptable margins, and consolidation is common. Leading suppliers respond by moving toward automotive, horticulture, and specialty products, but a large share of volume remains exposed to price competition. Producers in Asia Pacific have added reactors and packaging lines faster than demand has grown, and price cuts are passed quickly to distributors, which compresses margins and earnings for suppliers that lack a strong specialty portfolio or brand.
High Capital Cost and Thermal Efficiency Limits
Wafer production, epitaxy reactor, and test equipment are all very costly, and improvements in yield for newer designs like micro-LEDs take some time. High-power devices have their own restrictions due to heat dissipation and inefficiencies that may lead to reduced lifetime or bigger heat sinks. All this leads to increased costs of development and slower adoption by customers who cannot afford higher prices. Companies have to compromise between performance requirements and costs, as large chips, exotic substrates, and expensive testing processes may render new devices non-competitive until yields improve.
Supply Chain Concentration
Wafer growth, packaging, and assembly for many opto devices are concentrated in a few locations and a small group of suppliers. Natural events, plant outages, or trade disputes can interrupt deliveries to carmakers and phone brands. Buyers are asking for second sources and regional production, which adds cost and requires qualification work before new suppliers can win orders. A disruption at a single site can therefore affect several industries at the same time, and the effect on prices may last longer than the event itself.
Opto Semiconductors Market Segment Analysis
By Type, LEDs Dominate Opto Semiconductors Market; Image Sensors to Register Fastest Growth.
LEDs lead the type axis, with a 30.74% share in 2025. They are used in lighting, displays, backlights, signage, vehicles, and indicators, so their volume is the largest of any opto device. Efficiency gains, long life, and falling cost per lumen have supported replacement of older lamps, while automotive and specialty LEDs carry higher value and better margins. Automotive lighting is the fastest part of this segment, since headlamps, taillamps, and interior lighting use many LEDs per modern vehicle.
Image sensors are projected to expand at a CAGR of 12.67% from 2026 to 2035. Phones, cars, security cameras, robots, and medical devices are adding more and better cameras. Improvements in resolution, dynamic range, and depth sensing, together with artificial intelligence processing at the edge, are raising the content and value of sensors in each product. Automotive makers are specifying multiple cameras per vehicle for surround view and driver monitoring, and security and medical equipment makers are following soon.
By Material, Silicon Dominates Opto Semiconductors Market; Gallium Nitride to Register Fastest Growth.
Silicon holds the largest share, at 41.26% in 2025, because image sensors, photodiodes, and many optocouplers are built on mature silicon processes. Existing wafer fabs, low cost, and integration with processing circuits give silicon a durable advantage. Camera and light sensing volumes are very large, which keeps this material at the center of the market. Silicon photodiodes and CMOS sensors also benefit from decades of manufacturing learning, which gives them low defect rates and stable supply for consumer buyers.
Gallium nitride is expected to register the fastest growth, at a CAGR of 13.38% over 2026 to 2035. It is the base material for blue and white LEDs, ultraviolet emitters, and micro-LED structures, and it is also used in power devices. Better substrates, larger wafers, and new display and automotive uses are expanding the range of products built on it. Large substrates and falling defect density are lowering the cost of gallium nitride devices, which helps them compete with silicon.
By Application, Residential & Commercial Dominates Opto Semiconductors Market; Industrial to Register Fastest Growth.
Residential and commercial uses account for 54.36% of the market in 2025. Homes, offices, shops, and public spaces use LED lighting, and consumer devices rely on image sensors, proximity sensors, and infrared components. The very large installed base and regular replacement of lamps, phones, and cameras support steady orders from distributors, brands, and building owners. Replacement cycles are short for consumer devices and lamps, so the base of products needing new sensors and emitters is refreshed every few years globally.
Industrial applications are forecast to grow at a CAGR of 12.95% during 2026 to 2035. Factory automation, machine vision, robotics, energy equipment, and optical communications need robust sensors, isolators, and lasers. Investment in smart factories and data infrastructure, along with higher component content per machine, is raising demand faster than in consumer markets. Utilities and energy companies use optical sensing for monitoring and protection of equipment, and medical device makers add photodiodes and lasers to diagnostic and surgical systems.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
87.64% |
|
Europe |
Germany |
26.82% |
|
Asia Pacific |
China |
47.59% |
|
Middle East & Africa |
Saudi Arabia |
33.45% |
|
Latin America |
Brazil |
49.76% |
Asia Pacific Opto Semiconductors Market
Asia Pacific accounted for 43.58% of the global market in 2025 and is also the fastest-growing region, with a projected CAGR of 11.90% from 2026 to 2035. China leads the region, followed by Japan, South Korea, Taiwan, and India. The region manufactures most LEDs, image sensors, and consumer devices, and it is investing heavily in compound semiconductor wafers and advanced packaging. Southeast Asian countries, led by Malaysia and Vietnam, host many assembly, test, and packaging plants for opto devices worldwide.
Local demand is large because the region produces most of the world's phones, vehicles, and appliances. Japan and South Korea lead in image sensors and premium components, Taiwan in LED chips and packaging, and China in volume lighting and rapidly growing automotive sensors. India and Southeast Asia are adding assembly and testing capacity as brands diversify production. Chinese producers are expanding in automotive LEDs and sensors, and government-backed funds are financing new compound semiconductor lines, which raises regional output and intensifies competition for global suppliers.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Opto Semiconductors Market
North America held a 28.81% share of the global market in 2025, supported by strong automotive, defense, data center, and industrial demand. The United States market was valued at USD 16.69 Billion in 2025 and is projected to grow at a CAGR of 11.58% from 2026 to 2035. In February 2026, the Semiconductor Industry Association reported that sales in the Americas rose 30.50% in 2025. Photonics clusters in California, Massachusetts, and New York support research, startups, and pilot manufacturing across the region.
Technology leadership in lasers, sensors, and photonics for data centers underpins the region. Canada contributes through photonics research and automotive suppliers, while Mexico is a major assembly base for vehicles and electronics that use opto components. Government support for local chip capacity should strengthen supply of compound semiconductor devices. Automakers in Michigan and Ohio, aerospace contractors, and cloud operators in Virginia and Oregon are major buyers, and they increasingly ask for qualified suppliers located close to their plants and data centers.
Europe Opto Semiconductors Market
Europe holds the third-largest share of the market, with Germany as the leading country, followed by France, the United Kingdom, Italy, and Austria. The region is a leader in automotive lighting, industrial sensing, and specialty photonics, and several of the largest opto component makers are headquartered there. Quality, reliability, and energy rules favor established suppliers. Austria, Switzerland, and the Nordic countries add expertise in photonics, sensors, and lighting controls that supplies local and export markets across the region's industrial base.
Industry data shows steady recovery. In June 2026, the World Semiconductor Trade Statistics organization reported that European semiconductor sales rose 6.70% in 2025. Automotive groups in Germany and France drive demand for adaptive headlights and driver monitoring, while factory automation customers buy sensors and optocouplers for industrial control systems. Energy efficiency rules and building renovation programs sustain LED replacement, while research institutes and equipment makers cooperate on micro-LED, quantum, and laser technologies that could open new product categories for European suppliers.
Latin America Opto Semiconductors Market
Latin America is a small region by value, led by Brazil, followed by Mexico, Argentina, and Colombia. Demand comes from lighting replacement, consumer electronics assembly, and automotive production. In July 2026, Brazil put the Brasil Semicon program into operation through 31 December 2029, which aims to build local semiconductor design and assembly capability. Chile and Peru buy industrial sensors for mining and renewable energy installations, while retail lighting and appliance demand adds smaller volumes across the region in several countries.
Mexico belongs to this region and is a major hub for vehicle and electronics assembly serving the United States, which creates steady demand for lighting and sensing components. Most opto devices are imported, so distributors and regional design centers play an important role in supplying manufacturers and in supporting local customers. Public lighting programs in several cities, together with solar and grid projects, are increasing LED purchases, and trade agreements with Asian suppliers keep import costs manageable for distributors and installers.
Middle East & Africa Opto Semiconductors Market
The Middle East & Africa region holds the smallest share of the market, but lighting upgrades and industrial diversification are lifting demand. Saudi Arabia and the United Arab Emirates are the main buyers, followed by Israel, Qatar, and South Africa. In March 2025, Asheil Versatile Lighting Technologies secured a 6,800 square meter site in Saudi Arabia for LED lighting manufacturing. Smart city programs and large real estate projects in the Gulf specify energy-efficient lighting and sensing systems as a standard requirement.
Efficiency rules are shaping the market. South Africa's lighting regulation moved to a second phase around May 2026, requiring a minimum of 105 lumens per watt for household lamps, which favors LED products. Gulf infrastructure projects and smart city programs add further demand, while most components are imported through distributors. Africa is at an earlier stage, with demand tied to street lighting, off-grid solar lighting, mobile devices, and telecom equipment, and it should rise as electrification programs expand and device prices fall across several countries.
Competitive Landscape
The Opto Semiconductors Market has a moderate level of concentration. ams OSRAM, Sony Semiconductor Solutions, onsemi, Vishay, Hamamatsu Photonics, Coherent, and STMicroelectronics hold strong positions in sensors, photodiodes, lasers, and LEDs, while many Asian producers compete on price in standard LEDs. Competition rests on performance, reliability, qualification for automotive use, and the ability to supply at scale.
Vendors follow several strategic lines. They are launching sensors with higher resolution and depth sensing, building laser and photodiode arrays for optical links, and developing micro-LED chips for lighting and displays. Automotive qualification, long supply agreements, and software support for sensor modules help them keep design wins for many years.
Opto Semiconductors Market Industry Leaders
1. ams OSRAM: LEDs, micro-LEDs, photodiodes, time-of-flight sensors, and VCSEL devices.
2. Sony Semiconductor Solutions: CMOS image sensors for security, mobile, and industrial cameras.
3. onsemi: Image sensors and indirect time-of-flight depth sensors.
4. Vishay: Optocouplers, PIN photodiodes, and ambient light sensors.
5. Hamamatsu Photonics: Photodiodes, avalanche photodiodes, and photonic sensors.
Companies Covered in this Report
- ams OSRAM
- Sony Semiconductor Solutions
- onsemi
- Vishay Intertechnology
- Hamamatsu Photonics
- Coherent
- STMicroelectronics
Recent Industry Developments
- March 2025: onsemi launched the Hyperlux ID family of indirect time-of-flight depth sensors with 1.2 megapixel resolution.
- September 2025: Hamamatsu Photonics released a surface-mount InGaAs avalanche photodiode for 1550 nm sensing.
- September 2025: Coherent introduced 850 nm 2D VCSEL and photodiode arrays for artificial intelligence optical interconnects.
- January 2026: ams OSRAM showed its EVIYOS Shape micro-LED with 25,600 pixels and a 48 by 32 zone time-of-flight sensor at CES.
- March 2026: Sony Semiconductor Solutions announced the IMX908 image sensor with 96 dB single-exposure dynamic range.
- June 2026: STMicroelectronics launched the VL53L9 direct time-of-flight module with 2,268 zones.
- June 2026: Vishay introduced AEC-Q102 qualified PIN photodiode ambient light sensors for automotive use.
Scope and Research Methodology
This study covers the Opto Semiconductors Market, which includes semiconductor devices that emit, detect, or respond to light, such as LEDs, image sensors, infrared components, optocouplers, and laser diodes. The base year is 2025, the forecast period is 2026 to 2035, and all values are expressed in USD. The market is segmented by type, material, application, and region. Finished lighting fixtures, cameras, and displays that contain these devices are excluded from the scope. Value reflects sales of discrete devices, modules, and arrays by manufacturers, and it excludes the value of products that contain them, along with services and software sold separately. Photovoltaic cells and solar modules are outside the scope of this report.
The research program combines secondary and primary research. Secondary research draws on company annual reports, investor presentations and filings, industry association statistics, government and trade agency records, product documentation, and peer-reviewed and industry literature. Primary research consists of structured interviews and surveys with executives, product and business heads, procurement leaders, and design engineers across the value chain, including device makers, distributors, and module suppliers. These conversations are used to validate assumptions, pricing, and adoption rates. Where several sources disagreed, the analyst team weighed them by date, scope, and transparency. Disagreements are logged and resolved before figures are locked.
Market engineering follows a bottom-up build from supplier revenue and unit shipment data, which is cross-checked top-down against end-use production volumes. Triangulation across these views confirms segment and regional estimates. Forecasts consider vehicle electrification, camera content, lighting rules, trade policy, and macroeconomic conditions, and every dataset passes an analyst quality review before publication. Currency values are held at constant 2025 exchange rates. Sensitivity checks on unit volumes, selling prices, and capacity additions produce base, optimistic, and conservative cases, and the base case is reported here. Rounding is applied only at the final stage of the build.
Opto Semiconductors Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 66.12 Billion |
| Market Size by 2035 | USD 188.42 Billion |
| CAGR | CAGR of 11.04% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (LEDs, Image Sensors, Infrared Components, Optocouplers, and Laser Diodes) • By Material (Silicon, Gallium Arsenide, Gallium Nitride, Indium Phosphide, and Others) • By Application (Residential and Commercial and Industrial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | ams OSRAM, Sony Semiconductor Solutions, onsemi, Vishay Intertechnology, Hamamatsu Photonics, Coherent, STMicroelectronics |

Frequently Asked Questions
The market was valued at USD 66.12 Billion in 2025 and is estimated at USD 73.42 Billion in 2026. It is projected to reach USD 188.42 Billion by 2035.
The market is projected to grow at a CAGR of 11.04% from 2026 to 2035, supported by automotive sensing, smartphone cameras, and optical links.
Asia Pacific leads, with a 43.58% share in 2025, owing to its dominance in electronics manufacturing and LED and sensor production.
Asia Pacific is also the fastest-growing region, with a CAGR of 11.90% from 2026 to 2035, driven by new capacity and strong local demand.
LEDs, silicon, and residential and commercial uses lead their axes. Image sensors, gallium nitride, and industrial applications are the fastest growing.
