
Packer Bottle Market Report Scope & Overview:
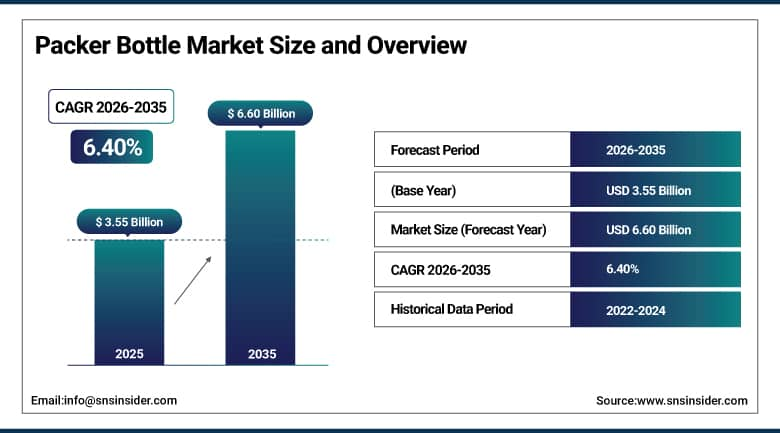
The Packer Bottle Market was valued at USD 3.55 Billion in 2025 and is expected to reach USD 6.60 Billion by 2035, growing at a CAGR of 6.40% from 2026–2035.
Packer bottles, sometimes called pill bottles or pill packers, are the wide-mouth containers that a manufacturer fills with tablets, capsules, powders, or supplements before a pharmacy or retailer ever puts a label on them, distinct from consumer-facing bottles designed around branding first. Their whole job is protection and practicality: a tight seal that keeps contents safe from oxidation and moisture, a mouth wide enough to fill quickly on a production line, and a shape that works with standard capping and labeling equipment. Growth in the pharmaceuticals and nutraceuticals sectors, where these bottles are essential for tablets, capsules, and solid dosage forms, remains the category's clearest and most consistent demand driver.
Berlin Packaging worked with a leading nutritional supplements manufacturer to redesign its packer bottles around the Star Wars franchise, leveraging a saga with multi-generational fan appeal to make vitamin bottles feel less like medicine and more like something a kid actually wants to pick up. It's a small but telling shift for a product category that spent decades as purely functional container hardware: a packer bottle's job used to end at keeping tablets dry and tamper-evident, and now it's expected to double as a marketing surface too.
To Get More Information On Packer Bottle Market - Request Free Sample Report
Packer Bottle Market Trends
- Post-consumer recycled content continues expanding across pharmaceutical and nutraceutical packer bottle lines, as manufacturers pursue documented, certified sustainability credentials that major consumer health brands increasingly require from suppliers.
- Glass packer bottles continue gaining renewed interest for light-sensitive and chemically reactive formulations, valued for their nonporous, contamination-resistant properties even as plastic remains the cost-effective default across most volume categories.
- Branded and customized packer bottle design is expanding beyond purely functional packaging, with manufacturers offering licensed franchise tie-ins and premium finishes aimed at supplement brands targeting younger or more design-conscious consumers.
- E-commerce growth continues boosting demand for durable, reliable packer bottle designs capable of surviving direct-to-consumer shipping without the protective secondary packaging traditional retail distribution typically provided.
- Manufacturers continue advancing lightweight, impact-resistant plastic formulations that reduce shipping costs and breakage rates without compromising the barrier protection pharmaceutical and nutraceutical contents require.
U.S. Packer Bottle Market Outlook
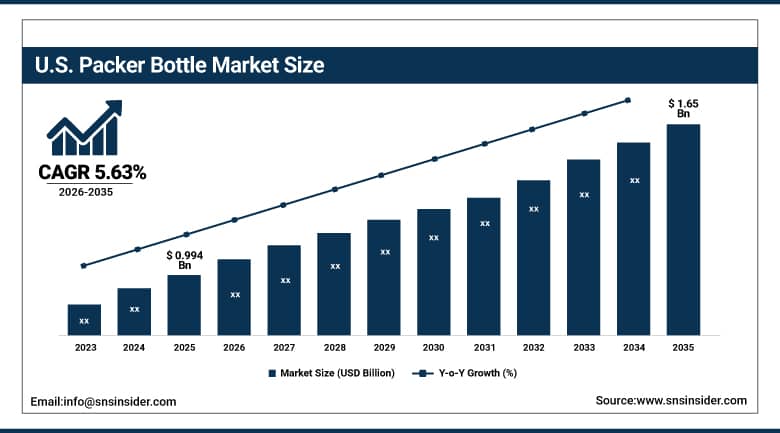
The U.S. Packer Bottle Market was valued at approximately USD 0.994 Billion in 2025 and is expected to reach approximately USD 1.65 Billion by 2035, growing at a CAGR of approximately 5.63%.
Demand in the United States is anchored by a deep pharmaceutical and nutraceutical manufacturing base, including prescription drugs, over-the-counter medicines, vitamins, minerals, and sports nutrition supplements, that collectively represent the primary driver of domestic packer bottle consumption. A concentration of established American packaging companies with decades of pharmaceutical customer relationships and documented regulatory compliance expertise continues anchoring the domestic supply base, giving the country a level of manufacturing depth that newer international entrants find genuinely difficult to replicate quickly. Growing post-consumer recycled content adoption across major suppliers continues reshaping material sourcing requirements as pharmaceutical and nutraceutical brand owners increasingly demand documented sustainability credentials from their packaging partners.
Alpha Packaging, a U.S.-based manufacturer, has built its reputation specifically around post-consumer recycled bottles with FDA and ISO certifications, offering the kind of documented regulatory compliance that pharmaceutical and nutraceutical brand owners need before they'll switch a packer bottle supplier. That certification requirement is a genuine competitive moat in the U.S. market: any manufacturer can mold a bottle out of recycled plastic, but proving it still meets pharmaceutical-grade purity and safety standards is a slower, more expensive process that favors established domestic suppliers over newer entrants.
Packer Bottle Market Segment Analysis
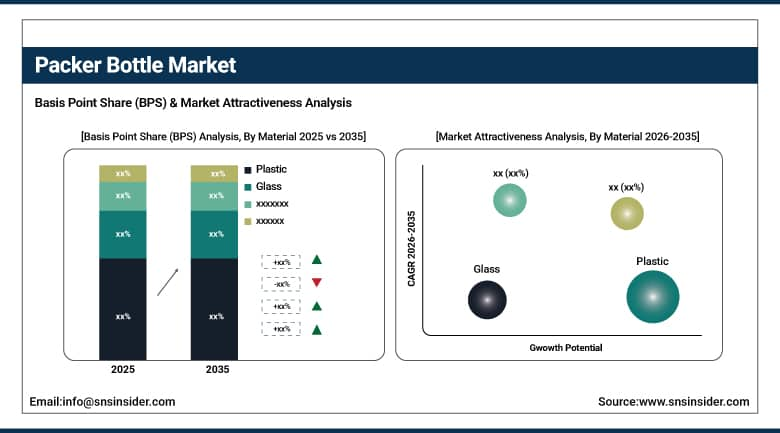
- By Material, the Plastic segment dominated the Packer Bottle Market with approximately 65.00% share in 2025, while the Glass segment is the fastest growing with a CAGR of approximately 7.40%.
- By Application, the Tablets & Capsules segment dominated the Packer Bottle Market with approximately 46.60% share in 2025, while the Powder & Granules segment is the fastest growing with a CAGR of approximately 7.80%.
- By Capacity, the Medium segment dominated the Packer Bottle Market with approximately 48.40% share in 2025, while the Small segment is the fastest growing with a CAGR of approximately 7.60%.
- By End-User Industry, the Pharmaceuticals & Nutraceuticals segment dominated the Packer Bottle Market with approximately 54.20% share in 2025, while the Personal Care segment is the fastest growing with a CAGR of approximately 7.90%.
By Material, plastic dominates, glass grows fastest
Plastic held the majority share of the material segment in 2025, reflecting the material's cost-effectiveness, light weight, and manufacturing versatility across the wide range of shapes and capacities packer bottles come in. Its impact resistance also matters enormously in this category, since a packer bottle that shatters during filling, capping, or shipping represents lost product and wasted material in a way glass simply can't avoid as easily. That combination of low cost, durability, and manufacturing flexibility keeps plastic the default material choice across the overwhelming majority of packer bottle production, particularly for high-volume pharmaceutical and nutraceutical applications where cost efficiency at scale genuinely matters.
Glass is witnessing the highest growth, as the growing concerns over the environment keep stimulating the demand for sustainable packaging options; its non-porous and impermeable nature ensures safety from contamination and chemical reactions that some products might need. The amber-colored glass bottles are still the top pick for light sensitive pharmaceutical and nutraceutical products because there are some ingredients that deteriorate in light and such deterioration cannot be prevented by plastic packaging. The demand for quality and chemically inert packaging in specialty pharmaceutical and premium supplement segments keeps boosting the above-average growth of glass.
By Application, tablets & capsules dominates, powder & granules grows fastest
Tablets and capsules held the largest application share in 2025, reflecting the sheer scale of solid oral dosage form manufacturing across prescription drugs, over-the-counter medicines, and dietary supplements that collectively represent the packer bottle industry's largest and most consistent volume driver. That established, high-frequency demand pattern, tied directly to ongoing pharmaceutical and nutraceutical production rather than any single seasonal or discretionary purchasing cycle, keeps tablets and capsules the dominant application by a wide margin over powder, granule, and liquid alternatives across the broader packer bottle market.
Powder and granules is the fastest-growing application as protein powders, meal replacement products, and powdered dietary supplements continue expanding rapidly across the broader nutraceutical and sports nutrition categories worldwide. Rising consumer interest in powdered supplement formats, often preferred for their flexibility in dosing and mixing compared to fixed-dose tablets, continues pulling this application's growth ahead of the broader, tablet-and-capsule-dominated application mix. Growing sports nutrition and wellness product categories worldwide are reinforcing this above-average growth trajectory as powder-format products continue gaining shelf space.
By Capacity, medium dominates, small grows fastest
Medium-capacity packer bottles held the largest share of the capacity segment in 2025, matching the standard bottle sizes most commonly specified across prescription and over-the-counter pharmaceutical fills, as well as typical monthly-supply vitamin and supplement packaging. That broad compatibility with the most common dosage quantities and fill volumes across the industry's largest end-use categories keeps medium capacity the default specification most manufacturers produce at the highest volume, with established filling line equipment across the industry largely calibrated around this middle capacity range.
Small-capacity packer bottles are growing fastest as single-serving, travel-size, and trial packaging formats continue expanding across personal care, pharmaceutical, and nutraceutical categories where portability and portion control both matter increasingly to consumers making smaller, more frequent purchases. Rising consumer preference for single-serving and on-the-go options is fueling demand for smaller, more portable packer bottles specifically, a trend reinforced further by growing e-commerce distribution of smaller, more shipping-efficient package formats across direct-to-consumer supplement and healthcare brands.
By End-User Industry, pharmaceuticals & nutraceuticals dominates, personal care grows fastest
Pharmaceuticals and nutraceuticals accounted for the largest end-user share in 2025, highlighting the critical role packer bottles play in drug delivery and product safety across an industry where reliable containment isn't optional but a fundamental regulatory requirement. Growing global healthcare spending, expanding pharmaceutical manufacturing capacity, and rising nutraceutical and dietary supplement consumption worldwide all continue reinforcing this application's dominant position within the broader packer bottle market, keeping demand relatively insulated from the discretionary spending fluctuations that affect more purely consumer-driven packaging categories.
Personal care is the fastest-growing end-user industry as cosmetics, skincare, and wellness product brands increasingly adopt packer bottle formats for powders, capsules, and solid-format personal care products beyond traditional liquid cosmetic packaging. Rising consumer interest in solid-format beauty and wellness products, often marketed around sustainability and reduced packaging waste, continues reinforcing this above-average growth trajectory as personal care brands increasingly borrow packaging formats and supply relationships originally developed for the pharmaceutical and nutraceutical industries.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.90% |
|
Europe |
Germany |
24.70% |
|
Asia Pacific |
China |
38.20% |
|
Latin America |
Brazil |
35.50% |
|
Middle East & Africa |
UAE |
29.60% |
North America Packer Bottle Market Insights
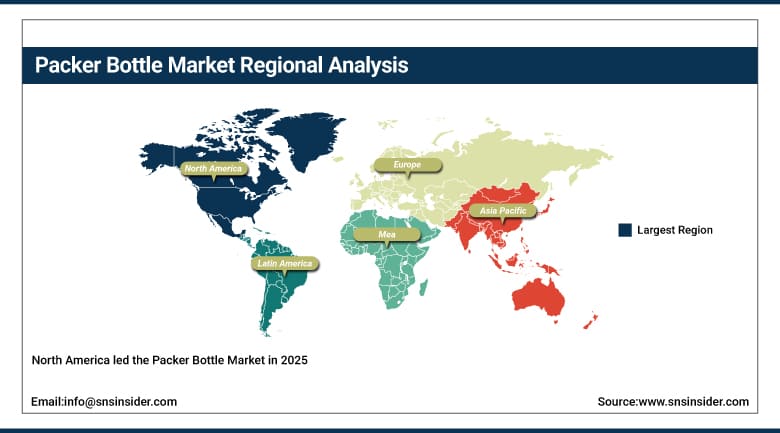
North America led the Packer Bottle Market in 2025, with the United States alone accounting for approximately 28.00% of global consumption volume, anchored by a deep pharmaceutical and nutraceutical manufacturing base spanning prescription drugs, over-the-counter medicines, vitamins, and sports nutrition supplements. That combination of manufacturing scale and regulatory compliance depth, built over decades of pharmaceutical industry relationships, keeps the region at the forefront of both consumption volume and continued packaging innovation across the broader packer bottle category. High consumer spending and stringent regulations promoting sustainable, documented packaging supply chains continue reinforcing this leading position.
Canada contributes a meaningful share through its own pharmaceutical and consumer health manufacturing sectors, while Mexico's market continues expanding alongside growing nearshoring-driven manufacturing investment tied to broader North American supply chain integration. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production and distribution networks spanning established pharmaceutical industry corridors.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Packer Bottle Market Insights
The Asia Pacific is forecasted to experience the fastest regional growth till 2035 due to an expanding manufacturing capacity for pharmaceuticals and nutraceuticals, increasing healthcare expenditure, and increasing penetration of organized retail within the most developed and fastest-growing economies of the region. Domestic pharmaceutical manufacturing expansion through government support in several Asian countries adds more fuel to this fast-paced growth trend, with several economies striving to decrease their dependency on imports of pharmaceutical packaging and develop their indigenous manufacturing capabilities.
China provides a strong base of pharmaceutical and nutraceutical manufacturing to provide a solid demand in the region, while India provides a rapidly growing industry of generics and dietary supplements that have attracted considerable investments in the manufacture of bottles. Japan and South Korea provide more developed markets focused on quality and having established standards of pharmaceutical packaging, while Southeast Asian markets follow a similar growth trend driven by healthcare infrastructure.
Europe Packer Bottle Market Insights
The European market is considered mature for packer bottle manufacturers due to the strong manufacturing base in the pharmaceutical and nutraceutical industries, coupled with strict regulations favoring sustainable and documentable packer bottle supply chain management. The major driver behind this market is the German packer bottle market, which has a substantial manufacturing base of pharmaceutical products as well as major players in the packaging industry who are experts in regulatory compliances and manufacture products for domestic as well as export clients from the pharmaceutical industry.
France, Italy, and the United Kingdom are also significant contributors to volume with substantial manufacturing bases for pharmaceutical and consumer health care products that comply with sustainability regulations set out by the EU. The increasing regional focus on glass and recyclable plastic packer bottles continues to influence product development in Europe.
MEA & Latin America Packer Bottle Market Insights
The Middle East and Africa represent a smaller but developing packer bottle market, with the UAE driving demand through growing pharmaceutical and nutraceutical retail investment tied to the region's broader economic diversification and healthcare infrastructure development goals. Growth elsewhere in the region remains tied closely to the pace of broader pharmaceutical manufacturing and organized retail infrastructure expansion across neighboring markets.
Latin America is a growing market led by Brazil, where expanding pharmaceutical and nutraceutical manufacturing continues driving demand for reliable, cost-efficient packer bottle packaging across both domestic and export-oriented healthcare product categories. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing pharmaceutical manufacturing sectors serving both regional and international markets.
Market Dynamics
Growth Drivers: Pharmaceutical demand growth and e-commerce distribution fueling adoption
Increasing demand in the pharmaceuticals and nutraceuticals sectors is one of the clearest forces behind rising packer bottle demand, as these bottles are essential for packaging tablets, capsules, and other solid dosage forms across an industry where reliable containment isn't discretionary but a fundamental regulatory requirement. That structural, regulation-anchored demand base gives the packer bottle market a level of resilience through broader economic cycles that more purely discretionary consumer packaging categories typically don't enjoy to the same degree.
E-commerce growth adds a second major driver, as expanding direct-to-consumer shipping of pharmaceutical, nutraceutical, and personal care products continues boosting demand for reliable and durable packaging solutions capable of safely reaching consumers without the protective secondary packaging traditional retail distribution channels typically provided. Growing food and beverage industry adoption of packer bottles for spices, condiments, and other dry products continues reinforcing this demand base beyond the category's traditional pharmaceutical anchor.
Restraints: Raw material price volatility and regulatory scrutiny limiting margin stability
Fluctuations in raw material prices add real cost unpredictability for manufacturers, since packer bottle producers remain exposed to broader plastic resin and glass commodity market swings that directly affect production costs and, ultimately, project budgets for pharmaceutical and nutraceutical brand owner customers. Manufacturers without long-term material supply contracts are particularly exposed to these swings, which can compress margins even when finished-bottle demand remains steady across the broader market.
Increasing regulatory scrutiny related to packaging materials and their environmental impact adds a further restraint, as manufacturers face genuine compliance costs navigating varying recycled-content mandates and material safety requirements across different jurisdictions simultaneously. That regulatory complexity falls disproportionately on smaller manufacturers without dedicated regulatory affairs capability, potentially limiting their ability to compete for large pharmaceutical and nutraceutical contracts that increasingly require documented compliance credentials.
Opportunities: Sustainable material innovation and personal care category expansion opening new growth avenues
Growing environmental concerns are expected to stimulate demand for sustainable alternatives, including eco-friendly plastics and glass packaging, offering manufacturers a genuine path to capturing premium business from pharmaceutical and nutraceutical brand owners chasing credible, documented sustainability commitments. Companies that build strong recycled-content sourcing and certification capability are positioned to capture disproportionate growth as regulatory pressure and brand-owner sustainability expectations both continue building across major markets.
Personal care category expansion represents a second significant opportunity, as cosmetics and wellness brands increasingly borrow packer bottle formats and supply relationships originally developed for pharmaceutical and nutraceutical applications to package solid-format beauty products. Manufacturers that build genuine cross-industry design and customization expertise, including licensed branding partnerships, are positioned to capture disproportionate growth as personal care brands continue diversifying beyond traditional liquid cosmetic packaging formats.
Recent Developments:
- February 2022: Comar Packaging Solutions acquired Automatic Plastics Ltd., a contract manufacturer of injection molded products primarily serving the medical device, pharmaceutical, and nutraceutical industries.
- 2025: Multiple major packer bottle manufacturers, including Berlin Packaging and O.Berk, continued expanding post-consumer recycled content offerings across their pharmaceutical and nutraceutical bottle portfolios.
- 2025: Glass packer bottle suppliers continued emphasizing wide-mouth designs paired with tamper-evident caps for vitamin, powder, and capsule packaging, differentiating from plastic on chemical inertness and contamination resistance.
- 2025: Manufacturers across the packer bottle industry continued advancing lightweight, impact-resistant plastic bottle designs aimed at reducing shipping costs and breakage rates for e-commerce-distributed pharmaceutical and nutraceutical products.
Packer Bottle Market Key Players
- Aaron Packaging, Inc.
- Xuzhou Das Packing Solution Co., Ltd.
- Alpha Packaging, Inc.
- Amcor plc
- Andler Packaging Group
- Avantis Packaging
- Beatson Clark
- Berlin Packaging
- Berry Global Group, Inc.
- CL Smith Company
- Comar, LLC
- Dongguan Fu Kang Plastic Products Co., Ltd.
- Gerresheimer AG
- Jiangmen K.K. Plastic Factory Ltd.
- Maynard and Harris
- Mpact Limited
- Shanghai Hopeck
- O.Berk Company, LLC
- Plastipak Holdings Inc.
- Consolidated Container Company LLC
Packer Bottle Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.55 Billion |
| Market Size by 2035 | USD 6.60 Billion |
| CAGR | CAGR of 6.40% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Material (Plastic, Glass, Metal) • by Application (Tablets & Capsules, Powder & Granules, Liquid) • by Capacity (Small, Medium, Large) • by End-User Industry (Pharmaceuticals & Nutraceuticals, Food & Beverages, Personal Care, Chemicals, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Aaron Packaging, Inc., Xuzhou Das Packing Solution Co., Ltd., Alpha Packaging, Inc., Amcor plc, Andler Packaging Group, Avantis Packaging, Beatson Clark, Berlin Packaging, Berry Global Group, Inc., CL Smith Company, Comar, LLC, Dongguan Fu Kang Plastic Products Co., Ltd., Gerresheimer AG, Jiangmen K.K. Plastic Factory Ltd., Maynard and Harris, Mpact Limited, Shanghai Hopeck, O.Berk Company, LLC, Plastipak Holdings Inc., Consolidated Container Company LLC |
Frequently Asked Questions
Key players in the Packer Bottle Market include Amcor plc, Berry Global Group, Inc., Berlin Packaging, Gerresheimer AG, and Alpha Packaging, Inc., among others.
Key opportunities in the Packer Bottle Market include sustainable material innovation with eco-friendly plastics and glass packaging and personal care category expansion beyond traditional pharmaceutical and nutraceutical applications.
The market is driven by increasing demand in the pharmaceuticals and nutraceuticals sectors, combined with e-commerce growth boosting demand for reliable, durable packaging solutions.
The Pharmaceuticals & Nutraceuticals segment dominated the Packer Bottle Market, accounting for approximately 54.20% market share.
The North America region dominated the Packer Bottle Market in 2025, with the United States alone accounting for approximately 28.00% of global consumption volume, driven by a deep pharmaceutical and nutraceutical manufacturing base.
