
Pediatric Hospitals Market Report Scope & Overview:
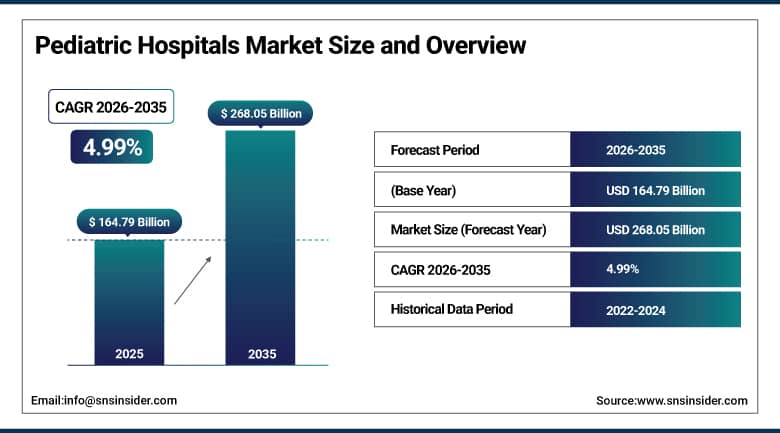
The Pediatric Hospitals Market was valued at USD 164.79 Billion in 2025 and is expected to reach USD 268.05 Billion by 2035, growing at a CAGR of 4.99% from 2026-2035.
The Pediatric Hospitals Market covers hospitals and hospital units that are built, staffed and equipped to care for newborns, children and adolescents. These facilities offer child-sized equipment, specialist physicians, child life services and family-centered care that general hospitals often cannot match. Demand comes from respiratory illness, congenital conditions, childhood cancers, mental health needs and complex chronic disease. Governments and charities are funding new children's hospitals, especially in emerging economies. Falling birth rates in some countries, workforce shortages and thin margins are limiting factors. Digital tools and regional referral networks are reshaping how care is delivered. Hospitals are also forming networks to share specialists and protocols across sites.
⮞In March 2026, the World Health Organization and partner agencies reported 4.9 million deaths of children under five and 2.3 million newborn deaths in 2024, with sub-Saharan Africa accounting for 58%. The numbers show the scale of unmet need for specialized child health services.
To Get More Information On Pediatric Hospitals Market - Request Free Sample Report
Pediatric Hospitals Market Trends:
-
Expansion of neonatal intensive care and specialty pediatric units
-
Growth of pediatric telehealth, remote monitoring and hospital-at-home programs
-
Investment in gene therapy, precision medicine and rare disease centers
-
Rising focus on pediatric mental and behavioral health services
-
Construction of new children's hospitals in Asia, the Middle East and Africa
U.S. Pediatric Hospitals Market Outlook:
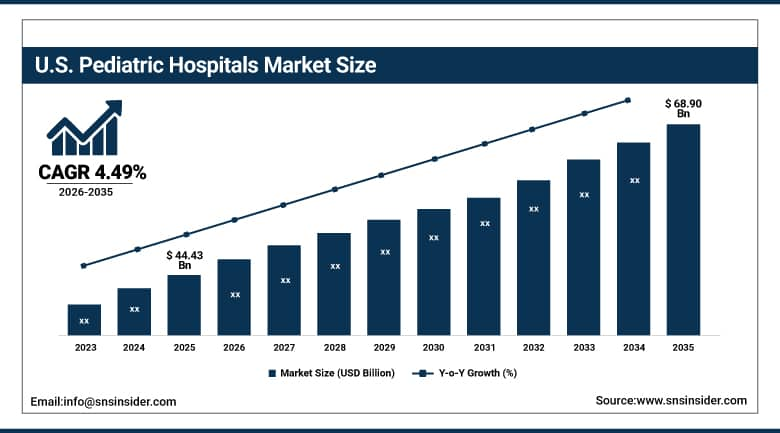
The U.S. Pediatric Hospitals Market was valued at USD 44.43 Billion in 2025 and is expected to reach USD 68.90 Billion by 2035, growing at a CAGR of 4.49% from 2026-2035.
U.S. Pediatric Hospitals Market is the largest national market and it comprises a group of free standing children’s hospitals and pediatric services located within academic medical centers. The presence of Medicaid as an important payor influences financing and growth strategies. There is an increase in investments in the areas of neonatal services, behavioral services, gene therapy, and outpatient facilities close to the families. Pediatric inpatient services have been shut down in many hospitals and this leads to a shift towards specialized institutions for treating complicated patients. Shortages of nurses and sub-specialists limit capacity. Philanthropy is an important source of funding.
⮞In April 2026, the Centers for Disease Control and Prevention's National Center for Health Statistics reported 3,606,400 U.S. births in 2025, down 1% from the year before. The birth cohort still supports a large base of newborn and child care needs.
Pediatric Hospitals Market Segment Analysis:
-
By Ownership, the For-Profit Private segment dominated the Pediatric Hospitals Market with approximately 40.76% share in 2025 and is also the fastest growing with a CAGR of approximately 5.61%.
-
By Therapeutic Area, the Respiratory segment dominated the Pediatric Hospitals Market with approximately 20.75% share in 2025, while the Endocrinology segment is the fastest growing with a CAGR of approximately 6.09%.
-
By Age Group, the School-Age segment dominated the Pediatric Hospitals Market with approximately 42.15% share in 2025, while the Adolescents segment is the fastest growing with a CAGR of approximately 6.03%.
-
By Service Type, the Inpatient Care segment dominated the Pediatric Hospitals Market with approximately 52.40% share in 2025, while the Outpatient Care segment is the fastest growing with a CAGR of approximately 6.39%.
By Ownership, For-Profit Private Dominates the Pediatric Hospitals Market and Is Also the Fastest Growing
For-profit private hospitals lead because they can raise capital quickly, move into growing urban areas and build specialty units that attract insured families. In many countries, private operators run the largest share of beds, and parents with insurance or the means to pay often choose them for shorter waits and comfort. Chains negotiate with payers and suppliers from scale, and they standardize operations across sites. Their focus on profitable services, such as neonatal intensive care, surgery and imaging, helps them maintain a strong market position. Insurers in turn offer them preferred network status when quality is high.
Private for-profit providers are also the fastest growing group as rising incomes and insurance coverage in Asia, the Middle East and Latin America lift demand for paid pediatric care. Investors are funding new facilities and acquiring existing hospitals. Public and not-for-profit hospitals remain essential for complex and charity care, but they depend on government budgets and philanthropy, which grow more slowly. Partnerships between private operators and public systems are increasing, spreading specialized capacity to more families. Medical tourism flows into private hospitals in India, Thailand and Turkey add to demand.
⮞In August 2026, the Children's Hospital Association, citing a Manatt study, reported that state-directed payments make up 38% of children's hospital Medicaid funding. The figure shows how much public financing shapes the hospital landscape.
By Therapeutic Area, Respiratory Dominates the Pediatric Hospitals Market and Endocrinology Grows Fastest
Respiratory conditions lead because asthma, bronchiolitis, pneumonia and seasonal viral infections account for a large share of pediatric admissions and emergency visits. Children are prone to airway disease, and surges in winter fill hospital beds and intensive care units. Treatment involves oxygen therapy, ventilation support and specialized nursing. Hospitals invest in respiratory therapists, pulmonary clinics and home oxygen programs. Air pollution and vaccine-preventable infections in some regions add further demand for hospital-based respiratory care. Flu and respiratory syncytial virus seasons strain staffing every year and prompt added surge capacity.
Endocrinology is the fastest growing therapeutic area as rates of childhood type 1 diabetes, obesity-related disorders and growth conditions rise. New devices such as continuous glucose monitors and insulin pumps have made specialist clinics more central to care. Hospitals are expanding diabetes education and multidisciplinary programs. Oncology, cardiology, gastroenterology and neurology also advance as survival improves and new therapies arrive, and they bring high-value procedures that support revenue. Telehealth follow-up helps clinics manage large numbers of patients with diabetes.
⮞In July 2026, the American Cancer Society projected that about 5,660 adolescents aged 15 to 19 would be diagnosed with cancer in the United States in 2026. The count shows the continuing demand for pediatric oncology care.
By Age Group, School-Age Dominates the Pediatric Hospitals Market and Adolescents Grows Fastest
School-age children aged 2 to 11 lead because they are the largest group among pediatric patients and are prone to infections, injuries, asthma and surgical needs such as tonsil and appendix procedures. Schools and clinics refer many cases to hospitals, and the group makes up a large part of elective and emergency visits. Hospitals design child-friendly spaces for this age group, with play therapy and education support, which also helps keep families loyal to a specific hospital. Sports injuries and fractures also bring many children to hospital emergency departments.
Adolescents aged 12 to 18 are the fastest growing group as mental health conditions, eating disorders, substance use and chronic disease management shift into hospital programs. Teenagers need confidential, age-appropriate services and a smooth transition to adult care. Hospitals are building behavioral health units, gender and sexual health clinics and sports medicine centers. Neonates and infants remain the most intensive users of beds, and their care is a high-cost, high-skill area for specialty centers. Schools and primary care physicians increasingly refer teenagers to hospital programs for these needs.
⮞In February 2025, the Royal College of Paediatrics and Child Health, citing NHS England data, said the paediatric elective waiting list in England had reached nearly 340,000 children. The backlog shows how demand for hospital-based child care continues to outpace capacity.
By Service Type, Inpatient Care Dominates the Pediatric Hospitals Market and Outpatient Care Grows Fastest
Inpatient care leads because hospitals earn most revenue from admissions, surgery, intensive care and long stays for complex conditions. Neonatal and pediatric intensive care units require specialized staff and equipment and generate high spending per patient. Free-standing children's hospitals also take referrals from smaller facilities, which concentrates complex cases. Even so, the number of general hospitals offering pediatric inpatient beds has fallen, raising the importance of specialized centers. Specialized centers therefore remain the core of inpatient revenue. Surgical programs for heart, brain and spine conditions are especially valuable. Hospitals with high volumes also tend to report better outcomes for complex surgery.
Outpatient care is the fastest growing service type as health systems build ambulatory surgery centers, specialty clinics and telehealth programs closer to families. Many procedures and treatments that once required an overnight stay can now be done on the same day. Payers favor lower-cost settings, and parents prefer less disruption. Emergency and critical care continue to need heavy investment, and hospital-at-home models for selected conditions are expanding the reach of pediatric teams. Families gain time and lower out-of-pocket costs, which supports adoption.
⮞In January 2025, JAMA Pediatrics researchers reported that U.S. pediatric inpatient units fell from 1,749 to 1,226 between 2008 and 2022, with beds down from 31,133 to 25,064. The decline concentrates complex inpatient care in fewer specialized hospitals.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
U.S. |
74.83 |
|
Europe |
Germany |
23.76 |
|
Asia Pacific |
China |
41.37 |
|
Latin America |
Brazil |
49.42 |
|
Middle East & Africa |
Saudi Arabia |
28.15 |
North America Pediatric Hospitals Market Insights
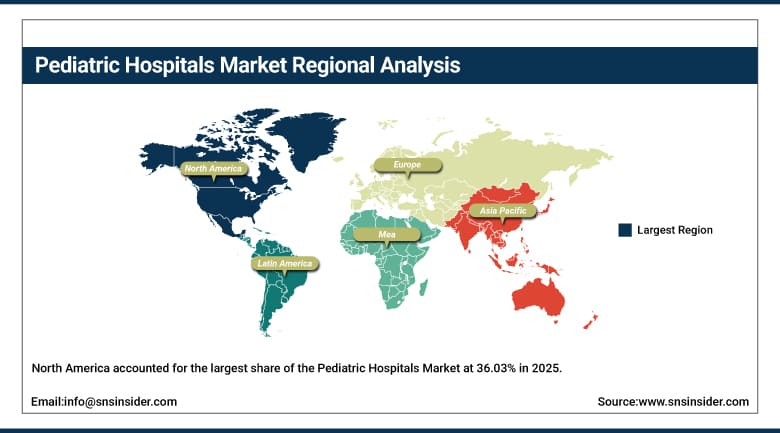
North America accounted for the largest share of the Pediatric Hospitals Market at 36.03% in 2025, led by the United States. The region has the most developed network of free-standing children's hospitals, large academic programs, advanced neonatal care and strong philanthropy. Canada adds demand through provincially funded children's hospitals in Toronto, Montreal, and Vancouver. Large donor bases support research buildings and specialty wings.
Financials and labor determine the marketplace. Medicaid and state programs pay for a considerable portion of the expenses, and thus any alteration in the policy can impact the financial status of hospitals. The facilities are now adding more capacity in behavioral health, gene therapy, and outpatient facilities, with many hospitals planning to utilize AI in their operations. The shortage of nurses and subspecialists along with slim margins is the primary barrier, with the hospitals relying on philanthropy and collaborations to finance constructions.
⮞In August 2026, Fitch Ratings reported that the median operating margin of rated children's hospitals was 3.3% in fiscal 2025, compared with 3.2% a year earlier. The thin margins explain the focus on efficiency and philanthropic funding.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Pediatric Hospitals Market Insights
Europe is led by Germany, the United Kingdom, France, Italy and Spain. Most countries fund children's hospitals through national or social insurance systems, and well-known centers in London, Rome, Paris and Berlin act as referral hubs for rare and complex disease. Research partnerships between hospitals and universities support strong clinical programs and attract patients from other countries. Foundations and national research funds provide further support.
Demographics and government spending affect growth. The birth rate in various nations is at an all-time low, hence the lower growth in volumes, but complexity of care per patient keeps increasing. Waiting lists for elective care in certain settings have increased, and the government has been allocating funds for capacity building and digitization of services. Rare disease cross-border network allows patients to benefit from specialized knowledge, while nations are building new facilities that combine research and treatment centers. Specialist labor planning is high on the list of priorities of health departments.
⮞In March 2026, Eurostat reported that the European Union's fertility rate fell to a record low of 1.34 in 2024, with about 3.55 million births, down 3.3%. Fewer births shift the focus of hospitals toward more complex care.
Asia Pacific Pediatric Hospitals Market Insights
Asia Pacific is projected to be the fastest growing region, with a CAGR of 7.33% during 2026-2035 and a 27.40% share in 2025. China, Japan, India, South Korea, Singapore and Australia lead. Large child populations in India and Southeast Asia, rising incomes and growing insurance coverage are lifting demand. Governments and private groups are building new children's hospitals and expanding neonatal units, and Singapore, Japan and Australia already operate advanced specialty centers. Medical schools are also expanding pediatric training places.
Public expenditure and medical tourism boost economic growth. India is increasing bed and intensive care unit availability in leading public children's hospitals, while China is enhancing regional centers and increasing workforce of specialists. Birth rates are declining in China, Japan and South Korea; therefore, healthcare facilities are focusing on treating complicated conditions. The reason for popularity of private chains is shorter waiting times, and lack of access to pediatric care in rural regions and shortage of pediatric specialists is one of the significant problems in Asia.
⮞In September 2026, India's Ministry of Health and Family Welfare announced that Delhi's Kalawati Saran Children's Hospital would increase beds from 394 to 894 and intensive care beds from 40 to 200. The expansion shows the scale of public investment in the region.
MEA & Latin America Pediatric Hospitals Market Insights
In Latin America, Brazil, Mexico, Argentina, Chile and Colombia lead, with public networks supplemented by private and charitable hospitals. Brazil has large specialized children's hospitals that treat patients mainly through the public system, and neonatal care is a priority as governments try to reduce newborn deaths. Philanthropic foundations also support specific units and equipment.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar, Egypt and South Africa are the main markets. Gulf states are building specialized women's and children's hospitals as part of health system modernization, and Qatar and the United Arab Emirates attract international staff and partnerships. Elsewhere in Africa, child mortality remains high and access to specialized hospitals is limited, so donors and governments are investing in neonatal units and regional referral centers. International accreditation is a goal for many new hospitals in the Gulf.
⮞In September 2025, the Pan American Health Organization reported that neonatal deaths account for more than half of child deaths in Latin America and the Caribbean. The finding supports investment in newborn intensive care across the region.
Market Dynamics:
Growth Drivers: Neonatal Care Needs and Specialty Investment Drive Growth in the Pediatric Hospitals Market
The need for neonatal care and complex illnesses fuel the demand. Early births, congenital problems and chronic diseases necessitate intensive care units and specialized staff which most general hospitals don't have. Higher chances of survival for early births and children with cancers and heart diseases results in higher number of people who need prolonged treatment. Governments in developing countries are establishing neonatal units to reduce child mortality. All these factors allow for stable growth in the bed capacity and specialty care despite the falling birth rates in some areas. Families tend to go to hospitals that can prove their success in handling particular illnesses.
Specialization and technology boost the growth. Gene therapy program, precision medicine, high-resolution imaging and robotic surgery for children become more common among hospitals. Telehealth services and remote monitoring allow reaching families living far away from big cities. Building is supported by donations and government investments, hospital-university partnerships boost research activity. The increase of insurance coverage in several countries allows for more families to get access to hospital treatment. Research institutes established by hospitals are funded by grants and industry.
⮞In November 2025, the World Health Organization's Eastern Mediterranean office reported that 11% of babies in the region are born preterm and that preterm complications cause 22.8% of deaths among children under five. The burden underlines the need for specialized newborn care.
Restraints: Falling Birth Rates and Workforce Shortages Restrain Growth in the Pediatric Hospitals Market
Falling birth rates restrain volume growth. In China, Japan, South Korea and much of Europe, fewer children are born each year, which reduces demand for routine admissions. Some hospitals consolidate or close wards as occupancy falls, and investors may delay new projects. The effect is strongest for general pediatric services, while complex and specialty care are less affected. Providers must plan for smaller cohorts and shift toward higher-acuity work. Rural hospitals with low volumes are especially vulnerable to such changes.
Workforce shortages and thin margins add further limits. Pediatric nurses, intensivists and subspecialists are in short supply, and burnout after recent respiratory surges has raised turnover. Reimbursement for children is lower than for adults in many systems, particularly under public insurance, so hospitals struggle to cover high fixed costs. Rising construction and equipment costs make expansion harder, and uneven access in rural and low-income regions limits growth in underserved populations. Wage competition from adult hospitals and private providers pushes costs higher.
⮞In January 2026, China's National Bureau of Statistics reported 7.92 million births in 2025, down from 9.54 million in 2024. The sharp drop shows the demographic pressure on pediatric volumes in a major market.
Opportunities: Emerging Market Expansion and Digital Care Create Opportunities in the Pediatric Hospitals Market
Emerging market expansion offers the largest opportunity. Governments in South Asia, Africa, the Middle East and Latin America are building dedicated children's hospitals and neonatal centers to meet population needs. These projects create demand for construction, equipment, staffing and management services. Public-private partnerships and donor funding can speed delivery, and operators from mature markets can export expertise through management contracts and training. Training programs for local doctors and nurses are a natural companion to these projects.
Digital care and precision child health provide additional openings. Artificial intelligence can help diagnose conditions earlier, predict deterioration in intensive care and plan treatment. Remote monitoring and telehealth allow hospitals to follow children at home. Gene and cell therapies for rare disease are creating new centers of excellence, and behavioral health programs are expanding. Hospitals that combine research, data and clinical care are well placed to attract funding and patients. Data sharing across hospitals can speed research on rare conditions.
⮞In June 2026, Bangladesh's Ministry of Health said it was opening five specialized children's hospitals of 200 beds each, with intensive care units, in Barishal, Khulna, Cumilla, Rangpur and Rajshahi. The program shows how emerging markets are building dedicated pediatric capacity.
Recent Developments:
-
In October 2026, The Hospital for Sick Children (SickKids) announced a five-year partnership with Microsoft Canada to apply data and artificial intelligence to precision child health. The work aims to help teams diagnose faster, treat smarter and predict outcomes better.
-
In September 2026, Nationwide Children's Hospital announced that the U.S. Food and Drug Administration approved a gene therapy for Sanfilippo syndrome Type A, developed at its research institute. The approval is the first for the condition.
-
In April 2026, Children's National Hospital in Washington, D.C. was named in a mayoral proposal for USD 1 million to fund a one-year study of sites for a new hospital campus. The study will evaluate locations for expanded pediatric services.
-
In August 2026, Texas Children's announced an expansion of its neonatal intensive care unit in Austin. The project adds capacity for critically ill newborns in the Central Texas region.
Pediatric Hospitals Market Key Players are:
-
Children's Hospital of Philadelphia (CHOP)
-
Texas Children's Hospital
-
Nationwide Children's Hospital
-
Cincinnati Children's Hospital Medical Center
-
Seattle Children's Hospital
-
St. Jude Children's Research Hospital
-
Children's Hospital Colorado
-
Children's National Hospital
-
The Hospital for Sick Children (SickKids)
-
Great Ormond Street Hospital
-
Bambino Gesù Children's Hospital
-
Sidra Medicine
-
KK Women's and Children's Hospital
-
Hospital Pequeno Príncipe
Pediatric Hospitals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 164.79 Billion |
| Market Size by 2035 | USD 268.05 Billion |
| CAGR | CAGR of 4.99% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Ownership (For-Profit Private, Not-for-Profit Private, and Public) • By Therapeutic Area (Respiratory, Endocrinology, Gastroenterology, Cardiology, Oncology, Neurology, and Others) • By Age Group (Neonates & Infants, Toddlers & Pre-School, School-Age, and Adolescents) • By Service Type (Inpatient Care, Outpatient Care, and Emergency & Critical Care) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Children's Hospital of Philadelphia (CHOP), Texas Children's Hospital, Nationwide Children's Hospital, Cincinnati Children's Hospital Medical Center, Seattle Children's Hospital, St. Jude Children's Research Hospital, Children's Hospital Colorado, Children's National Hospital, The Hospital for Sick Children (SickKids), Great Ormond Street Hospital, Bambino Gesù Children's Hospital, Sidra Medicine, KK Women's and Children's Hospital, Hospital Pequeno Príncipe |

Frequently Asked Questions
Key players include Children's Hospital of Philadelphia, Texas Children's, Nationwide Children's, Cincinnati Children's, Seattle Children's, St. Jude Children's Research Hospital, Children's Hospital Colorado, Children's National, SickKids, Great Ormond Street Hospital, Bambino Gesù, Sidra Medicine, KK Women's and Children's Hospital and Hospital Pequeno Príncipe.
Key opportunities include new children's hospitals in emerging markets, digital care and artificial intelligence, gene therapy centers and behavioral health services.
Rising complexity of pediatric illness, the need for neonatal and specialty care, and public and philanthropic investment are the main growth factors.
By Ownership, the For-Profit Private segment dominated the market in 2025 with an estimated 40.76% share, supported by its ability to raise capital and build specialty units.
North America dominated the market with a share of 36.03% in 2025, driven by a developed network of children's hospitals, academic programs and philanthropy.
