
Pharmaceutical Glass Packaging Market Report Scope & Overview:
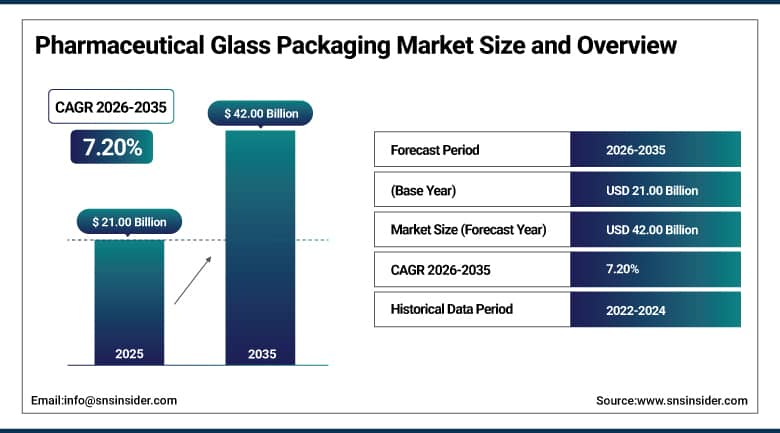
The Pharmaceutical Glass Packaging Market was valued at USD 21.00 Billion in 2025 and is expected to reach USD 42.00 Billion by 2035, growing at a CAGR of 7.20% from 2026–2035.
Pharmaceutical glass packaging is crucial in ensuring pharmaceutical products' safety, integrity, and efficacy, using specially designed glass containers and closures to protect drugs from moisture, light, and chemical interactions that could compromise their quality. More than 65% of injectable drugs globally are stored in glass containers specifically because glass offers a level of chemical resistance and impermeability that plastic alternatives still can't reliably match, particularly for biologics and other formulations sensitive to even trace contamination. The category has become genuinely strategic rather than purely industrial, since a vial shortage or quality failure can directly delay a vaccine rollout or a critical drug supply chain in ways few other packaging categories can.
SCHOTT Pharma inaugurated an expanded glass vial manufacturing facility in Lebanon, Pennsylvania in 2025, a more than $60 million investment largely funded by the U.S. Biomedical Advanced Research and Development Authority that more than tripled local capacity for high-value vial solutions. The company generated €986 million in revenue in fiscal 2025 supplying the top 30 leading pharmaceutical manufacturers for injectable drugs, and its own statistic puts the stakes in perspective: every minute, more than 30,000 people around the world receive an injection packaged in a SCHOTT Pharma product.
To Get More Information On Pharmaceutical Glass Packaging Market - Request Free Sample Report
Pharmaceutical Glass Packaging Market Trends
-
Ready-to-use vial formats continue gaining adoption, as they support pharmaceutical manufacturers and contract manufacturing organizations by reducing manual preparation steps and simplifying regulatory compliance for sterile injectable production.
-
Domestic manufacturing capacity expansion continues accelerating in the United States, backed by federal funding aimed at strengthening pharmaceutical supply chain resilience for critical primary packaging materials.
-
Advanced glass vial coating technology continues advancing, improving drug-container compatibility and reducing the risk of delamination that has historically affected certain injectable drug formulations stored in glass.
-
Industry consolidation and portfolio rationalization continue reshaping the competitive landscape, as leading manufacturers acquire complementary businesses while divesting lower-margin, non-core packaging operations.
-
Demand for specialty packaging supporting antibody-drug conjugates, GLP-1 therapies, and other advanced biologics continues expanding faster than conventional generic drug packaging volume.
U.S. Pharmaceutical Glass Packaging Market Outlook
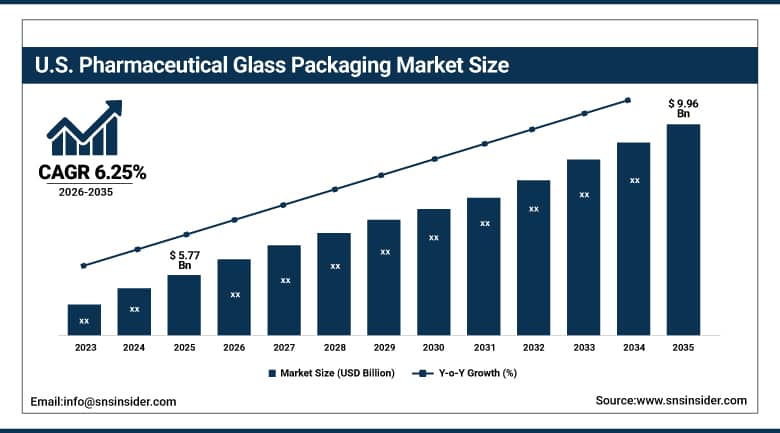
The U.S. Pharmaceutical Glass Packaging Market was valued at approximately USD 5.77 Billion in 2025 and is expected to reach approximately USD 9.96 Billion by 2035, growing at a CAGR of approximately 6.25%.
Demand in the United States is anchored by rising demand for pharmaceutical products, stringent regulations and quality standards imposed by regulatory authorities, and growing focus on product safety and integrity across the domestic pharmaceutical manufacturing base. Federal investment through the Biomedical Advanced Research and Development Authority continues supporting expanded domestic glass vial production capacity, aimed at reducing American reliance on imported packaging for biologics, vaccines, and emergency medications. A concentration of the world's leading pharmaceutical glass manufacturers, several with major domestic manufacturing footprints, continues anchoring both supply security and innovation capacity.
The Lebanon, Pennsylvania expansion was funded largely through the U.S. Biomedical Advanced Research and Development Authority specifically to strengthen domestic pharmaceutical supply chains and reduce American reliance on imported glass vials for biologics, vaccines, and emergency medications. That kind of federal investment in a foreign-headquartered company's domestic manufacturing capacity reflects how seriously U.S. health authorities now treat pharmaceutical packaging as critical infrastructure, not just an ordinary industrial supply chain component.
Pharmaceutical Glass Packaging Market Segment Analysis
-
By Product, the Bottles segment dominated the Pharmaceutical Glass Packaging Market with approximately 64.00% share in 2025, while the Ampoules segment is the fastest growing with a CAGR of approximately 9.80%.
-
By Glass Type, the Type I/Borosilicate segment dominated the Pharmaceutical Glass Packaging Market with approximately 55.00% share in 2025, while the Type III/Amber Glass segment is the fastest growing with a CAGR of approximately 8.40%.
-
By Application, the Injectable Drugs segment dominated the Pharmaceutical Glass Packaging Market with approximately 58.60% share in 2025, while the Oral/Topical Drugs segment is the fastest growing with a CAGR of approximately 7.80%.
-
By End-Use, the Pharmaceutical Companies segment dominated the Pharmaceutical Glass Packaging Market with approximately 70.00% share in 2025, while the Biotechnology Firms segment is the fastest growing with a CAGR of approximately 9.20%.
By Product, bottles dominates, ampoules grows fastest
Bottles held the largest share of the product segment in 2025, driven by their superior barrier properties and durability across a wide range of oral and topical drug packaging applications that make up the bulk of overall pharmaceutical volume by unit count. That combination of broad application and proven reliability keeps bottles the dominant product category across the pharmaceutical glass packaging market, particularly for generic and over-the-counter medications produced at high volume.
Ampoules are growing fastest as their advantages in preserving sterility continue winning favor for single-dose injectable applications where contamination risk must be minimized as completely as possible. Ampoules and vials together serve as the backbone of injectable drug packaging used daily in hospitals and clinics, and rising global demand for biologics, vaccines, and high-potency pharmaceuticals is reinforcing this above-average growth trajectory relative to the broader, bottle-dominated product mix.
By Glass Type, Type I/borosilicate dominates, Type III/amber glass grows fastest
Type I borosilicate glass held the majority share of the glass-type segment in 2025, valued for its superior chemical and thermal properties that ensure drug integrity and sterility across the most demanding pharmaceutical applications. Its low alkali content and exceptional resistance to leaching keep Type I glass the required standard for injectable drug packaging and other applications where even minimal chemical interaction between container and contents isn't acceptable.
Type III and amber glass are growing fastest as light-sensitive oral and topical drug formulations increasingly require the protective properties amber glass specifically provides against photodegradation. Growing pharmaceutical product diversification beyond injectable formulations, combined with expanding generic drug manufacturing in emerging markets where Type III glass offers a more cost-efficient alternative to borosilicate, continues reinforcing this above-average growth trajectory.
By Application, injectable drugs dominates, oral/topical drugs grows fastest
Injectable drugs accounted for the largest application share in 2025, representing the largest segment of the pharmaceutical glass packaging market given the increasing demand for biologics, vaccines, and injectable drugs that has driven the need for high-quality glass packaging solutions preventing drug degradation. That combination of stringent sterility requirements and rising biologics manufacturing volume keeps injectable drugs the dominant application category by a wide margin over oral and topical alternatives.
Oral and topical drugs are growing fastest as pharmaceutical manufacturers continue expanding generic drug production and diversifying beyond the injectable formulations that have historically dominated glass packaging demand. The high effectiveness of biological drugs for treating chronic and autoimmune diseases is expected to drive continued growth across both application categories, with oral and topical formulations increasingly adopting glass packaging for light-sensitive and moisture-sensitive formulations specifically.
By End-Use, pharmaceutical companies dominates, biotechnology firms grows fastest
Pharmaceutical companies accounted for the large majority of the end-use segment in 2025, due to strict drug safety regulations and increasing demand for inert, high-quality packaging for medicines and vaccines produced at large commercial manufacturing scale. That combination of regulatory requirement and manufacturing volume keeps pharmaceutical companies the dominant end-use category across the entire pharmaceutical glass packaging market by a wide margin over biotechnology and research applications.
Biotechnology firms are the fastest-growing end-use category as rising demand for biopharmaceuticals and increased focus on patient safety continue expanding demand for specialized glass packaging suited to complex biologic formulations. Growing biotech investment in advanced therapies, including antibody-drug conjugates and cell and gene therapies requiring highly specialized, contamination-resistant packaging, continues reinforcing this above-average growth trajectory.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.80% |
|
Europe |
Germany |
25.70% |
|
Asia Pacific |
China |
40.60% |
|
Latin America |
Brazil |
35.60% |
|
Middle East & Africa |
Saudi Arabia |
29.90% |
North America Pharmaceutical Glass Packaging Market Insights
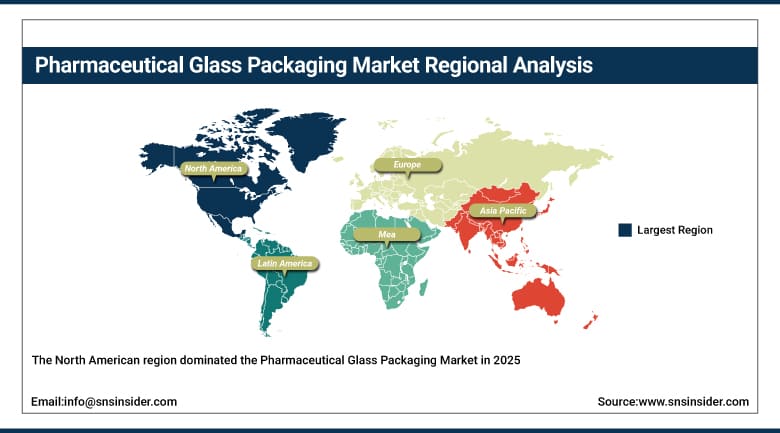
The North American region dominated the Pharmaceutical Glass Packaging Market in 2025, holding a share of roughly 33.60% of the total global revenue of the market, owing to the well-developed healthcare sector and increasing demand for pharmaceutical products due to a highly developed pharmaceutical manufacturing sector in the region. The rapid growth of the pharmaceutical sector, along with increased treatment of communicable and non-communicable diseases, further cements this dominance in the healthcare sector in North America.
While Canada adds its portion owing to the development of the pharmaceutical and biotechnology manufacturing sectors within the country, Mexico has been witnessing growth in the market along with increasing investment in pharmaceutical manufacturing in Mexico, owing to the supply chain integration of the North American market. The cross-border supply relationships among the countries of North America have helped many manufacturers serve the market in all three countries.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Pharmaceutical Glass Packaging Market Insights
Asia Pacific is anticipated to exhibit the highest regional growth through the forecast period, driven by increased healthcare investments and demand for sustainable packaging solutions across the region's largest and fastest-growing pharmaceutical manufacturing economies. Expanding pharmaceutical manufacturing ecosystems and growing domestic healthcare consumption continue reinforcing this accelerating growth trajectory across both injectable and oral drug packaging applications.
China's expanding pharmaceutical manufacturing base gives the region substantial baseline demand, while India's rapidly growing generic drug and biopharmaceutical industries are drawing significant new investment in glass packaging production capacity. Japan and South Korea represent more mature, quality-focused markets with established pharmaceutical glass manufacturing standards, while Southeast Asian markets continue following a similar healthcare-infrastructure-driven growth trajectory.
Europe Pharmaceutical Glass Packaging Market Insights
Europe represents a mature, technically advanced pharmaceutical glass packaging market, The European market is considered an advanced and mature one in the sphere of pharmaceutical glass packaging industry, with numerous manufacturers of glass packaging containers being leaders in the world, having considerable experience in developing and producing specialty coatings and sterile ready-to-use packaging technology.
Germany is a core country from this perspective, where there is a strong pharmaceutical manufacturing sector and glass packaging manufacturers are developing high-capacity plants for biologic and injectable drugs.
Hungary, France, and Italy also represent substantial volumes, with each of them having pharmaceutical glass manufacturing capacity serving both domestic and export-oriented pharmaceutical clients. Further development of manufacturing capacity for sterile ready-to-use cartridges and vials in the European region will ensure demand for advanced pharmaceutical packaging technology.
MEA & Latin America Pharmaceutical Glass Packaging Market Insights
The Middle East and Africa represent a smaller but strategically developing pharmaceutical glass packaging market, with Saudi Arabia driving demand through substantial healthcare infrastructure investment tied to the country's broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader pharmaceutical manufacturing and healthcare infrastructure development.
Latin America is a growing market led by Brazil, where expanding pharmaceutical manufacturing and rising healthcare investment continue driving demand for reliable, high-quality glass packaging. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing pharmaceutical manufacturing sectors serving both regional and export markets.
Market Dynamics
Growth Drivers: Rising biologics demand and regulatory quality standards fueling adoption
One of the most evident drivers of increased demand for pharmaceutical glass packaging is the high demand for biologics, vaccines, and injectable drugs, which have complex compositions requiring the high chemical resistance and contamination protection that glass can provide better than any other material. The performance requirement for pharmaceutical glass provides an unshakable demand base linked to the healthcare demands that grow steadily regardless of the economic situation.
Regulatory standards and quality requirements set for the packaging of pharmaceuticals by the regulatory agencies represent another strong factor driving increased demand, as the demand for pharmaceuticals grows while the need to ensure drug safety grows stricter. Increased awareness of the superiority of glass packaging relative to any other type of packaging contributes to this trend in the major pharmaceutical markets.
Restraints: High production costs and breakage risk limiting broader adoption
Higher costs involved in manufacturing specialty pharmaceutical grade glass is a real limitation since the process of manufacturing the borosilicate glass to fit the exact specifications necessary for pharmaceutical use will cost significantly more than making ordinary glass or plastics. This can be a problem where the cost issue affects the use of glass over cheaper plastic in certain generic drugs.
The possibility of breakage during manufacturing, filling, transportation and handling represents yet another limitation, since glass bottles are naturally more fragile than plastic alternatives. Special handling processes and packaging required for such products can be quite costly in the pharmaceuticals industry.
Opportunities: Domestic manufacturing capacity expansion and specialty biologics packaging opening new growth avenues
Domestic manufacturing capacity expansion offers manufacturers a genuine path to capturing government-backed investment aimed at strengthening pharmaceutical supply chain resilience, particularly in markets prioritizing reduced reliance on imported critical packaging materials. Companies that build strong domestic production capability, backed by public health authority funding, are positioned to capture disproportionate growth as supply chain security becomes a genuine strategic priority.
Specialty biologics packaging represents a second significant opportunity, as expanding antibody-drug conjugate, GLP-1 therapy, and cell and gene therapy pipelines continue requiring highly specialized, contamination-resistant glass packaging beyond conventional vial and ampoule formats. Manufacturers that build genuine specialty packaging capability are positioned to capture premium pricing from biotechnology customers prioritizing performance and regulatory compliance over pure cost considerations.
Recent Developments:
-
June 2025: SCHOTT Pharma announced a more than €100 million investment at its Lukácshaza, Hungary site to construct a sterile ready-to-use cartridge manufacturing facility supporting biologics, GLP-1 therapies, insulin, and obesity treatments.
-
August 2025: Gerresheimer announced the decision to separate and initiate a sales process for its Moulded Glass business, aligning with its strategy to become a pure-play provider of pharmaceutical and biotech systems.
-
2025: Gerresheimer and Corning formed a branded vial partnership, converting Corning's glass platform into vial form with production across Gerresheimer's facilities in North America, Europe, and Asia.
-
August 2026: Gerresheimer agreed to divest its Centor US Holding and global primary packaging plastics businesses to an affiliate of Apax Partners for approximately €1.5 billion, further concentrating its focus on injectable drug packaging.
Pharmaceutical Glass Packaging Market Key Players
-
Schott AG (Schott Pharma)
-
Gerresheimer AG
-
Nipro Corporation
-
Amcor plc
-
Owens-Illinois, Inc.
-
Corning Incorporated
-
Stölzle Glass Group
-
West Pharmaceutical Services, Inc.
-
SGD Pharma
-
Piramal Pharma Solutions
-
Bormioli Pharma S.p.A.
-
APG Pharma
-
Ardagh Group S.A.
-
Shandong Pharmaceutical Glass Co., Ltd.
-
Beatson Clark
-
DWK Life Sciences
-
Wheaton Industries, Inc.
-
Dätwyler Holding Inc.
-
Fu Yuan Pharmaceutical Glass
-
Kaisha (Beijing) Pharmaceutical Glass
Pharmaceutical Glass Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 21.00 Billion |
| Market Size by 2035 | USD 42.00 Billion |
| CAGR | CAGR of 7.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product (Ampoules, Bottles, Vials, Syringes, Cartridges, Others) • by Glass Type (Type I/Borosilicate, Type II, Type III, Amber Glass) • by Application (Injectable Drugs, Oral/Topical Drugs, Others) • by End-Use (Pharmaceutical Companies, Biotechnology Firms, Research Laboratories) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Schott AG (Schott Pharma), Gerresheimer AG, Nipro Corporation, Amcor plc, Owens-Illinois, Inc., Corning Incorporated, Stölzle Glass Group, West Pharmaceutical Services, Inc., SGD Pharma, Piramal Pharma Solutions, Bormioli Pharma S.p.A., APG Pharma, Ardagh Group S.A., Shandong Pharmaceutical Glass Co., Ltd., Beatson Clark, DWK Life Sciences, Wheaton Industries, Inc., Dätwyler Holding Inc., Fu Yuan Pharmaceutical Glass, Kaisha (Beijing) Pharmaceutical Glass |
Frequently Asked Questions
Key players in the Pharmaceutical Glass Packaging Market include Schott AG, Gerresheimer AG, Nipro Corporation, Amcor plc, and Owens-Illinois, Inc., among others.
Key opportunities in the Pharmaceutical Glass Packaging Market include domestic manufacturing capacity expansion backed by public health authority funding and specialty biologics packaging for antibody-drug conjugates and GLP-1 therapies.
The market is driven by increasing demand for biologics, vaccines, and injectable drugs, combined with stringent regulations and quality standards imposed by regulatory authorities.
The Bottles segment dominated the Pharmaceutical Glass Packaging Market, accounting for approximately 64.00% market share.
The North America region dominated the Pharmaceutical Glass Packaging Market in 2025 with approximately 33.60% share, driven by robust healthcare infrastructure and rising demand for pharmaceutical products.
