
Single-Use Packaging Market Report Scope & Overview:
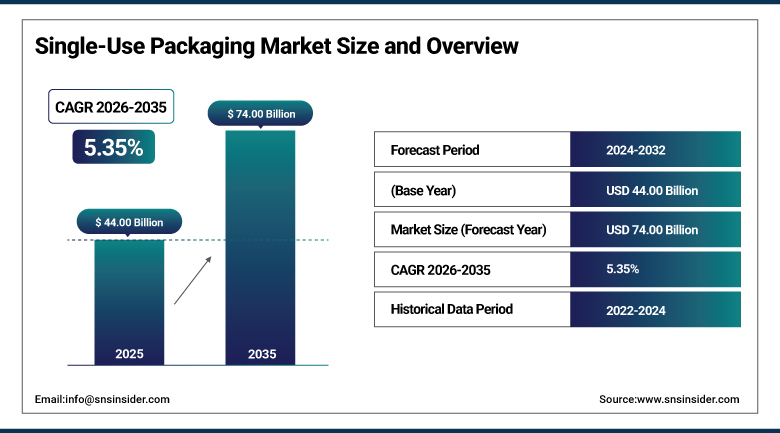
The Single-Use Packaging Market was valued at USD 44.00 Billion in 2025 and is expected to reach USD 74.00 Billion by 2035, growing at a CAGR of 5.35% from 2026–2035.
Single-use packaging is designed to be used once and thrown away, the cups, wrappers, pouches, and trays that make food service, healthcare, and e-commerce run at the speed and hygiene standard modern consumers expect. Its commercial success has never really been in question, despite the mounting plastic waste headlines, because flexibility, strength, light weight, and simplicity of sterilizing remain genuinely hard to replicate in a reusable format at comparable cost. The real story reshaping this market isn't decline, it's a steady material shift, as single-use paper packaging keeps gaining ground as an environmentally beneficial alternative that lets brand owners keep the convenience of single-use without the plastic waste headline.
Huhtamaki officially launched recyclable single coated paper cups crafted for dairy products and yogurt in February 2025, engineered to align with high food safety requirements while replacing the multi-layer plastic-lined cups that category has traditionally relied on. Dairy and yogurt cups have historically been a particularly stubborn packaging category to make genuinely recyclable, since the plastic coating that keeps liquid dairy from soaking through paper is exactly what makes conventional cups hard to recycle, and solving both problems in the same product is a real materials-engineering achievement.
To Get more information Single-Use Packaging Market - Request Free Sample Report
Single-Use Packaging Market Trends
-
Single-use paper packaging continues gaining traction as an environmentally beneficial alternative to conventional plastic, particularly across food service cups, containers, and food contact materials.
-
Pharmaceutical and healthcare single-use packaging continues expanding rapidly, driven by rising global demand for sterile, contamination-free packaging for syringes, vials, IV bags, and other medical disposables.
-
E-commerce and home delivery growth continues driving demand for packaging that ensures safe transport and product protection, a use case single-use formats handle more cost-effectively than reusable alternatives at scale.
-
Biobased and bio-derived film technology continues advancing across specialized applications, including single-use bioprocessing containers now earning independently verified sustainability certifications.
-
Industry-wide collaborative initiatives continue targeting specific single-use plastic categories, with brand and retailer coalitions publishing concrete guidelines for eliminating avoidable plastic packaging formats like poly bags.
U.S. Single-Use Packaging Market Outlook
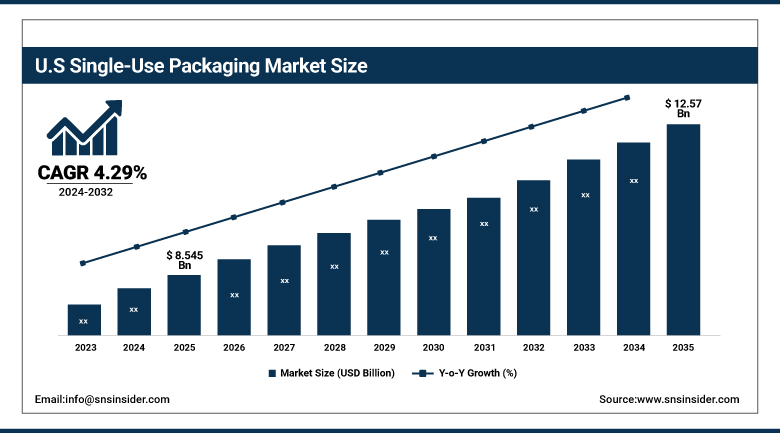
The U.S. Single-Use Packaging Market was valued at approximately USD 8.545 Billion in 2025 and is expected to reach approximately USD 12.57 Billion by 2035, growing at a CAGR of approximately 4.29%.
The US demand is shaped by the increased emphasis on health and safety considerations especially in the food and pharmaceutical sectors together with the rise in the adoption of e-commerce and delivery services that necessitate safe and protective packaging. The food products such as baby food, pharmaceuticals and ready to eat meals are some of the key pillars of domestic demand as health and convenience are still top priorities in these product lines despite the growing sustainability considerations facing the packaging industry. Increasing state bans on single use plastics continue to shape material specification needs.
The European Outdoor Group and more than 30 outdoor brands, retailers, and packaging firms took coordinated action in February 2025 to reduce the environmental impact of single-use plastic packaging through the Single Use Plastics Project, first launched in 2018. The initiative specifically targets garment poly bags, releasing practical guidelines for merchants on eliminating them from operations, a reminder that reducing single-use packaging often comes down to unglamorous category-by-category work rather than one sweeping industry-wide fix.
Single-Use Packaging Market Segment Analysis
-
By Product, the Flexible Packaging segment dominated the Single-Use Packaging Market with approximately 58.60% share in 2025, while the Rigid Packaging segment is the fastest growing with a CAGR of approximately 6.20%.
-
By Material Type, the Plastic segment dominated the Single-Use Packaging Market with approximately 46.80% share in 2025, while the Paper & Paperboard segment is the fastest growing with a CAGR of approximately 7.40%.
-
By End-User Industry, the Food & Beverage segment dominated the Single-Use Packaging Market with approximately 42.60% share in 2025, while the Pharmaceutical & Healthcare segment is the fastest growing with a CAGR of approximately 6.80%.
By Product, flexible packaging dominates, rigid packaging grows fastest
Flexible packaging had the largest market share within the product category in 2025 because it was more economical with respect to materials, lighter in shipping weight, and easier to store compared to rigid packaging in all of the many types of pouches, wraps, and bags in which single-use products come packaged. It is thus the preferred form of packaging in the categories of food service, personal care, and pharmaceuticals whenever the structural protection provided by rigid packaging is not required.
The fastest-growing category is the rigid packaging, which is experiencing increased demand because of the continuing growth in online purchases and the need for more robust shipping and handling containers, cups, and trays compared to flexible packaging. Consumer demands for intact products upon receipt and tamper-evident packaging continue to drive this above-average growth trend especially for meals and drinks.
By Material Type, plastic dominates, paper & paperboard grows fastest
Plastic held the largest share of the material-type segment in 2025, reflecting the mix of flexibility, strength, lightness, stability, impermeability, and simplicity of sterilizing that has made it a commercially successful packaging material despite well-documented environmental concerns. Its compatibility with high-speed production equipment and low per-unit cost keeps plastic the default material choice across the majority of single-use packaging volume, particularly in food service, personal care, and industrial applications.
Paper and paperboard is growing fastest as single-use paper packaging continues acquiring significant traction because it represents an environmentally beneficial alternative to conventional plastic formats. Rising regulatory pressure on plastic waste, combined with genuine improvements in paper-based barrier coating technology that narrow the performance gap with plastic, continues reinforcing this above-average growth trajectory relative to the broader, plastic-dominated material mix.
By End-User Industry, food & beverage dominates, pharmaceutical & healthcare grows fastest
The food and beverage segment had the highest end-user share in 2025 and continued to serve as the biggest contributor to the overall single-use packaging market due to the usage of quick-service, food service cups, containers, and food contact materials in almost all forms of dining and takeaway across the globe. The growing number of disposable food packaging products, ranging from coffee cups to takeaway containers, makes food and beverages the dominant end-user segment over all other industries.
The fastest growing end-user segment was pharmaceutical and healthcare, as increasing global demand for medical products, medications, and healthcare services requires single-use packaging to keep the products sterile and contamination-free. Single-use packaging is an easy and cost-effective solution to package such medical disposables as syringes, vials, IV bags, and many others, required for both hospital and home usage.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
40.60% |
|
North America |
United States |
80.90% |
|
Europe |
Germany |
24.80% |
|
Latin America |
Brazil |
35.60% |
|
Middle East & Africa |
UAE |
30.20% |
Asia Pacific Single-Use Packaging Market Insights
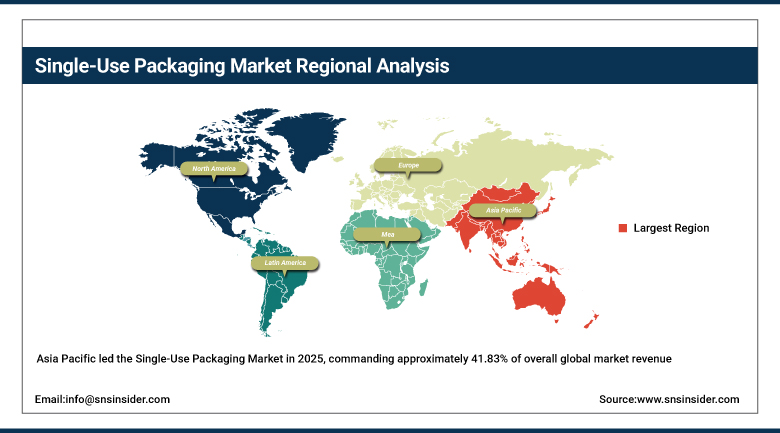
Asia Pacific led the Single-Use Packaging Market in 2025, commanding approximately 41.83% of overall global market revenue, driven by rapid urbanization, expanding food service and e-commerce activity, and rising packaged goods consumption across the region's largest and fastest-growing economies. Government policies promoting sustainability alongside continued manufacturing capacity expansion across multiple Asian countries keep regional single-use packaging production growing in step with rising domestic consumer demand.
China's massive food processing and consumer goods manufacturing base gives the region substantial baseline demand, while India's expanding organized retail and pharmaceutical sectors are drawing significant new investment in single-use packaging capacity. Japan and South Korea represent more mature, technology-forward markets with established packaging standards, while Southeast Asian markets continue following a similar urbanization-driven growth trajectory as regional infrastructure expands.
Get Customized Report as per Your Business Requirement - Enquiry Now
Middle East & Africa Single-Use Packaging Market Insights
Africa and the Middle East are forecasted to show the highest regional growth until 2035, driven by development of infrastructure and increased consumer expenditure in the fastest developing economies of the region. UAE leads this trend, with growth fueled by expansion of the hospitality, healthcare, and retail sectors linked to the diversification efforts of the region.
The next major contribution to the demand comes from Saudi Arabia, which will see increased expenditures in infrastructure as well as growth in pharmaceutical and food manufacturing industries as part of its diversification efforts. South Africa becomes the demand driver for the rest of the continent due to its more developed manufacturing and retail industry.
North America Single-Use Packaging Market Insights
North America represents a substantial single-use packaging market, with the United States accounting for the large majority of regional demand through its rising focus on health and safety across food and pharmaceutical industries. Growing state-level single-use plastic restrictions continue reshaping material specification requirements, pushing domestic manufacturers toward paper and other more easily recyclable single-use alternatives across food service and retail categories.
Canada contributes additional demand through its own food processing and healthcare manufacturing sectors, while Mexico's market continues expanding alongside growing nearshoring-driven manufacturing investment. Cross-border supply relationships tie much of North American demand together, with major manufacturers typically serving all three markets through shared production networks.
Europe Single-Use Packaging Market Insights
Europe represents a mature, regulation-driven single-use packaging market, shaped by comprehensive EU packaging waste directives and industry-wide coalitions targeting specific single-use plastic categories for elimination or replacement. Germany anchors regional demand, home to a large food processing and pharmaceutical manufacturing base and several major packaging companies with deep expertise in recyclable single-use alternatives.
France, Italy, and the United Kingdom contribute meaningful volume as well, each with substantial food service and healthcare manufacturing sectors adapting to tightening EU sustainability requirements. Growing regional emphasis on paper-based and recyclable single-use formats continues shaping product development across the region more directly than in most other global markets.
Market Dynamics
Growth Drivers: Health and safety focus and e-commerce expansion fueling adoption
Rising focus on health and safety, particularly in the food and pharmaceutical industries, is one of the clearest forces behind rising single-use packaging demand, as consumers demand products that are securely sealed and hygienically packaged to maintain product quality and prevent contamination. That fundamental safety requirement is especially crucial in sectors like baby food, pharmaceuticals, and ready-to-eat meals, where hygiene and convenience remain paramount regardless of broader sustainability pressure on the category.
Increasing adoption of e-commerce and home delivery services adds a second major driver, creating a surge in demand for packaging that ensures the safe transport and protection of goods through increasingly complex logistics networks. Growing shipment volumes and rising customer expectations for damage-free deliveries continue reinforcing this demand base independent of traditional retail distribution trends, as single-use formats remain the most cost-effective way to protect goods through a single shipping journey.
Restraints: Environmental regulation and recycling infrastructure gaps limiting broader adoption
Mounting regulatory pressure on single-use plastics remains a genuine restraint, as growing amounts of plastic bags, styrofoam food containers, and disposable coffee cups accumulating in landfills and rivers have significantly impacted the environment and prompted expanding restrictions across multiple jurisdictions. That regulatory pressure adds real compliance complexity for manufacturers serving customers across multiple, inconsistently regulated markets simultaneously.
Uneven recycling infrastructure across different markets adds a further restraint, since many single-use packaging formats, particularly multi-layer plastic-paper composites, require specialized processing that many regions haven't yet built at meaningful scale. That infrastructure gap limits how quickly genuine circularity can improve even as producers invest heavily in recyclable single-material redesigns as an alternative pathway.
Opportunities: Paper-based alternative development and pharmaceutical packaging innovation opening new growth avenues
Paper-based alternative development offers manufacturers a genuine path to capturing premium business from brand owners chasing credible sustainability commitments ahead of tightening single-use plastic restrictions across major markets. Companies that successfully develop paper-based formats matching plastic's functional performance are positioned to capture significant new business as regulatory and consumer pressure on conventional plastic single-use packaging continues building.
Pharmaceutical packaging innovation represents a second significant opportunity, as rising global demand for medical supplies and healthcare services continues expanding the addressable market for sterile, contamination-free single-use formats. Manufacturers that build strong pharmaceutical-grade production capability, backed by biobased film innovation earning independent sustainability certification, are positioned to capture premium pricing from drug manufacturers prioritizing both compliance and environmental credentials.
Recent Developments:
-
July 2024: Thermo Fisher Scientific launched biobased films for single-use bioprocessing containers, earning ISCC Plus certification.
-
February 2025: Huhtamaki officially launched recyclable single coated paper cups crafted for dairy products and yogurt, aligned with high food safety requirements.
-
February 2025: The European Outdoor Group and more than 30 outdoor brands, retailers, and packaging firms released guidelines for eliminating single-use poly bags through the Single Use Plastics Project.
-
February 2025: Clemson FRESH launched a new Compostable Packaging Research and Design Center to accelerate development of sustainable, next-generation single-use packaging.
Single-Use Packaging Market Key Players
-
Amcor plc
-
Berry Global Group, Inc.
-
Sonoco Products Company
-
Huhtamaki Oyj
-
Gerresheimer AG
-
Pactiv Evergreen Inc.
-
Sealed Air Corporation
-
Winpak Ltd.
-
Sabert Corporation
-
Genpak, LLC
-
Dart Container Corporation
-
International Paper Company
-
Smurfit WestRock plc
-
Graphic Packaging International, LLC
-
Novolex Holdings, LLC
-
Crown Holdings, Inc.
-
Constantia Flexibles Group GmbH
-
Mondi Group
-
DS Smith plc
-
Silgan Holdings Inc.
Single-Use Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 44.00 Billion |
| Market Size by 2035 | USD 74.00 Billion |
| CAGR | CAGR of 5.35% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product (Rigid Packaging, Flexible Packaging) • by Material Type (Plastic, Paper & Paperboard, Glass, Others) • by End-User Industry (Food & Beverage, Pharmaceutical & Healthcare, Personal Care, Retail & E-commerce, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Berry Global Group, Inc., Sonoco Products Company, Huhtamaki Oyj, Gerresheimer AG, Pactiv Evergreen Inc., Sealed Air Corporation, Winpak Ltd., Sabert Corporation, Genpak, LLC, Dart Container Corporation, International Paper Company, Smurfit WestRock plc, Graphic Packaging International, LLC, Novolex Holdings, LLC, Crown Holdings, Inc., Constantia Flexibles Group GmbH, Mondi Group, DS Smith plc, Silgan Holdings Inc. |
Frequently Asked Questions
Key players in the Single-Use Packaging Market include Amcor plc, Berry Global Group, Inc., Sonoco Products Company, Huhtamaki Oyj, and Gerresheimer AG, among others.
Key opportunities in the Single-Use Packaging Market include paper-based alternative development matching plastic's functional performance and pharmaceutical packaging innovation with biobased, sustainability-certified single-use formats.
The market is driven by rising focus on health and safety in the food and pharmaceutical industries, combined with increasing adoption of e-commerce and home delivery services.
The Flexible Packaging segment dominated the Single-Use Packaging Market, accounting for approximately 58.60% market share.
The Asia Pacific region dominated the Single-Use Packaging Market in 2025 with approximately 41.83% share, driven by rapid urbanization and expanding food service and e-commerce activity.
