
Glass Packaging Market Report Scope & Overview:
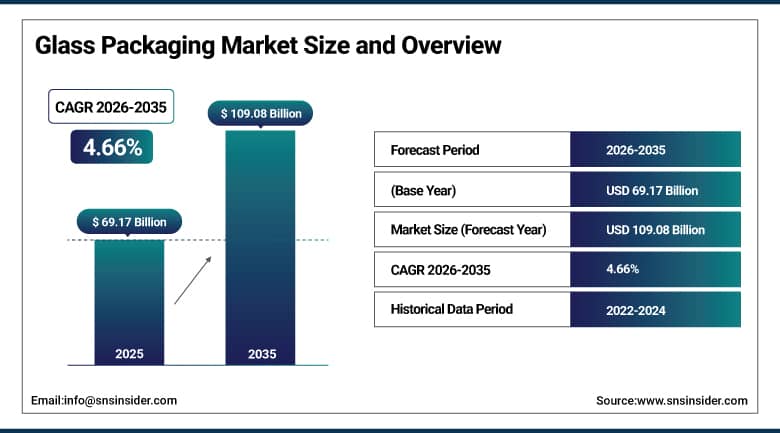
The Glass Packaging Market was valued at USD 69.17 Billion in 2025 and is expected to reach USD 109.08 Billion by 2035, growing at a CAGR of 4.66% from 2026-2035.
Glass has a genuine advantage that plastic and aluminum can't quite match: it can be melted down and remade into a new bottle over and over again without ever losing quality or purity, and that infinite recyclability is exactly what's putting glass back in favor as governments and consumers alike grow more serious about cutting down on plastic waste. Bans on single-use plastics, tightening recycling mandates, and deposit-return schemes across multiple regions are all nudging brand owners back toward a material that, not that long ago, some assumed plastic and aluminum had permanently displaced. Beyond the sustainability story, glass simply performs well as a packaging material, it's chemically inert, keeps flavors and formulations intact, and carries a premium look that brands in spirits, wine, cosmetics, and pharmaceuticals have never really stopped valuing. Pharmaceutical companies in particular continue leaning on glass for liquid medications precisely because of its inertness and chemical resistance, a property no comparably priced alternative fully replicates.
In March 2024, Verallia commissioned the world's first 100% electric furnace for glass container production in Cognac, France, cutting CO2 emissions by 60% compared to conventional gas-fired furnaces. That's a genuinely significant technical milestone, glass furnaces have traditionally run on natural gas at extremely high temperatures, making them one of the harder pieces of the packaging supply chain to decarbonize, and Verallia's success in getting an electric furnace to commercial scale gives the broader industry a real proof point that glassmaking doesn't have to stay tied to fossil fuels indefinitely.
To Get More Information On Glass Packaging Market - Request Free Sample Report
Glass Packaging Market Trends
-
Rising adoption of electric and hybrid glass furnace technology reducing carbon emissions across manufacturing operations.
-
Growing consumer preference for glass packaging as plastic bans and recycling mandates reshape brand packaging choices.
-
Expanding deposit-return system implementation across Europe requiring reusable glass beverage container formats.
-
Increasing demand for lightweight glass technology reducing material use without compromising strength or appeal.
-
Rising consolidation among glass packaging manufacturers through cross-border acquisitions and asset purchases.
-
Growing premiumization trend in spirits and craft beverages sustaining demand for distinctive glass bottle designs.
U.S. Glass Packaging Market Outlook
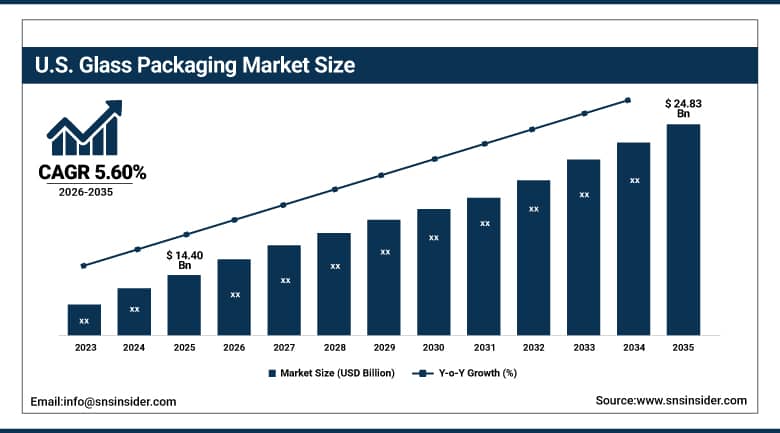
The U.S. Glass Packaging Market was valued at USD 14.40 Billion in 2025 and is expected to reach USD 24.83 Billion by 2035, growing at a CAGR of 5.60% from 2026-2035.
The domestic market keeps benefiting from strong demand across alcoholic beverages, pharmaceuticals, and food, with rising interest in premium spirits, wine, and craft beer continuing to sustain glass bottle usage well above what population growth alone would suggest. Glass's recyclability, chemical inertness, and premium brand perception keep it in favor even as manufacturers face growing competition from alternative packaging materials that are lighter and often cheaper to ship. According to the U.S. Environmental Protection Agency, glass container recycling in the country has held steady around 30 to 31 percent in recent years, with certain states running deposit-return systems achieving meaningfully higher recovery rates, a reminder that infrastructure and policy still matter enormously to how much of the glass Americans use actually gets a second life.
Ardagh Glass Packaging-North America has continued investing across its domestic manufacturing footprint, including securing an 11th consecutive ENERGY STAR building certification for its Fairfield, California distribution center, reflecting sustained attention to energy efficiency across the company's operations. That kind of consistent, year-over-year certification isn't a flashy headline, but it does illustrate how domestic glass manufacturers are treating operational efficiency as an ongoing discipline rather than a one-time initiative, particularly as energy costs and sustainability expectations both continue climbing across the industry.
Glass Packaging Market Segment Analysis
-
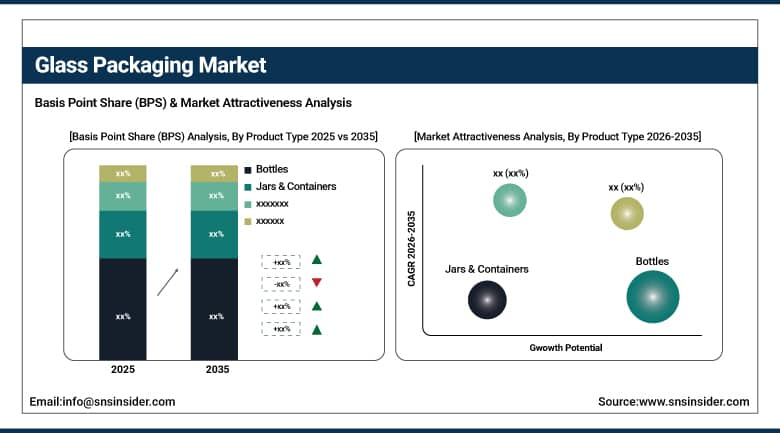
By Product Type, the Bottles segment dominated the Glass Packaging Market with approximately 44.60% share in 2025, while the Jars & Containers segment is the fastest growing with a CAGR of approximately 5.60%.
-
By Material, the Soda-Lime Glass segment dominated the Glass Packaging Market with approximately 62.60% share in 2025, while the Borosilicate Glass segment is the fastest growing with a CAGR of approximately 5.80%.
-
By Color, the Flint/Clear segment dominated the Glass Packaging Market with approximately 48.60% share in 2025, while the Amber segment is the fastest growing with a CAGR of approximately 5.20%.
-
By End-Use Industry, the Food & Beverage segment dominated the Glass Packaging Market with approximately 46.60% share in 2025, while the Pharmaceuticals segment is the fastest growing with a CAGR of approximately 5.80%.
By Product Type, Bottles Dominates the Glass Packaging Market and Jars & Containers Grows Fastest
Bottles segment continues to be the dominating product segment as they serve as the primary format for a wide range of products including alcohol, soft drinks, pharmaceutical products, and personal care products, all of which are capable of being reusable, recyclable and preserving the product's integrity to a much higher degree compared to other formats. Pharmaceutical companies choose glass bottles in order to package liquid pharmaceuticals precisely due to their inertness and chemical resistance, while high-quality spirits and wines are packaged in glass bottles owing to the elegance that glass brings to such products.
Jars and containers segment is experiencing the fastest growth rate, owing to increasing application in food preservation, cosmetic products, and specialty products, where an association between glass and quality and freshness is being created by the consumers. In fact, brands belonging to food products, skincare products and condiments are positioning glass as an indicator of quality and care.
By Material, Soda-Lime Glass Dominates the Glass Packaging Market and Borosilicate Glass Grows Fastest
Soda-lime glass dominates the market thanks to its affordability and versatility, a combination that makes it the practical default choice across the vast majority of food, beverage, and general consumer packaging applications. Manufacturers favor this material because it's relatively inexpensive to produce at scale while still delivering the clarity, strength, and recyclability that most packaging applications require, sustaining its position as the largest material category by a wide margin.
Borosilicate glass is growing fastest, driven almost entirely by its favored status in pharmaceutical applications where its superior thermal shock resistance and chemical stability matter enormously for vaccines, injectable drugs, and biologics. Rising global concern for the safe delivery of these sensitive medical products continues pushing borosilicate glass demand higher, positioning this material for above-market growth as pharmaceutical manufacturing and vaccine distribution infrastructure continue expanding worldwide.
By Color, Flint/Clear Dominates the Glass Packaging Market and Amber Grows Fastest
Flint, or clear, glass holds the largest share of this market because transparency genuinely matters across most packaging applications, brands want consumers to see the product inside, whether that's a premium spirit, a food item, or a cosmetic formulation, and clear glass delivers that visibility while still offering all of glass's other protective properties. This broad applicability across food, beverage, and personal care applications continues to sustain clear glass's position as the default color choice for most packaging programs.
Amber glass is growing fastest, reflecting its essential role in protecting light-sensitive contents, particularly in pharmaceutical and craft beer applications where UV exposure can genuinely degrade product quality over time. As both the pharmaceutical and craft brewing sectors continue expanding, demand for amber glass's protective properties is climbing faster than the broader color category, positioning it for continued above-market growth.
By End-Use Industry, Food & Beverage Dominates the Glass Packaging Market and Pharmaceuticals Grows Fastest
Food and beverage represents the largest end-use industry for glass packaging, anchored by sustained global demand for alcoholic beverages, soft drinks, and packaged foods that continue relying on glass for both practical preservation and brand presentation. The sheer scale of global food and beverage production, combined with glass's enduring popularity in premium beverage categories, continues to sustain this industry's position as the largest source of glass packaging demand.
Pharmaceuticals represent the fastest-growing end-use industry, and the reasons are fairly direct, glass offers protection for liquid dosage forms that few other materials can match, its non-reactive nature keeps drug formulations stable, and increasing regulatory pressure on pharmaceutical companies to shift toward more sustainable packaging continues reinforcing glass's appeal over plastic alternatives. As global healthcare access expands and vaccine and biologic production continues scaling, pharmaceutical demand for glass packaging is climbing faster than any other end-use category.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
Europe |
Germany |
29.60% |
|
North America |
United States |
84.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Glass Packaging Market Insights
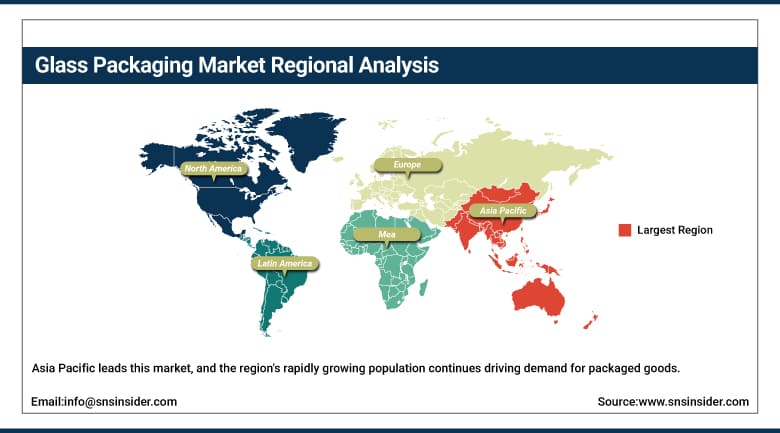
Asia Pacific leads this market, and the region's rapidly growing population continues driving demand for packaged goods, including food, beverages, and pharmaceuticals, at a scale few other regions can match. China's substantial domestic glass manufacturing base and consumer market continue anchoring regional demand, while rising incomes across the broader region keep expanding the addressable market for premium and mid-tier packaged products relying on glass.
India and Southeast Asian markets are contributing significant incremental growth as expanding middle-class populations continue driving demand for packaged food, beverages, and pharmaceuticals. Japan and South Korea round out the region with established, quality-focused consumer markets that favor glass for its premium positioning, reinforcing Asia Pacific's position as the largest regional market through the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Glass Packaging Market Insights
North America is expanding fastest among all regions, driven by high demand across the alcoholic beverage, pharmaceutical, and food sectors. The United States in particular continues seeing strong glass bottle usage on the back of rising demand for premium spirits, wine, and craft beer, categories where consumers consistently associate glass packaging with quality and authenticity in ways that plastic alternatives simply can't match.
Canada and Mexico contribute additional regional demand as their own beverage and food packaging sectors continue growing. Continued domestic investment in lightweight glass technology and deposit-return infrastructure is expected to sustain North America's fastest-growing status through the forecast period, even as the region trails Asia Pacific in absolute market size.
Europe Glass Packaging Market Insights
Europe accounts for a sizable percentage of the global glass packaging market owing to the manufacturing potential of Germany, and its leadership in the sustainable packaging regulation. The mandatory deposit return policy in the EU, which requires that 10 to 15 percent of bottles made of glass must be reusable as of January 2024 in Austria, has been instrumental in ensuring that Europe remains the leader in circular glass packaging systems.
France, Italy, and Spain contribute to regional demand because of the dominance of the wine and spirits industries in those nations, which have been using glass bottles not only to preserve the beverages but also to enhance the prestige of the brands. Manufacturers in the region have been adopting electric and hybrid furnaces in order to meet the emissions standards of the EU and remain technologically advanced despite a slower growth rate compared to other regions.
MEA & Latin America Glass Packaging Market Insights
The Middle East & Africa market remains comparatively modest but is expanding as growing food, beverage, and pharmaceutical sector investment across the United Arab Emirates and Saudi Arabia sustains demand for glass packaging. Regional manufacturing capacity remains limited, with much of the region's glass packaging supply continuing to be imported from European and Asian manufacturers.
Latin America's market is led by Brazil, where a substantial domestic beverage and food production base sustains steady demand for glass packaging. Mexico is contributing growth as regional beverage manufacturing continues to expand, particularly in premium spirits categories increasingly favoring glass bottle presentation. Across the region, adoption remains concentrated among larger manufacturers serving both domestic and export markets.
Market Dynamics
Growth Drivers: Sustainability Regulation and Premium Packaging Demand
Strict regulations being imposed by governments and regulatory authorities across the globe to reduce plastic pollution is the key factor driving the demand for glass packaging. The increasing ban on plastics and the mandate of recycling have made industries prefer environmentally sustainable packaging solutions, such as glass packaging.
An increase in the need for high-quality packaging presentation is another key growth driver for the glass packaging market. Brands from the beverages industry, cosmetics, and specialty foods industry prefer the aesthetics of glass over plastic packaging. Increased consumer demand for safe packaging and the chemical inertness of glass packaging will drive demand within the pharmaceuticals and personal care segments of the market.
Restraints: Weight-Related Shipping Costs and Alternative Packaging Competition
Cost associated with shipping weights is a significant restraint in the market because glass being heavier than plastic and aluminum still results in increased costs of transportation and environmental problems that certain brands cannot easily justify, especially for less profitable categories of products that have high cost of logistics.
The emergence of competition from other materials used in packaging is another important restraint. The increasing usage of metal, plastic, wood, and paper packaging continues causing problems for glass packaging in particular categories where weight and cost become more important than glass’s high price and sustainable features. Glass manufacturers must continue innovating in the area of lightweight technologies to compete in costs with these materials.
Opportunities: Electric Furnace Technology and Lightweight Glass Innovation
Continued development of electric and hybrid furnace technology represents a substantial opportunity, as manufacturers that can successfully decarbonize glass production at commercial scale are positioned to capture demand from brand owners increasingly scrutinizing their supply chain's carbon footprint. Manufacturers demonstrating genuine emissions reductions through electric furnace adoption are increasingly favored by sustainability-focused customers seeking to reduce their own reported carbon impact.
The ongoing progress in the development of light-weight glass materials is another promising direction for development, since companies which will be able to save on material usage for containers while still preserving their strength and aesthetic value are likely to overcome one of the biggest disadvantages of glass – its heavier weight compared to plastic and aluminum. Companies which will be able to supply light-weight glass materials and at the same time preserve their premium look are very likely to succeed.
Recent Developments:
-
In January 2024, Austria implemented an EU-mandated deposit-return system requiring 10 to 15% of beverage containers, including glass, to be reusable with full deposit returns.
-
In February 2025, Mineragua introduced a new 12-pack glass bottle set for its sparkling water line.
Glass Packaging Market Key Players
-
Owens-Illinois, Inc. (O-I Glass)
-
Ardagh Group S.A.
-
Verallia SA
-
Gerresheimer AG
-
Vitro Packaging
-
Bormioli Rocco S.p.A.
-
Vetropack Holding Ltd.
-
Amcor plc
-
Piramal Glass Pvt. Ltd.
-
Toyo Seikan Group Holdings Ltd.
-
B.A. Glass B.V.
-
Nihon Yamamura Glass Co., Ltd.
-
Heinz-Glas GmbH & Co. KGaA
-
AptarGroup, Inc.
-
Stölzle Glass Group
-
Wiegand-Glas GmbH
-
Vidrala S.A.
-
Beatson Clark Ltd.
-
Anchor Glass Container Corporation
-
KOA Glass Co., Ltd.
Glass Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 69.17 Billion |
| Market Size by 2035 | USD 109.08 Billion |
| CAGR | CAGR of 4.66% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Bottles, Jars & Containers, Vials & Ampoules, Cartridges & Syringes) • By Material (Soda-Lime Glass, Borosilicate Glass, De-Alkalized Soda-Lime Glass) • By Color (Flint/Clear, Amber, Green, Others) • By End-Use Industry (Food & Beverage, Pharmaceuticals, Cosmetics & Personal Care, Household Chemicals) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Owens-Illinois, Inc. (O-I Glass), Ardagh Group S.A., Verallia SA, Gerresheimer AG, Vitro Packaging, Bormioli Rocco S.p.A., Vetropack Holding Ltd., Amcor plc, Piramal Glass Pvt. Ltd., Toyo Seikan Group Holdings Ltd., B.A. Glass B.V., Nihon Yamamura Glass Co., Ltd., Heinz-Glas GmbH & Co. KGaA, AptarGroup, Inc., Stölzle Glass Group, Wiegand-Glas GmbH, Vidrala S.A., Beatson Clark Ltd., Anchor Glass Container Corporation, KOA Glass Co., Ltd. |
Frequently Asked Questions
Key players include Owens-Illinois, Inc., Ardagh Group S.A., Verallia SA, Gerresheimer AG, Vitro Packaging, Vetropack Holding Ltd., and Bormioli Rocco S.p.A., among other global glass packaging manufacturers.
Continued development of electric and hybrid furnace technology and continued advancement of lightweight glass innovation represent the biggest opportunities for glass packaging manufacturers.
Growth is driven mainly by government and regulatory efforts to curb plastic pollution, combined with rising demand for premium packaging presentation across spirits, cosmetics, and specialty foods.
By Product Type, Bottles held approximately 44.60% share in 2025, reflecting their standard status across alcoholic beverages, soft drinks, pharmaceuticals, and personal care products.
Asia Pacific led with approximately 38.60% share in 2025, driven by the region's rapidly growing population and expanding demand for packaged goods.
