
Quantum Chip Market Report Scope & Overview:
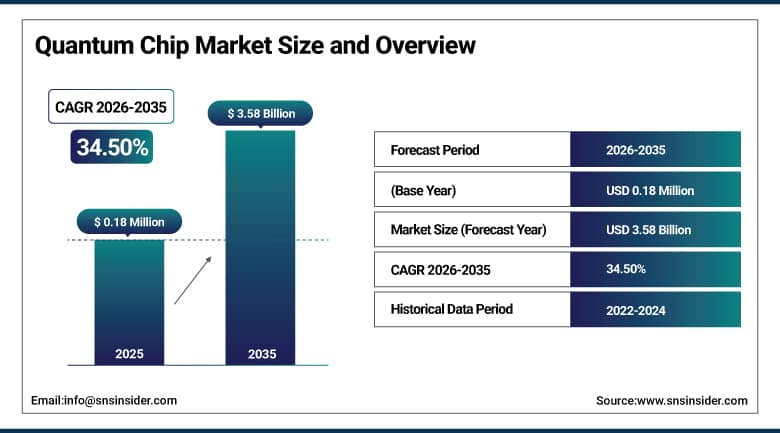
The Quantum Chip Market was valued at USD 0.18 Million in 2025 and is expected to reach USD 3.58 Billion by 2035, growing at a CAGR of 34.50% from 2026-2035.
The Quantum Chip Market covers the processors and supporting silicon that hold and manipulate qubits, including superconducting circuits, trapped-ion traps, photonic chips, neutral-atom arrays and silicon spin devices, together with the cryogenic and control electronics that make them usable. Revenue today comes from chip and system sales to research labs, governments, cloud providers and early enterprise users, and from access through cloud platforms. The market is small but expanding quickly as vendors move from tens to hundreds of qubits, work toward error-corrected machines, and build dedicated fabrication lines. Public funding, strategic investment and new listings are supplying capital, while error rates, scaling and cost remain the main technical hurdles.
⮞Quantum chips are getting their own foundry. In late May 2026, IBM announced plans to invest more than USD 10 Billion over five years in quantum computing, targeting a fault-tolerant quantum computer by 2029. The plan includes Anderon, a standalone pure-play quantum chip foundry in Albany, New York, running on a 300mm line, backed by a USD 1 Billion CHIPS letter of intent matched by USD 1 Billion from IBM. The move treats quantum devices as a manufacturing category rather than a laboratory product, and gives outside developers a path to volume fabrication.
To Get More Information On Quantum Chip Market - Request Free Sample Report
Quantum Chip Market Trends:
-
Shift from laboratory prototypes to dedicated 300mm quantum chip foundries
-
Progress toward error-corrected logical qubits rather than raw qubit counts
-
Growth of photonic and neutral-atom chips that operate with simpler cooling
-
Government co-investment through programs such as the CHIPS initiative
-
Public listings and acquisitions consolidating the vendor base
-
Integration of quantum processors with classical GPUs and cloud platforms
U.S. Quantum Chip Market Outlook:
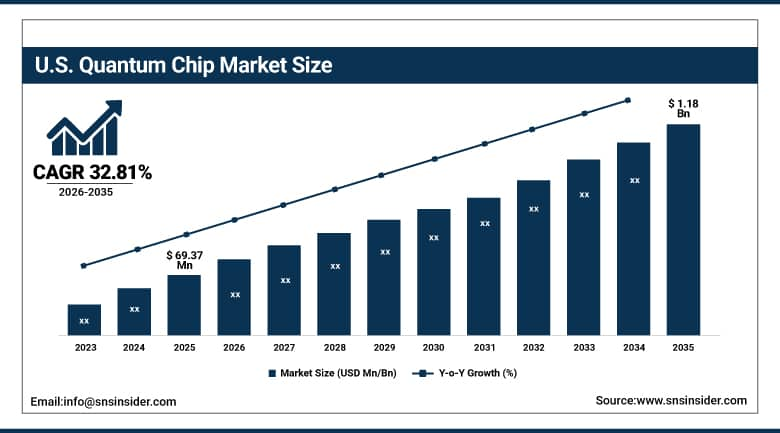
The U.S. Quantum Chip Market was valued at USD 69.37 Million in 2025 and is expected to reach USD 1.18 Billion by 2035, growing at a CAGR of 32.81% from 2026-2035.
The U.S. Quantum Chip Market is the largest national market in the world, supported by IBM, Google, Microsoft, IonQ, Rigetti, D-Wave and Quantinuum, along with university labs, national laboratories and a growing group of foundry partners. Federal programs, including the National Quantum Initiative, Department of Energy centers and CHIPS funding, provide a steady base of demand and R&D money. Defense and intelligence agencies buy for sensing and cryptography research, while banks and pharmaceutical firms run pilots through cloud access. Export controls and a shortage of cryogenic and fabrication capacity limit speed, but public funding and private capital markets keep investment high.
⮞Washington is paying for manufacturing. On September 8, 2026, Quantinuum finalized a definitive agreement for USD 100 Million in CHIPS research and development funding to accelerate trapped-ion chip manufacturing. GlobalFoundries fabricates the ion traps on 300mm wafers, and Monarch Quantum builds photonic light engines, as part of a USD 2 Billion federal initiative. The Colorado and Minnesota based company, which recently listed publicly with USD 1.7 Billion in gross proceeds, reported Q2 2026 revenue of USD 8 Million and has a partnership with Oracle Cloud.
Quantum Chip Market Segment Analysis:
-
By Type, the Superconducting segment dominated the Quantum Chip Market with approximately 46.50% share in 2025, while the Photonic segment is the fastest growing with a CAGR of approximately 36.80%.
-
By Component, the Quantum Processors segment dominated the Quantum Chip Market with approximately 38.90% share in 2025, while the Cryogenics and Control Systems segment is the fastest growing with a CAGR of approximately 34.50%.
-
By Application, the Quantum Computing segment dominated the Quantum Chip Market with approximately 41.20% share in 2025, while the Quantum Cryptography segment is the fastest growing with a CAGR of approximately 35.60%.
-
By End-User, the BFSI segment dominated the Quantum Chip Market with approximately 28.70% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 36.40%.
-
By Qubit Count, the 51-200 Qubits segment dominated the Quantum Chip Market with approximately 38.60% share in 2025, while the Above 1,000 Qubits segment is the fastest growing with a CAGR of approximately 52.40%.
By Type, Superconducting Dominates the Quantum Chip Market and Photonic Grows Fastest
Superconducting chips lead because they are the most mature architecture, with fast gate speeds, compatibility with established semiconductor lithography and a large installed base on cloud platforms. IBM and Google have scaled processors steadily, and Rigetti and IQM sell systems to national laboratories and universities. The ecosystem of control electronics, software and trained engineers is deepest here, which lowers risk for buyers. Foundry efforts such as IBM's planned Anderon line extend this advantage by moving fabrication toward standard 300mm tools and repeatable yields.
Photonic chips are growing fastest because they use light, can operate at or near room temperature for much of the system, and map onto telecom-grade manufacturing. PsiQuantum, Xanadu and Quantinuum's photonic partners are building waveguide and detector chips on commercial foundry lines. Photonic designs also suit networking and cryptography, where photons are the natural carrier. Challenges include photon loss and the large number of components for fault tolerance, but heavy funding and foundry access support rapid growth from a small base.
By Component, Quantum Processors Dominates the Quantum Chip Market and Cryogenics and Control Systems Grows Fastest
Quantum processors lead because the chip itself is the core product and carries the highest value in every system sold. Superconducting, trapped-ion, neutral-atom and photonic processors are priced as strategic assets, and buyers pay for qubit quality, connectivity and error rates. Vendors increasingly sell processors as part of full systems or cloud access, but processor design remains the main source of differentiation and intellectual property, and it receives the largest share of research budgets and venture funding.
Cryogenics and control systems are growing fastest because every extra qubit needs more wiring, amplification and cooling. Dilution refrigerators, cryo-CMOS controllers and microwave electronics are scaling alongside processors, and error correction requires real-time decoding hardware. Suppliers are developing denser cabling and integrated control chips to avoid a wiring bottleneck. As systems move from hundreds to thousands of qubits, this supporting hardware becomes a larger part of each purchase and a focus for specialist suppliers and chip designers.
By Application, Quantum Computing Dominates the Quantum Chip Market and Quantum Cryptography Grows Fastest
Quantum computing leads because most chips are built to run algorithms, either on gate-based processors or on annealing systems such as D-Wave's. Customers include government laboratories, universities, cloud providers and enterprise research teams testing optimization, chemistry and materials problems. Revenue comes from system sales and cloud access, and recent quarterly results from IonQ, Rigetti and D-Wave show rising but still modest sales. Advances in error correction are widening the set of problems that can be explored.
Quantum cryptography is growing fastest because governments and telecom operators are preparing for threats to current encryption and are testing quantum key distribution and quantum random number generation. These applications use photonic and specialized chips that are simpler than full computers and can be deployed sooner. Satellite links, financial networks and government communications are early adopters. Standards work and national programs in the United States, Europe, China and India are creating funded demand for secure communication hardware over the forecast period.
By End-User, BFSI Dominates the Quantum Chip Market and Healthcare Grows Fastest
BFSI leads because banks, insurers and asset managers have the capital and the optimization, risk and portfolio problems that early quantum systems target. Financial firms run pilots with cloud providers, sign research agreements with hardware vendors and invest in post-quantum security. Although most work is experimental, budgets are dedicated and multi-year, and firms want early access to build skills and secure intellectual property before commercial advantage appears.
Healthcare is growing fastest as pharmaceutical and life science companies pursue molecular simulation, drug discovery and protein modelling, where quantum chips could outperform classical methods. Partnerships between drug developers and hardware makers are increasing, and hospitals and research institutes explore imaging and genomics applications. Adoption starts from a smaller base and depends on error-corrected hardware, but the potential value of faster discovery is attracting investment and supporting the highest growth rate among end-users.
By Qubit Count, 51-200 Qubits Dominates the Quantum Chip Market and Above 1,000 Qubits Grows Fastest
Chips with 51 to 200 qubits lead because they match the systems commercially available today and offer enough scale for useful research while keeping error rates manageable. Most cloud-accessible machines from IBM, IonQ, Rigetti, IQM and Quantinuum fall in or near this range, and customers value fidelity over raw count. These devices are the workhorses for algorithm development, benchmarking and early commercial pilots, so they account for the largest revenue.
Chips above 1,000 qubits are growing fastest from a very small base as roadmaps move toward error-corrected machines that need thousands of physical qubits per logical qubit. Neutral-atom arrays from Atom Computing, Pasqal and Infleqtion, along with superconducting and photonic roadmaps, target this scale. Fabrication on 300mm lines, modular designs that link chips, and better control electronics support the shift. Sales will be few but high in value, which produces rapid percentage growth.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
86.40 |
|
Asia Pacific |
China |
34.80 |
|
Europe |
United Kingdom |
25.60 |
|
Middle East & Africa |
Israel |
38.40 |
|
Latin America |
Brazil |
52.30 |
North America Quantum Chip Market Insights
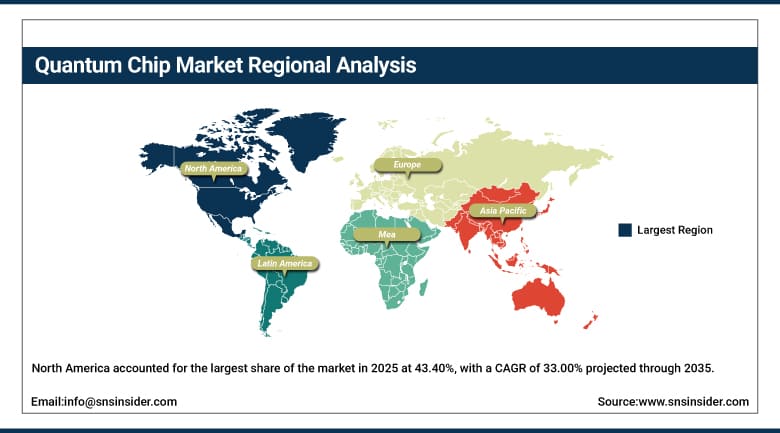
North America accounted for the largest share of the market in 2025 at 43.40%, with a CAGR of 33.00% projected through 2035. The United States holds most regional value through IBM, Google, Microsoft, IonQ, Rigetti, D-Wave, Quantinuum and PsiQuantum, as well as federal laboratories and universities. Canada adds Xanadu and a strong research base, and public programs fund both research and fabrication.
Federal co-investment, such as the CHIPS agreements with IBM's Anderon and Quantinuum, along with the IonQ acquisition of SkyWater, is building local fabrication capacity. Capital markets are open to quantum companies, supporting listings and large raises. Growth is slower than in Asia Pacific because the base is already large, but the depth of talent and funding keeps the region dominant.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Quantum Chip Market Insights
Asia Pacific held 27.90% of the market in 2025 and is the fastest-growing region, advancing at a CAGR of 37.60% during 2026-2035. China, Japan, South Korea, India and Australia lead through national quantum programs, large research institutes and growing hardware industries. Fujitsu and RIKEN in Japan operate superconducting systems, while Chinese teams pursue superconducting and photonic processors.
Governments fund national missions and local supply chains, and local telecom and finance firms test quantum security. India's national quantum mission and Australia's silicon and photonic start-ups add momentum. Export controls and reliance on imported cryogenic equipment restrain some projects, yet strong public budgets and manufacturing depth support the fastest regional growth.
Europe Quantum Chip Market Insights
Europe held 22.80% of the market in 2025 and is growing at a CAGR of 33.10% through 2035. The United Kingdom, Germany, France, Finland and the Netherlands lead, with companies such as IQM, Pasqal, Alice & Bob, Oxford Quantum Circuits and Quantum Motion. IQM's Nasdaq listing in July 2026, with 26 systems sold, shows rising commercial scale.
The EU Quantum Flagship, national strategies and pilot production lines fund chip development, and European supercomputing centers install quantum systems beside classical machines. Fragmented funding and fewer late-stage investors compared with the United States restrain scale-up, but strong research institutions and public procurement sustain steady growth.
MEA & Latin America Quantum Chip Market Insights
The Middle East and Africa held 3.90% of the market and is growing at a CAGR of 35.00%. Israel leads through quantum start-ups and defense research, while the United Arab Emirates and Saudi Arabia fund national programs and partnerships with global vendors. Gulf governments see quantum as part of economic diversification and are buying systems and sponsoring research centers.
Latin America held 2.00% of the market and is growing at a CAGR of 31.00%. Brazil leads through university research and national initiatives, with Mexico, Chile and Argentina adding smaller programs. Limited funding, import dependence and a thin talent pipeline restrain adoption, but cloud access and international research partnerships allow institutions to take part without owning hardware.
Market Dynamics:
Growth Drivers: Public Funding, Foundry Scale-Up and Progress in Error Correction
Public funding is a major driver. Governments in the United States, Europe and Asia are financing national quantum programs, research centers and fabrication lines, including USD 100 Million for Quantinuum and a USD 1 Billion letter of intent for IBM's Anderon foundry. Defense, energy and science agencies provide steady demand, which reduces risk for suppliers and lets them plan multi-year chip roadmaps.
Foundry scale-up and error-correction progress add momentum. Moving quantum chips onto 300mm lines improves yield, cost and repeatability, while better logical qubits move machines toward useful workloads. Capital markets have responded: Quantinuum raised USD 1.7 Billion, IonQ completed its USD 1.8 Billion acquisition of SkyWater, and IQM listed on Nasdaq, giving companies the funds to expand production.
Restraints: High Error Rates, Cryogenic Complexity and Limited Commercial Revenue
High error rates remain the central restraint. Today's physical qubits make mistakes often, and useful algorithms need thousands of physical qubits per logical qubit. Until error correction is demonstrated at scale, buyers treat purchases as research investments, which limits order sizes and extends sales cycles for chip makers.
Cryogenic complexity and thin revenue add pressure. Many chips need dilution refrigerators and dense wiring that are costly and hard to scale, and quarterly sales remain small, for example D-Wave's USD 3.1 Million in Q2 2026 against a USD 48 Million net loss. Companies depend on external capital, which exposes them to market swings and delays.
Opportunities: Photonic and Neutral-Atom Chips, Quantum Security and Hybrid Computing
Photonic and neutral-atom chips offer a major opportunity because they reduce cooling needs and can use existing semiconductor or optical manufacturing. Vendors such as PsiQuantum, Xanadu, Atom Computing and Pasqal are building toward large arrays, and foundries like GlobalFoundries and SkyWater now serve quantum customers, allowing new entrants to reach production faster.
Quantum security and hybrid computing provide further opportunities. Demand for quantum key distribution and random number chips is rising as governments prepare for new threats to encryption, and quantum processors paired with GPUs and cloud platforms, such as Quantinuum's Oracle Cloud partnership, let customers try applications without owning hardware. These routes create revenue before full fault tolerance.
Recent Developments:
-
On July 31, 2026, IonQ closed its USD 1.8 Billion acquisition of SkyWater Technology, adding a U.S. semiconductor foundry to its trapped-ion business, and reported Q2 2026 revenue of USD 80.1 Million with 2026 guidance of USD 280 Million to USD 290 Million.
-
On July 2, 2026, IQM Quantum Computers listed on Nasdaq, having sold 26 systems, and reported first-half 2026 revenue of EUR 8.9 Million.
-
In 2026, Rigetti signed a letter of intent with the U.S. Department of Commerce for up to USD 100 Million over three years to support its chip manufacturing, and reported Q2 2026 revenue of USD 5.1 Million.
-
In Q2 2026, D-Wave Quantum reported revenue of USD 3.1 Million and a net loss of USD 48 Million, reflecting continued investment in annealing and gate-model chip development.
Quantum Chip Market Key Players:
-
International Business Machines Corporation (IBM)
-
Google LLC (Alphabet Inc.)
-
Microsoft Corporation
-
Intel Corporation
-
IonQ, Inc.
-
Rigetti Computing, Inc.
-
D-Wave Quantum Inc.
-
Quantinuum Ltd.
-
PsiQuantum Corp.
-
Xanadu Quantum Technologies Limited
-
Pasqal SAS
-
Atom Computing, Inc.
-
Alice & Bob
-
Fujitsu Limited
-
IQM Quantum Computers
-
Infleqtion, Inc.
-
Oxford Quantum Circuits
-
Quantum Motion Technologies
-
Anderon (IBM)
-
GlobalFoundries Inc.
-
SkyWater Technology, Inc.
-
Amazon Web Services, Inc. (AWS)
Quantum Chip Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.18 Million |
| Market Size by 2035 | USD 3.58 Billion |
| CAGR | CAGR of 34.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Superconducting, Trapped Ion, Photonic, Neutral Atom, Silicon Spin, Others) • By Component (Quantum Processors, Cryogenics and Control Systems, Quantum Memory and Interconnects, Others) • By Application (Quantum Computing, Quantum Cryptography, Quantum Sensing, Quantum Simulation, Others) • By End-User (BFSI, Healthcare, Aerospace and Defense, Government and Research, Others) • By Qubit Count (Up to 50 Qubits, 51-200 Qubits, 201-1,000 Qubits, Above 1,000 Qubits) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | International Business Machines Corporation (IBM), Google LLC (Alphabet Inc.), Microsoft Corporation, Intel Corporation, IonQ, Inc., Rigetti Computing, Inc., D-Wave Quantum Inc., Quantinuum Ltd., PsiQuantum Corp., Xanadu Quantum Technologies Limited, Pasqal SAS, Atom Computing, Inc., Alice & Bob, Fujitsu Limited, IQM Quantum Computers, Infleqtion, Inc., Oxford Quantum Circuits, Quantum Motion Technologies, Anderon (IBM), GlobalFoundries Inc., SkyWater Technology, Inc., Amazon Web Services, Inc. (AWS) |

Frequently Asked Questions
Key players include IBM, Google, Microsoft, Intel, IonQ, Rigetti, D-Wave, Quantinuum, PsiQuantum, Xanadu, Pasqal, Atom Computing, Alice & Bob, Fujitsu, IQM, Infleqtion, GlobalFoundries and SkyWater.
Key opportunities include photonic and neutral-atom chips that need less cooling, quantum security and key distribution hardware, and hybrid quantum-classical computing delivered through cloud platforms.
The major growth factor is public and private funding, including CHIPS co-investment, national quantum programs and capital market raises, which is financing dedicated quantum fabrication and error-correction research.
By Type, the Superconducting segment dominated the market with approximately 46.50% share in 2025, owing to its maturity, fast gate speeds and compatibility with semiconductor fabrication.
North America dominated the market with a share of 43.40% in 2025, supported by leading vendors, federal funding and deep capital markets in the United States.
