
Reinsurance Market Report Scope & Overview:
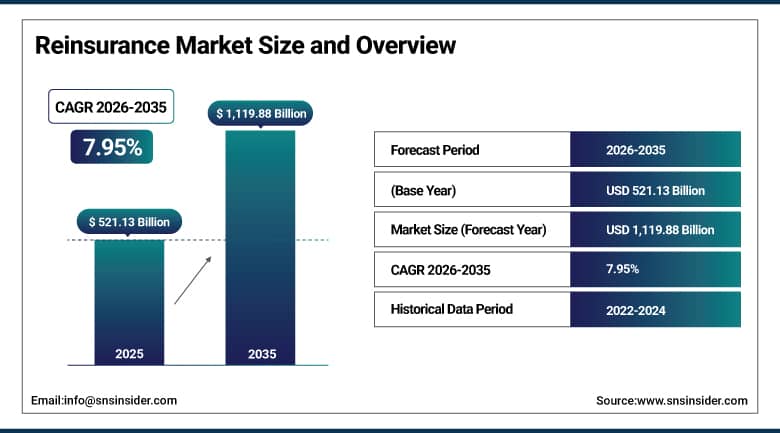
The Reinsurance Market was valued at USD 521.13 Billion in 2025 and is expected to reach USD 1,119.88 Billion by 2035, growing at a CAGR of 7.95% from 2026-2035.
The Reinsurance Market comprises the premiums that primary insurers cede to reinsurers and alternative capital providers to protect their balance sheets against large losses, volatile claims and regulatory capital strain. Demand will increase with the value of the insured property, the incidence of weather catastrophes, and expansion of the life and health books in developing countries. The amount of capital in the industry has hit an all-time high in 2026, buoyed by strong results from underwriting and investments in catastrophe bonds and other insurance-linked securities. Pricing has started to ease from several years of tightening, creating pressure on competition in terms and conditions, as consolidation in the form of mergers continues in carriers.
⮞In August 2026, the Swiss Re Institute estimated global insured natural catastrophe losses at USD 42 billion in the first half of 2026, the lowest first-half total since 2020 and 16% below the ten-year average. Benign loss experience supported record reinsurer earnings and capital.
To Get More Information On Reinsurance Market - Request Free Sample Report
Reinsurance Market Trends
-
Catastrophe bond issuance reached record levels in the first half of 2026.
-
Property catastrophe pricing is softening after several years of hardening.
-
Reinsurers are expanding in specialty and cyber lines to diversify earnings.
-
Mergers among Lloyd's and Bermuda carriers are consolidating capacity.
-
Climate models and satellite data are being used more widely to price weather risk.
U.S. Reinsurance Market Outlook
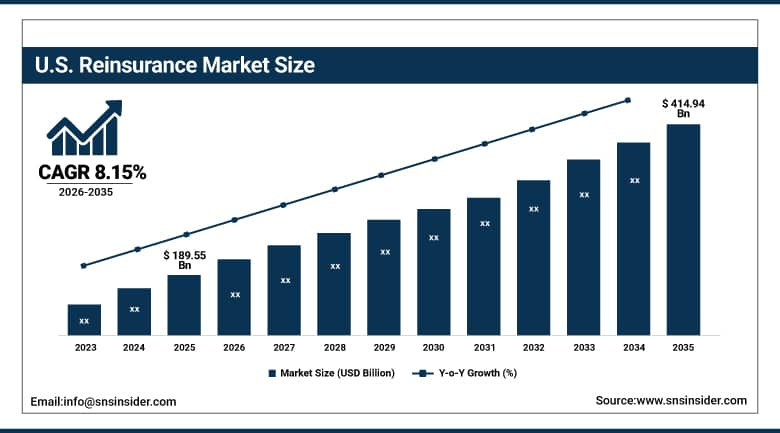
The U.S. Reinsurance Market was valued at USD 189.55 Billion in 2025 and is expected to reach USD 414.94 Billion by 2035, growing at a CAGR of 8.15% from 2026-2035.
The U.S. Reinsurance Market is the world's largest national source of ceded premium, driven by exposure to hurricanes, severe convective storms, wildfires and earthquakes, and by a large casualty sector affected by social inflation. State-backed insurers in Florida and Texas, along with regional carriers, buy substantial catastrophe cover each year, and many place part of it through catastrophe bonds. Domestic reinsurers compete with Bermuda, London and European carriers that write a large share of U.S. risk. Primary insurers also use reinsurance to manage rating agency capital and growth in specialty lines, and cyber and casualty buyers are lifting limits. Expansion is steady, supported by rising property values and higher limits purchased.
⮞In June 2026, Florida Citizens Property Insurance Corporation placed about USD 2.82 billion of risk transfer, comprising USD 2.13 billion of catastrophe bonds and USD 691 million of traditional reinsurance, at prices roughly 30% below comparable 2025 coverage. The program shows both the size of public sector buying and the softening of rates.
Reinsurance Market Segment Analysis
-
By Type, the Treaty segment dominated the Reinsurance Market with approximately 61.55% share in 2025, and is also the fastest growing with a CAGR of approximately 8.94%.
-
By Product, the Non-Life segment dominated the Reinsurance Market with approximately 59.55% share in 2025, while the Life and Health segment is the fastest growing with a CAGR of approximately 8.76%.
-
By Line of Business, the Property segment dominated the Reinsurance Market with approximately 40.50% share in 2025, while the Specialty segment is the fastest growing with a CAGR of approximately 8.91%.
-
By Distribution Channel, the Broker segment dominated the Reinsurance Market with approximately 60.70% share in 2025, while the Direct segment is the fastest growing with a CAGR of approximately 8.63%.
By Type, Treaty Dominates the Reinsurance Market and Also Grows Fastest
Treaty arrangements account for most ceded premium because insurers prefer to transfer whole portfolios under standing contracts rather than negotiate cover risk by risk. A quota share or excess of loss treaty gives the cedent predictable capital relief, lower administration costs and stable access to capacity across renewal cycles. Reinsurers favor the form since it delivers diversified books and long relationships with cedents. Large global programs for property catastrophe, casualty and life blocks are almost entirely treaty based, and renewals on 1 January, 1 April, 1 June and 1 July set pricing for the broader market.
The segment is also the quickest to expand as growing insurers in Asia, Latin America and the Middle East adopt treaty protection to support premium growth and meet solvency regimes. Insurance-linked securities and catastrophe bonds follow treaty-like structures and add capacity, while multi-year and aggregate covers are gaining use. Facultative reinsurance remains important for large single risks such as industrial plants, energy assets and infrastructure projects, where underwriters assess each exposure individually and charge for specialist expertise, which supports margins on complex placements and keeps the segment active.
⮞In May 2026, Artemis data showed record monthly catastrophe bond issuance of about USD 6.93 billion, taking first-half 2026 issuance to roughly USD 17.98 billion across 83 deals and the outstanding market to a record USD 65.6 billion. The figures show alternative capital taking a larger role beside traditional treaty reinsurers.
By Product, Non-Life Dominates the Reinsurance Market and Life and Health Grows Fastest
Non-life lines supply the largest portion of premium since property catastrophe, casualty, marine, aviation and specialty risks create the bulk of volatility that primary insurers need to lay off. Climate-related events, rising construction costs and inflation in liability claims keep demand for protection high, and cedents buy more limit as exposures grow. Reinsurers price this business with sophisticated models, and results swing with catastrophe experience, yet strong underwriting margins in recent years have attracted new capital and encouraged established firms to expand their property and casualty books, while smaller specialists also entered the field.
Life and health reinsurance is growing at a faster rate as insurers in Asia and other emerging markets transfer longevity, mortality and morbidity risk, and as pension and annuity buy-outs expand in the United Kingdom and North America. Reinsurers provide capital relief, product design and underwriting support, and asset-intensive deals allow insurers to move blocks of business off balance sheet. Demand for medical and critical illness cover is rising with aging populations, and specialist firms are growing in the longevity and funded reinsurance segments, often backed by private capital from asset managers.
By Line of Business, Property Dominates the Reinsurance Market and Specialty Grows Fastest
Property business leads because natural catastrophe exposure is concentrated and insurers face the largest single-event losses in this class. Hurricanes, earthquakes, floods, wildfires and severe convective storms drive purchasing of catastrophe excess of loss and per-risk programs, and regulators and rating agencies expect carriers to hold protection against realistic disaster scenarios. Property cat pricing was strong through the recent hard market, and capital from pension funds and other investors entered through bonds and collateralized vehicles, deepening the supply of protection and giving buyers a wider choice of structures, from indemnity to parametric triggers.
Specialty lines are expanding fastest as new risks emerge and insurers seek expertise in areas such as cyber, political violence, marine, aviation, space, energy and credit. Reinsurers able to build knowledge in these classes earn margins less correlated with weather, which diversifies earnings. Casualty reinsurance remains a major line, but reserve concerns linked to social inflation have made underwriters cautious and led to tighter terms. Growth in digital exposure and complex supply chains continues to create demand for specialty capacity, and underwriters are building teams to evaluate emerging threats such as ransomware aggregation and space debris.
By Distribution Channel, Broker Dominates the Reinsurance Market and Direct Grows Fastest
Brokers place the majority of reinsurance business because they provide market access, risk analytics, structuring skills and negotiation power on behalf of cedents. Large brokers maintain relationships with hundreds of reinsurers and alternative capital managers, produce catastrophe modeling and advise on capital strategy, and they are central to catastrophe bond placement. Cedents value independent advice at renewal, and reinsurers value the consistent flow of well-prepared submissions. The channel is also a source of data and analytics tools that shape pricing.
Direct placement is gaining share as large insurers with sophisticated risk functions deal directly with reinsurers to lower brokerage costs and build closer partnerships. Long-term strategic relationships, multi-year quota shares and joint ventures between primary carriers and reinsurers encourage direct dealing. Digital platforms are also shortening the process for smaller treaties, and some reinsurers have built direct capabilities for regional and mid-sized cedents. Even so, complex programs continue to rely on brokers for structuring and market reach, and brokers have responded by launching their own capital and data services.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
91.00% |
|
Europe |
Germany |
26.00% |
|
Asia Pacific |
China |
33.00% |
|
Latin America |
Brazil |
38.40% |
|
Middle East and Africa |
United Arab Emirates |
28.50% |
North America Reinsurance Market Insights
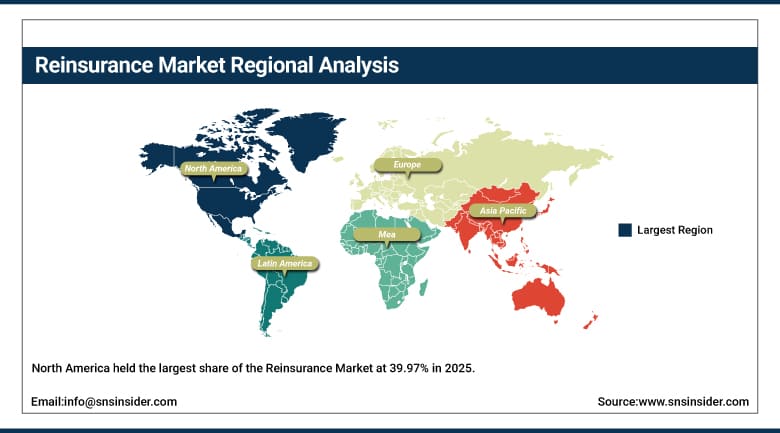
North America held the largest share of the Reinsurance Market at 39.97% in 2025, with the United States generating the bulk of ceded premium and Canada contributing a smaller, stable share. The region faces the world's greatest concentration of insured catastrophe exposure, including coastal hurricane zones, tornado corridors, wildfire areas and seismic regions, which sustains large annual purchases. Domestic carriers, Bermuda-based reinsurers and Lloyd's syndicates all compete for this business, and insurance-linked securities have become a core part of the capital supply.
State-sponsored programs are major buyers. Texas and Florida windstorm and property insurers return to the market every year with large combinations of traditional cover and catastrophe bonds, and their results influence global pricing. Casualty lines face reserve pressure from legal system abuse, which keeps underwriters selective and supports demand for aggregate and loss portfolio covers. Regulators supervise reinsurance credit and collateral, and growth stays moderate, backed by rising insured values and higher retention and limit purchases. Insurers are also paying closer attention to wildfire modeling and to secondary perils, such as hail and flood, that have driven many recent losses.
⮞In June 2026, the Texas Windstorm Insurance Association completed a 2026-27 reinsurance program of USD 2.28 billion, including the USD 750 million Alamo Re 2026-1 catastrophe bond, with rate on line falling to 9.21% from 10.2%. The result shows falling prices for top-tier catastrophe protection.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Reinsurance Market Insights
Europe is home to the largest traditional reinsurers, notably in Germany, Switzerland, France and the United Kingdom, and it combines substantial domestic demand with the global underwriting reach of firms based in Munich, Zurich, Paris and London. Insurers face windstorm, flood and hail exposure and operate under the Solvency II regime, which rewards risk transfer through capital relief. The Lloyd's market in London provides specialty capacity for aviation, marine, energy and political risks, and attracts business from around the world.
Reinsurers in the region reported strong results in the first half of 2026, but they also reported falling premium volume as prices eased and they chose to cut back on less attractive treaties, preferring margin over market share. Consolidation continues, as shown by large acquisitions of Lloyd's carriers. Regulators are reviewing Solvency II and considering stronger supervision of cross-border reinsurance, particularly for life blocks transferred to offshore entities. Growth is steady, supported by life and longevity transactions and specialty demand, although earnings can swing with large single-year losses, and the supervisory agenda on climate stress testing is widening.
⮞In September 2026, Lloyd's reported first-half gross written premium up 6.9% and a combined ratio of 90.8%, compared with 92.5% a year earlier. The results show healthy underwriting margins in the London specialty market.
Asia Pacific Reinsurance Market Insights
Asia Pacific is the fastest growing region, with a projected CAGR of 9.76% from 2026-2035, as rising incomes, expanding insurance penetration and exposure to typhoons, earthquakes and floods lift demand for risk transfer. China, Japan, India, South Korea, Australia and Southeast Asian countries all contribute, and regional reinsurers such as China Re, Korean Re and GIC Re compete alongside global groups, and local insurers often cede through regional hubs. Catastrophe-prone economies are looking for protection from large events, and governments encourage insurers to build resilience.
Regulators are modernizing solvency rules, which increases the use of reinsurance for capital management and supports demand from mid-sized insurers. Hubs in Singapore, Hong Kong and Shanghai attract regional offices of global reinsurers, and Japanese groups are active acquirers abroad. Life and health demand is growing with aging populations and rising middle classes, and bancassurance channels are expanding. Barriers include complex local regulation and requirements for local retention, but the pace of premium growth positions the region as the key source of new demand. Insurers are also adopting parametric covers for typhoon and flood exposure.
MEA and Latin America Reinsurance Market Insights
The Middle East and Africa is led by the United Arab Emirates, where Dubai and Abu Dhabi host regional reinsurance hubs offering favorable regulation and access to Gulf, African and South Asian business. Saudi Arabia is expanding its insurance market under national transformation plans, and South Africa has a mature insurance sector. Demand grows with energy projects, large infrastructure and expanding medical cover. African markets are small, but low penetration implies long-term potential for reinsurers prepared to invest in local relationships and train local underwriting talent.
Latin America is led by Brazil, with Mexico, Chile, Colombia and Argentina also important, and Mexico is treated as part of this region. Earthquake, hurricane and flood exposure encourages cedents to buy catastrophe protection, while Brazil opened its reinsurance market to foreign carriers, drawing competition for local reinsurers. Recent acquisitions of independent Brazilian reinsurers show investor interest, and local regulators continue to refine capital and registration rules. Currency volatility and inflation affect pricing, but demand rises as insurance penetration deepens and as multinational insurers expand their regional footprint.
Growth Drivers: Catastrophe Exposure and Rising Insured Values Drive Growth in the Reinsurance Market
Insured values keep climbing as populations and assets concentrate in coastal and urban areas, and as inflation lifts the cost of rebuilding. Primary insurers need more reinsurance limit to protect the same share of capital, which expands ceded premium even in years with moderate losses. Climate variability adds to uncertainty, so cedents and regulators insist on stronger protection against large events, and rating agencies reward the use of reinsurance in capital models, which makes protection a standard part of balance sheet management.
Persistent claims from large events reinforce demand. Over the past decade, Bermuda insurers and reinsurers incurred roughly USD 1.34 trillion in gross claims and policyholder benefits, with the United States representing 62% of the total. Such concentration means that cedents with exposure in the country need dependable cover, and global reinsurers deploy capital there. Growth of life, health and specialty portfolios in emerging markets adds new buyers across the forecast period, widening the pool of insurers that rely on reinsurance for expertise as well as capital.
⮞In September 2026, the Bermuda Monetary Authority reported that Bermuda insurers and reinsurers incurred about USD 1.34 trillion in gross claims and policyholder benefits over 2016 to 2025, with the United States accounting for USD 827 billion, or 62%. The data highlights the scale and concentration of risk that reinsurance absorbs.
Restraints: Softening Prices and Abundant Capital Restrain Growth in the Reinsurance Market
After several years of hardening, property catastrophe prices have turned lower as record capital chases business. Cedents are able to buy more cover for the same spend or reduce outlay, which lowers premium growth even when limits rise. Reinsurers face pressure to loosen terms, such as attachment points and exclusions, that were tightened in earlier renewals, and some cedents are asking for broader cover at lower prices. If competition continues, margins could narrow just as claims inflation persists in long-tail casualty lines, and weaker underwriters may eventually have to retreat from the least profitable accounts.
Rising retention by large insurers also restrains ceded premium. Well-capitalized carriers are choosing to keep more risk after strong earnings, while catastrophe bonds and other alternative capital draw business away from traditional treaty markets. Casualty uncertainty linked to social inflation and legal system abuse makes some reinsurers reluctant to expand. Geopolitical conflict and trade tensions complicate pricing for marine, aviation and political risk classes, and regulatory reviews of offshore life reinsurance may limit some transactions, adding another layer of uncertainty for long-term planning.
⮞In August 2026, Munich Re reported that risk-adjusted prices at the July renewals fell 5.5% and volume fell 9.1% to EUR 2.9 billion, and it cut its reinsurance insurance revenue outlook for 2026. The renewal results show how softer pricing is reducing written premium.
Opportunities: Alternative Capital and Emerging Market Insurance Penetration Create Opportunities in the Reinsurance Market
Insurance-linked securities allow reinsurers and asset managers to bring institutional capital into the sector. Record catastrophe bond issuance has widened the investor base to include pension funds and sovereign wealth funds seeking returns uncorrelated with financial markets. Reinsurers that act as managers or fronts for this capital can earn fees without carrying all the risk, and sponsors gain multi-year protection. New structures covering cyber, pandemic and parametric risk extend the toolbox, and sponsors from the public sector are returning each year.
Emerging markets present a long runway. Insurance penetration in Asia, Africa and Latin America remains far below developed economies, and growing middle classes, government-backed micro and agricultural schemes and mandatory cover create new primary premium that will need reinsurance support. Parametric solutions, which pay quickly on index triggers, suit climate-vulnerable regions, and development banks support some of the early programs. Reinsurers can also grow in longevity, funded reinsurance and specialty lines, where expertise commands better margins, and technology that improves exposure data creates further openings.
Recent Developments:
-
In August 2026, Hannover Re reported first-half group net income of about EUR 1.4 billion, up about 7%, with a property and casualty reinsurance combined ratio of 83.2% compared with 88.4% a year earlier. The result reflects benign catastrophe experience and disciplined underwriting.
-
In July 2026, SCOR reported first-half net income of EUR 397 million, down 6.8%, and a property and casualty combined ratio of 79.9%, an improvement of 3.9 points. Second-quarter income was weighed down by a loss related to Covea.
-
In October 2026, Vinci Compass Investments agreed to acquire Austral Resseguradora, a Brazilian independent reinsurer. The move shows investor appetite for Latin American reinsurance platforms.
-
In September 2026, Fortitude Re agreed to acquire nearly all of the assets of Dayforward. The transaction adds to consolidation in life and annuity reinsurance.
Reinsurance Market Key Players
-
Munich Re
-
Swiss Re
-
SCOR
-
Lloyd's
-
Berkshire Hathaway Reinsurance Group
-
Reinsurance Group of America
-
Everest Group
-
China Re
-
RenaissanceRe
-
Arch Capital Group
-
Axis Capital
-
Mapfre Re
-
Korean Re
-
Sompo International
-
Tokio Marine HCC
-
AXA XL
Reinsurance Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 521.13 Billion |
| Market Size by 2035 | USD 1,119.88 Billion |
| CAGR | CAGR of 7.95% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Treaty and Facultative) • By Product (Non-Life and Life and Health) • By Line of Business (Property, Casualty, Specialty, and Others) • By Distribution Channel (Broker and Direct) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Munich Re, Swiss Re, Hannover Re, SCOR, Lloyd's, Berkshire Hathaway Reinsurance Group, Reinsurance Group of America, Everest Group, China Re, PartnerRe, RenaissanceRe, Arch Capital Group, Axis Capital, Mapfre Re, Korean Re, Sompo International, Tokio Marine HCC, AXA XL |

Frequently Asked Questions
Key opportunities include alternative capital and catastrophe bonds, specialty lines such as cyber, and rising insurance penetration in Asia, Africa and Latin America. Longevity and funded reinsurance transactions also offer growth for carriers with specialist skills.
The major growth factor is rising insured values combined with catastrophe exposure. Insurers need more reinsurance limit to protect capital, and regulators and rating agencies reward risk transfer.
The Treaty segment dominated the Reinsurance Market in 2025 with approximately 61.55% share. Insurers prefer standing contracts that transfer whole portfolios with predictable capital relief and lower administration costs.
