
Remote Weapon Stations Market Report Scope & Overview:
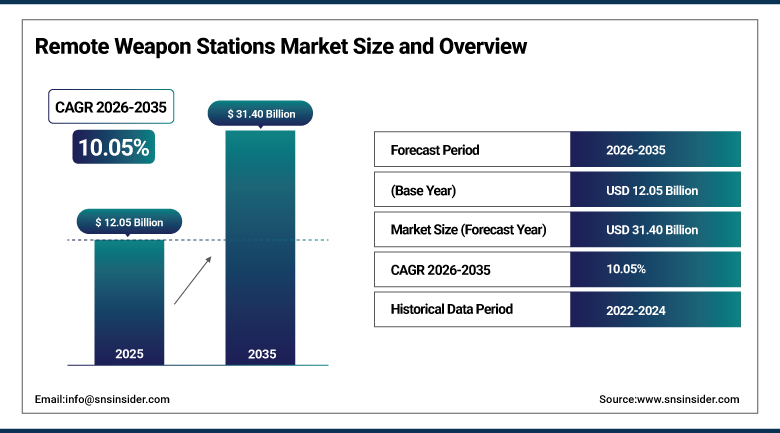
The Remote Weapon Stations Market was valued at USD 12.05 Billion in 2025 and is expected to reach USD 31.40 Billion by 2035, growing at a CAGR of 10.05% from 2026-2035.
The Remote Weapon Stations Market growth is being driven primarily by accelerating defense modernization programs across NATO and Indo-Pacific militaries, which continue to prioritize crew survivability and force protection by shifting weapon operation away from exposed vehicle positions toward remotely operated, armor-protected systems. Rising cross-border tensions and the proliferation of low-cost drones in recent conflicts have elevated demand for remote weapon stations equipped with counter-unmanned aerial system capabilities integrated at the vehicle, vessel, and fixed-installation level. Demand is further reinforced by continued integration of artificial intelligence and automation into targeting and fire control systems, which improves engagement accuracy while reducing operator workload in high-intensity combat environments. Growing procurement of remote weapon stations for homeland security, border protection, and naval patrol applications is expanding the market's addressable base beyond traditional armored vehicle platforms, positioning the industry for sustained, rapid growth through the coming decade.
In March 2024, Kongsberg Defense and Aerospace won a contract from Patria to supply PROTECTOR remote weapon stations for installation on more than 300 Patria armored vehicles destined for Sweden and Finland.
To Get more information Remote Weapon Stations Market - Request Free Sample Report
Remote Weapon Stations Market Trends
- Growing integration of counter-unmanned aerial system capabilities into remote weapon station platforms.
- Rising adoption of AI-enabled targeting and automated fire control to improve engagement accuracy.
- Continued expansion of remote weapon station deployment across naval patrol and coastal defense vessels.
- Increasing procurement of lightweight, modular remote weapon stations for mobile and border security operations.
- Expanding use of remote weapon stations on fixed installations protecting critical infrastructure and forward bases.
U.S. Remote Weapon Stations Market Outlook
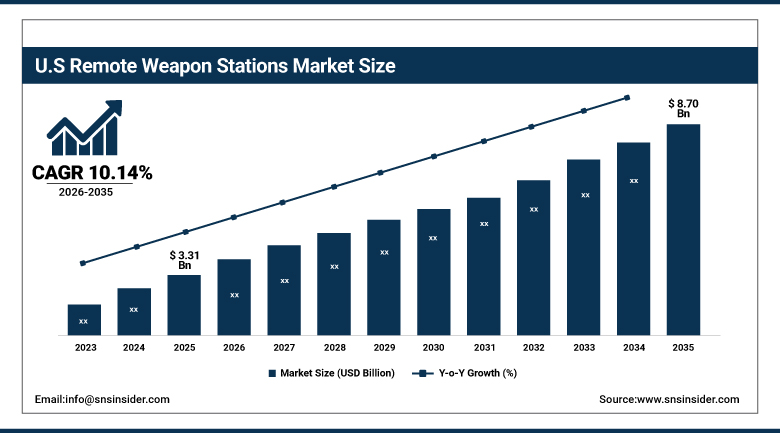
The U.S. Remote Weapon Stations Market was valued at USD 3.31 Billion in 2025 and is expected to reach USD 8.70 Billion by 2035, growing at a CAGR of 10.14% from 2026-2035.
U.S. Remote Weapon Stations Market growth is also being bolstered by continuous investments in defense modernization, the increasing expenditure of the U.S. Navy and Marine Corps in AI and automation for the development of autonomous weapon stations, and the concentration of top producers of remote weapon stations in the country. The market is also driven by the procurement of the systems by various armed force departments in the country, which includes armored ground vehicles, naval patrol boats, and ground-based air defense systems. Improved accuracy of target and increased survivability of the operator are other factors driving the domestic demand.
In July 2023, Kongsberg Protech Systems USA began full-rate production of the Marine Air Defense Integrated System remote weapon station under a USD 94 million, five-year contract awarded to upgrade the U.S. Marine Corps' ground-based air defense systems.
Remote Weapon Stations Market Segment Analysis
- By Component, the Sensors segment dominated the Remote Weapon Stations Market with approximately 34.50% share in 2025, while the Human Machine Interface segment is the fastest growing with a CAGR of approximately 11.80%.
- By Platform, the Land segment dominated the Remote Weapon Stations Market with approximately 58.50% share in 2025, while the Air-Based segment is the fastest growing with a CAGR of approximately 11.20%.
- By Lethality, the Lethal segment dominated the Remote Weapon Stations Market with approximately 57.50% share in 2025, while the Non-Lethal segment is the fastest growing with a CAGR of approximately 11.50%.
- By Technology, the Remote Controlled segment dominated the Remote Weapon Stations Market with approximately 54.0% share in 2025, while the Autonomous segment is expected to be the fastest growing with a CAGR of approximately 14.5% during the forecast period.
By Component, Sensors dominates and Human Machine Interface grows fastest
The sensors category, which comprises of electro-optical and infrared sets, is the leading component segment in the Remote Weapon Stations Market owing to its essential function of providing real-time surveillance, target identification, and precision strike in all kinds of battlefields. The sensor component segment is gaining impetus from innovations in thermal imaging, laser rangefinders, and multi-spectral sensors integration technologies which provide better situational awareness and accuracy in network-centric battlespace.
The human machine interface category has emerged as the fastest growing component segment on account of rising need for efficient and user-friendly control systems which enable the gunner to strike at the target safely from the inside of an armored vehicle or below decks of a naval vessel. Human machine interfaces will emerge as a major recipient of investments in future due to military's focus on operator efficiency in addition to sensor and weapons capabilities.
By Platform, Land dominates and Air-Based grows fastest
Land-based platforms remain the dominant platform segment within the Remote Weapon Stations Market, reflecting sustained armored vehicle modernization programs across NATO and Indo-Pacific militaries that continue integrating remote weapon stations onto wheeled and tracked combat vehicles. This segment benefits from the sheer scale of global armored vehicle fleets requiring remote weapon station retrofits and new-build integration to improve crew survivability in asymmetric warfare conditions.
Air-Based platforms are emerging as the fastest-growing platform segment, driven by increasing integration of remote weapon systems onto helicopters and unmanned aerial vehicles supporting both combat and reconnaissance missions. This segment focuses on lightweight, power-efficient weapon and vision system designs suited to strict aircraft weight and power constraints, positioning air-based platforms to capture growing demand as militaries continue expanding armed unmanned aerial vehicle fleets.
By Lethality, Lethal dominates and Non-Lethal grows fastest
Lethal remote weapon stations have been the largest segment in terms of lethality in the Remote Weapon Stations Market as they form the backbone of modernization of fire-power on land, naval and air platforms. The segment derives strength from defense procurements that emphasize on upgrading of direct-fire lethality systems for ensuring the safety of crews while increasing combat capability compared to the manual weapon stations.
The non-lethal remote weapon stations represent the fastest growing segment of lethality in the market. They cater to the increased homeland security and law enforcement requirements where there is the need for a scaled and graduated response. This segment features modularity in its payload systems, making it possible to transition from lethal to non-lethal engagements and hence making them poised for greater growth in the future due to their applicability in the required security operations.
By Technology, Remote Controlled dominates and Autonomous grows fastest
Remote Controlled systems dominated the Remote Weapon Stations Market in 2025, supported by their widespread deployment across land and naval defense platforms and their established operational reliability. These systems enable operators to engage targets remotely while remaining protected within the vehicle or platform. Continued modernization of existing defense fleets and demand for stabilized, sensor-integrated weapon systems are supporting their leading market position.
Autonomous systems are expected to be the fastest-growing technology segment during the forecast period. Growth is driven by advances in artificial intelligence, automated target recognition, sensor fusion, machine vision, and decision-support technologies. Increasing development of unmanned and optionally crewed platforms is further encouraging defense organizations to integrate higher levels of autonomy into remote weapon systems, supporting rapid adoption of autonomous capabilities.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.50% |
|
Asia Pacific |
India |
38.60% |
|
Europe |
Germany |
34.90% |
|
Latin America |
Brazil |
41.80% |
|
Middle East & Africa |
Israel |
46.60% |
North America Remote Weapon Stations Market Insights
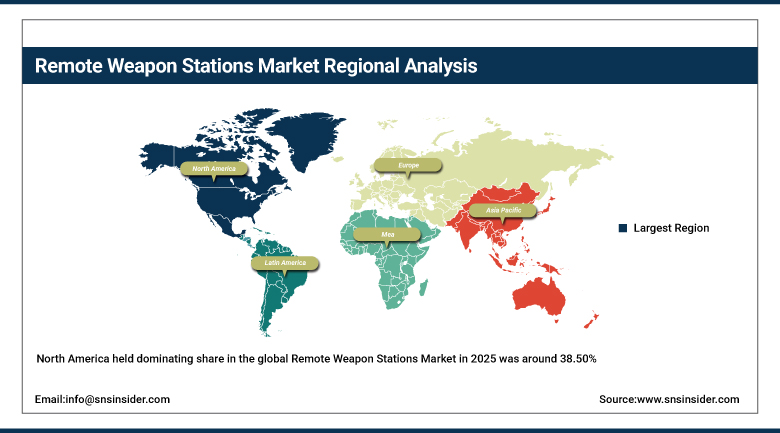
North America held dominating share in the global Remote Weapon Stations Market in 2025 was around 38.50%, owing to high military expenditure in the region. This region holds considerable demand because of procurement from the United States Army, Navy, and Marine Corp. In addition, emphasis on artificial intelligence and automation to ensure the functioning of weapon stations is a contributing factor for the same.
Furthermore, Canada adds to the demand in the region due to involvement in North American defense initiatives. Ongoing increase in the defense budget of the United States and expenditure in targeting and fire control systems will further consolidate its dominance in the regional market for remote weapon stations.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Remote Weapon Stations Market Insights
Asia Pacific is projected to expand at the fastest CAGR of approximately 11.50% across the Remote Weapon Stations Market during the 2026-2035 forecast period, driven by increasing defense expenditures and modernization efforts across the region's armed forces. India represents a particularly significant contributor within the region, supported by substantial indigenous defense production initiatives and growing armored vehicle modernization programs.
China and South Korea contribute additional regional growth, supported by sustained naval and land force modernization programs. Rising regional security tensions and continued government investment in domestic defense manufacturing capability further reinforce Asia Pacific's position as the fastest-growing global market for remote weapon stations.
Europe Remote Weapon Stations Market Insights
Europe region is one of the key markets for the remote weapon station, with Germany having a strong defense industry that includes manufacturers of armored vehicles and weapon systems.
The position of Germany in the European market is defined by its defense industry as well as the supply of the remote weapon station technology to NATO countries that have modernized their armored vehicles. Also, Norway and the United Kingdom are contributing to the regional demand for the technology because of the presence of reliable developers of the defense technology and procurement of NATO members. The high level of regional security tension will result in steady demand in the region.
MEA & Latin America Remote Weapon Stations Market Insights
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in markets such as Israel, which maintains a well-established defense technology ecosystem supporting both domestic use and significant export programs for remote weapon station systems. Gulf Cooperation Council markets contribute additional regional demand through growing defense procurement and border security modernization initiatives.
Latin America's Remote Weapon Stations Market is led by Brazil, which accounts for the majority of regional demand on the strength of its established defense industrial base and growing military modernization initiatives. Gradual expansion of domestic armored vehicle and naval patrol programs continues to support steady regional demand growth.
Market Dynamics
Growth Drivers: Defense Modernization and Crew Survivability Requirements
Growing modernization activities related to armored vehicles in both NATO and Indo-Pacific nations serve as the main drivers for the development of the Remote Weapon Stations Market, with armed forces still giving priority to crew safety amid asymmetric warfare through the transition from open to protected and remotely controlled firing operations. The trend is supported by growing cross-border disputes and increased use of drones in recent military confrontations that result in higher demands for remote weapon stations featuring counter-unmanned aerial systems technology.
Further implementation of artificial intelligence and automation into target acquisition and fire control systems is another key demand driver in the sector, as these tools enhance targeting efficiency and reduce operator workload in the conditions of intense battles. Additional demands for the use of remote weapon stations in homeland security, border protection, and naval patrolling applications will also contribute to market growth.
Restraints: High Procurement Costs and Complex Integration Requirements
The high cost per unit of the advanced remote weapon stations system, especially those that use advanced sensors and targeting technologies based on artificial intelligence, is seen to be one of the major limitations in the Remote Weapon Stations Market owing to budget constraints for modernization programs of the defense sector. It should also be noted that it becomes difficult for such weapon stations to be integrated into older systems since they were manufactured without considering this requirement.
Regulations and restrictions related to export control and transfer of technology create barriers to entry into the market for some manufacturers as a result of which their growth potential is affected. Another challenge is that of the complex nature of the supply chain for some of the components needed for manufacturing of the system.
Opportunities: Counter-Drone Integration and Naval Platform Expansion
Continued integration of counter-unmanned aerial system capabilities presents a substantial growth opportunity for the Remote Weapon Stations Market, as militaries worldwide seek to address the proliferation of low-cost drone threats across both traditional and asymmetric combat environments. Manufacturers that can demonstrate validated, integrated counter-drone remote weapon station solutions are well positioned to capture share as this capability becomes an increasingly standard procurement requirement.
Rising naval fleet modernization programs present a longer-term opportunity for manufacturers to extend remote weapon station technology across frigates, corvettes, patrol vessels, and littoral combat platforms requiring enhanced lethality and crew protection. As homeland security and coastal defense applications continue expanding, manufacturers with established naval-qualified remote weapon station technology are positioned to capture a disproportionate share of this emerging demand.
Recent Developments:
- 2023: EOS Defence Systems was awarded a second conditional contract to supply Ukraine with up to fifty remote weapon systems, along with associated ammunition, spare parts, and related support services.
- 2025: Thales announced the successful deployment of its new remote weapon station, Turret 360, on the French Navy's new generation of patrol boats, expanding the company's presence in naval remote weapon station applications.
Remote Weapon Stations Market Key Players are:
- General Dynamics Corporation
- Northrop Grumman Corporation
- BAE Systems plc
- Rheinmetall AG
- Kongsberg Gruppen ASA
- Elbit Systems Ltd.
- Thales Group
- Saab AB
- Leonardo S.p.A.
- Rafael Advanced Defense Systems Ltd.
- FN Herstal S.A.
- Aselsan A.Ş.
- Moog Inc.
- L3Harris Technologies, Inc.
- Israel Aerospace Industries Ltd.
- KNDS
- General Dynamics Land Systems
- Ultra Electronics Holdings plc
- Chess Dynamics Ltd.
- EOS Defense Systems
Remote Weapon Stations Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 12.05 Billion |
| Market Size by 2035 | USD 31.40 Billion |
| CAGR | CAGR of 10.05% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Sensors, Weapons/Armaments, Human Machine Interface, and Fire Control Station) • By Platform (Land, Naval, and Air-Based) • By Technology (Remote Controlled, Semi-Autonomous, Autonomous) • By Lethality (Lethal and Non-Lethal) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | General Dynamics Corporation; Northrop Grumman Corporation; BAE Systems plc; Rheinmetall AG; Kongsberg Gruppen ASA; Elbit Systems Ltd.; Thales Group; Saab AB; Leonardo S.p.A.; Rafael Advanced Defense Systems Ltd.; FN Herstal S.A.; Aselsan A.Ş.; Moog Inc.; L3Harris Technologies, Inc.; Israel Aerospace Industries Ltd.; KNDS; General Dynamics Land Systems; Ultra Electronics Holdings plc; Chess Dynamics Ltd.; EOS Defense Systems |
Frequently Asked Questions
Leading companies in the Remote Weapon Stations Market include General Dynamics, Northrop Grumman, BAE Systems, Rheinmetall, and Kongsberg Gruppen, among others.
Key opportunities include continued integration of counter-unmanned aerial system capabilities addressing drone proliferation, and rising naval fleet modernization programs requiring enhanced lethality and crew protection.
Increasing armored vehicle modernization programs across NATO and Indo-Pacific regions, combined with rising cross-border tensions and drone proliferation, is the major factor driving market growth.
The Land segment dominated the Remote Weapon Stations Market with approximately 58.50% share in 2025.
North America dominated the Remote Weapon Stations Market in 2025 with approximately 38.50% share, reflecting the region's robust defense budgets and advanced military capabilities, led by the United States.
