
Semiconductor Gases Market Report Scope & Overview:
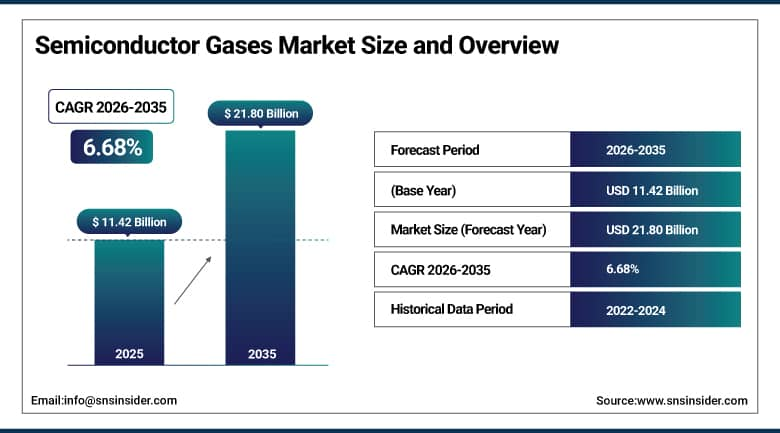
The Semiconductor Gases Market was valued at USD 11.42 Billion in 2025 and is anticipated to climb to USD 12.18 Billion in 2026 and USD 21.80 Billion by 2035, registering a CAGR of 6.68% over 2026–2035. Semiconductor gases are ultra-pure gases and gas mixtures used to deposit films, etch circuit patterns, clean process chambers, dope silicon, cool wafers and protect them from contamination during chip making. They range from bulk nitrogen, argon and hydrogen to specialty fluorine, silicon and dopant compounds, and demand follows wafer starts and the number of process steps per chip.
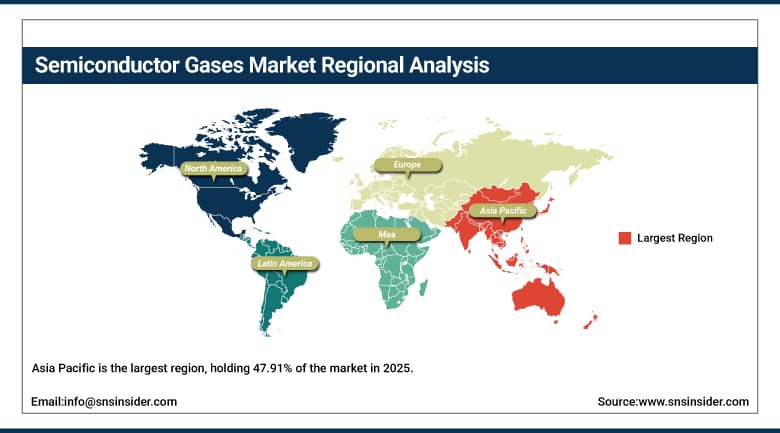
Asia Pacific accounted for the largest share of the market, at 47.91% in 2025, as Taiwan, South Korea, China and Japan operate most of the global wafer fabrication capacity. North America is the second largest region and is also the fastest growing, as new fabs supported by public incentives come online, followed by Europe, Middle East and Africa and Latin America. Reliable supply, purity at parts per billion levels and local delivery decide which gas suppliers win long contracts. Local availability of high-purity supply is a deciding factor in awarding multi-year contracts.
To Get More Information On Semiconductor Gases Market - Request Free Sample Report
Key Report Takeaways
-
By gas category, electronic specialty gases lead the market in 2025, while noble and rare gases are the fastest growing.
-
By process, chamber cleaning leads the market in 2025, while deposition is the fastest growing.
-
By application, logic leads the market in 2025, while memory is the fastest growing.
-
By region, Asia Pacific held a 47.91% share in 2025, while North America is the fastest growing.
Market Trends and Insights
Chip designs are moving to three-dimensional structures, gate-all-around transistors and stacked memory, which multiply the number of deposition and etch steps for each wafer. Every added layer consumes more silicon, nitrogen, fluorine and metal-bearing gases, so gas use per wafer rises even when wafer counts are flat. Suppliers that can deliver new chemistries with consistent purity and tight lot control are being qualified earlier in fab design cycles.
Fabs are being built in new places, and gas suppliers follow them. Industrial gas groups sign multi-decade on-site supply contracts and build air separation units, purification plants and bulk delivery systems next to new clusters in the United States, Japan, Korea, Taiwan and Southeast Asia. These contracts move revenue toward a steady, take-or-pay basis and reward firms that have capital, engineering skill and existing local networks.
Sustainability and supply resilience are shaping purchasing. Gases such as nitrogen trifluoride and sulfur hexafluoride carry high global warming potential, so chipmakers are adopting abatement systems, remote plasma cleaning and lower-impact alternatives. Helium and neon supply shocks have also pushed buyers toward recycling, dual sourcing and long-term allocations with producers. Some fabs now capture and reuse fluorine-bearing exhaust to lower emissions and purchase costs.
Drivers Impact Analysis
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Rising chip demand from AI, data centers and advanced nodes |
+2.64% |
Asia Pacific and North America |
Long term (4 years or more) |
|
Fab construction and public semiconductor incentives |
+2.05% |
North America, Europe and Asia Pacific |
Medium term (2 to 4 years) |
|
Memory expansion and high-bandwidth stacking |
+1.38% |
Asia Pacific and North America |
Short term (2 years or less) |
|
Growth of power, compound and automotive semiconductors |
+0.82% |
Europe, Asia Pacific and North America |
Medium term (2 to 4 years) |
|
Tighter purity needs at smaller geometries |
+0.57% |
Global |
Long term (4 years or more) |
Rising Chip Demand from AI, Data Centers and Advanced Nodes
Artificial intelligence servers, cloud data centers, smartphones and connected vehicles are lifting orders for logic and memory chips, and each advanced chip needs far more process steps than older designs. Foundries are adding leading-edge capacity at nodes where deposition, etch and cleaning steps are most gas intensive, and gas consumption per wafer rises with every new generation. This link between chip complexity and gas use gives suppliers a steady source of volume growth that does not depend only on the number of wafers started. Long supply agreements add visibility to future demand.
Fab Construction and Public Semiconductor Incentives
Governments in the United States, Europe, Japan, South Korea, China, Taiwan and India are funding new fabs, packaging plants and supply chains to reduce reliance on a few locations. Each new fab needs a complete gas package, including bulk gas plants, specialty gas cabinets, piping, purifiers and monitoring systems, often supplied under long contracts. Industrial gas groups are therefore announcing large capital projects near fab clusters, and the spending adds recurring revenue once plants start running. Construction schedules, however, shape the timing of orders.
Memory Expansion and High-Bandwidth Stacking
Demand for high-bandwidth memory used in AI accelerators, along with server DRAM and three-dimensional NAND, is driving capacity additions by the leading memory makers. Stacked memory requires many layers of dielectric and metal film, repeated etching and frequent chamber cleaning, which consume large quantities of silane, ammonia, nitrogen trifluoride, tungsten hexafluoride and fluorocarbons. Memory fabs also use large volumes of nitrogen and hydrogen, so suppliers see broad growth across both bulk and specialty categories in this application. Long contracts with memory makers give suppliers repeat volumes.
Growth of Power, Compound and Automotive Semiconductors
Electric vehicles, renewable energy systems and industrial automation are boosting demand for power devices made from silicon carbide, gallium nitride and silicon. These processes use specific gases for epitaxy, etching and annealing, and many new plants are located in Europe, Japan, China and the United States. Automotive chips also require strict quality records, which favors qualified suppliers. Although volumes are smaller than in leading-edge logic, the diversity of processes broadens demand for specialty chemistries. Strict quality documentation also lengthens qualification and supports supplier loyalty.
Tighter Purity Needs at Smaller Geometries
As feature sizes shrink, even trace amounts of moisture, oxygen, metals or particles can cause defects and lower yield. Fabs therefore specify gases at parts per billion or lower impurity levels and demand detailed analysis and traceability for every lot. Producers invest in better purification, analysis and cylinder handling, and they are paid a premium for high-quality supply. These requirements raise barriers for new entrants and support prices for established, qualified firms. Metrology and in-line gas analyzers support these controls and raise the value of certified deliveries.
Restraints Impact Analysis
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High capital intensity and strict handling and safety rules |
-0.34% |
Global |
Medium term (2 to 4 years) |
|
Supply risk and price swings in helium, neon and other inputs |
-0.21% |
Global |
Short term (2 years or less) |
|
Environmental rules on high-warming gases |
-0.14% |
Europe, North America and Asia Pacific |
Long term (4 years or more) |
|
Cyclical swings in chip capital spending |
-0.09% |
Global |
Short term (2 years or less) |
High Capital Intensity and Strict Handling and Safety Rules
Many specialty gases are toxic, flammable, corrosive or pyrophoric, so suppliers must invest in specialized cylinders, valves, purifiers, leak detection and emergency systems. Building on-site plants and purification lines costs hundreds of millions of dollars, and contracts run for many years before returns are earned. Transport and storage rules add further cost, and an accident can interrupt production, which makes new entrants cautious and slows expansion into smaller markets. Smaller fabs in emerging regions often depend on distributors because of these costs.
Supply Risk and Price Swings in Helium, Neon and Other Inputs
Several inputs come from a few sources. Helium depends on natural gas fields and limited processing plants, neon and other noble gases are by-products of large steel and air separation units, and fluorspar and rare earth based chemicals are concentrated in certain countries. Disruptions from conflict, export limits or plant outages can lift prices sharply, and chipmakers sometimes reduce purchases or switch process recipes. Such swings make planning harder for both suppliers and fabs. Recycling programs remain costly and uneven across regions.
Environmental Rules on High-Warming Gases
Fluorinated gases used for etching and chamber cleaning, including nitrogen trifluoride, sulfur hexafluoride and perfluorocarbons, have a very high global warming effect. Governments and customers are setting emission targets, and phase-down programs may limit use of the worst gases. Fabs must buy abatement equipment and test alternatives, which adds cost and extends qualification times. Companies that cannot offer lower-impact chemistries may lose share over the long term. Phase-down timetables differ by country, so suppliers face a patchwork of rules when planning global product lines.
Cyclical Swings in Chip Capital Spending
Semiconductor investment moves in cycles, and weak demand for consumer electronics or inventory corrections can lead chipmakers to postpone fab expansions and cut utilization. Bulk and specialty gas use falls with utilization, and project timelines slip when customers delay tool installation. Although long contracts soften the effect, sudden downturns can reduce volumes and hurt supplier earnings in the short term. Utilization at mature nodes can also fluctuate with demand from automotive and industrial customers, and suppliers with fixed plant costs feel the effect first.
Semiconductor Gases Segment Analysis
By Gas Category, Electronic Specialty Gases Dominate Semiconductor Gases Market; Noble and Rare Gases to Register Fastest Growth.
Electronic specialty gases lead the gas category axis in 2025. This group includes silane, ammonia, nitrogen trifluoride, tungsten hexafluoride, fluorocarbons, hydrogen chloride and dopant gases such as phosphine, arsine and diborane. Each plays a defined role in film deposition, etching, cleaning or doping, and each is sold at high purity and high unit value, so the group captures the largest revenue even though bulk gases are used in larger volumes. Cylinder and bulk supply options suit fabs of varying size.
Noble and rare gases are expected to register the fastest growth, at a CAGR of 7.94% during 2026–2035. Neon, krypton and xenon are essential for excimer laser lithography and plasma processes, and helium is used to cool wafers. More lithography steps and tight supply push buyers to sign long contracts, and suppliers are adding recovery and purification capacity to serve fabs reliably. Fabs also value dependable delivery schedules, which allow suppliers with local inventory to win repeat orders.
By Process, Chamber Cleaning Dominates Semiconductor Gases Market; Deposition to Register Fastest Growth.
Chamber cleaning leads the process axis in 2025. After each deposition run, films build up on chamber walls and must be removed, usually with fluorine-bearing gases such as nitrogen trifluoride and fluorocarbons activated in plasma. Because tools are cleaned very often, the cleaning step consumes large volumes of gas, and the rising number of deposition layers in advanced logic and memory increases cleaning frequency. Fabs treat cleaning gases as consumables, so spending rises with tool utilization and wafer output.
Deposition is projected to register the fastest growth, at a CAGR of 7.21% over 2026–2035. Chemical vapor deposition and atomic layer deposition use silane, ammonia, tungsten hexafluoride and metal-organic precursors with carrier gases to build dielectric and metal films. Three-dimensional device structures need many more layers, and each added layer lifts gas demand. Precursors for silicon nitride, silicon dioxide and tungsten films are supplied under tight purity and delivery requirements. Equipment makers collaborate with gas suppliers on new recipes.
By Application, Logic Dominates Semiconductor Gases Market; Memory to Register Fastest Growth.
Logic leads the application axis in 2025. Processors, accelerators and system-on-chip devices made at leading foundries use hundreds of process steps, and advanced nodes are especially gas intensive. Large investments in cutting-edge fabs in Taiwan, South Korea, the United States and Japan sustain demand, and customers hold supply contracts with strict purity and delivery requirements. Foundry customers sign long supply agreements, and gas companies place purification and monitoring systems inside their fabs to guarantee consistent quality at each site.
Memory is expected to register the fastest growth, at a CAGR of 7.48% during 2026–2035. High-bandwidth memory for AI accelerators, server DRAM and stacked NAND require tall multilayer structures, repeated etching and heavy chamber cleaning. Leading memory makers are expanding capacity, which raises consumption of both bulk and specialty gases. Suppliers expect memory to remain a strong growth source as AI servers absorb more output, and several are building gas plants near memory fabs in Korea and Japan.
Geography Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
Taiwan |
31.40% |
|
Europe |
Germany |
34.60% |
|
North America |
United States |
94.20% |
|
Middle East and Africa |
Israel |
58.30% |
|
Latin America |
Brazil |
46.70% |
Asia Pacific Semiconductor Gases Market
Asia Pacific is the largest region, holding 47.91% of the market in 2025. Taiwan hosts the leading foundry cluster, South Korea leads in memory, Japan is a major supplier of materials and equipment, and China is rapidly expanding mature-node and memory capacity. Industrial gas groups run large on-site plants in these countries, and local producers are growing in both bulk and specialty gases as governments push for local supply. Government subsidies for local chip supply chains encourage gas projects in several countries.
Southeast Asia is gaining importance in assembly, test and some wafer fabrication, with Singapore, Malaysia and Vietnam attracting new plants. India has begun building its first fabs and packaging facilities, which will create a new gas demand center. Regional competition is intense, and suppliers must provide fast delivery, local purification and strong technical service. Procurement teams in the region value suppliers that can deliver quickly, run purification inside the fab and respond to quality incidents within hours. Quick response is a decisive edge.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Semiconductor Gases Market
Europe held 19.84% of the market in 2025. Germany leads regional demand through its power, automotive and sensor chip fabs, while France, Italy, the Netherlands and Ireland add demand from logic, analog and equipment makers. Regional policy aims to raise the share of chips made in Europe, and new fabs and expansions of existing sites support gas orders. Dresden, Grenoble and Eindhoven are well known chip clusters, and universities and research institutes help supplier firms test new gas chemistries with local fabs.
Strict environmental and safety rules shape product choices, and chipmakers are active in adopting abatement systems and lower-impact gases. Several industrial gas groups are headquartered in Europe, which gives local fabs a strong supplier base, though high energy prices raise the cost of producing gases such as nitrogen and oxygen. Imports of noble gases and fluorine chemicals from outside the region leave some exposure to supply shocks. Suppliers respond with recycling, strategic stocks and investment in regional purification plants, which builds resilience for fabs across the continent.
North America Semiconductor Gases Market
North America accounted for 28.36% of the market in 2025 and is the fastest growing region, with a projected CAGR of 7.42% during 2026–2035. The United States market was valued at USD 3.05 Billion in 2025 and is projected to register a CAGR of 7.35% over the same period. Federal incentives have triggered large fab projects in Arizona, Texas, New York and Ohio. Ultra-high-purity nitrogen, oxygen, argon and hydrogen are the first products needed during fab construction, followed by specialty gases once tools are installed.
Each new site requires bulk gas plants, specialty gas systems and purification, so suppliers are committing large capital to the region. Canada contributes through compound semiconductor and research activity, and helium and rare gas supply from the continent give local buyers a degree of security. Construction timelines and labor availability remain the main factors shaping the pace of growth. Texas and Oregon also host established fabs that need steady supply, and Idaho and Utah add memory and analog demand, which gives suppliers a broad customer base.
Middle East and Africa Semiconductor Gases Market
Middle East and Africa accounted for 2.47% of the market in 2025. Israel leads the region with advanced chip design, several fabs and strong equipment and materials firms, which buy specialty and bulk gases through global suppliers. Gulf states are exploring semiconductor and data center projects as part of diversification plans. Universities and research parks in Saudi Arabia and the United Arab Emirates are building labs for chip design and advanced materials, which creates small but growing demand for research gases.
Local manufacturing is still limited, and most gases are imported or produced by international gas groups that operate regional plants. Strong energy resources, low-cost helium production in Qatar and Algeria and government investment programs may support future demand, but the region remains small during the forecast period. Africa has little chip production, although assembly of electronic goods in Egypt, Morocco and South Africa uses basic nitrogen and industrial gases. Distribution depends on regional gas companies and global importers, and costs are high.
Latin America Semiconductor Gases Market
Latin America held 1.42% of the market in 2025. Brazil leads the region with assembly and test operations, electronics manufacturing and research programs, while Argentina and Chile add small volumes. Mexico supports electronics assembly and some packaging tied to North American supply chains, and demand for gases there comes mainly from this back-end activity. Universities and public research centers in Brazil and Argentina train engineers and operate small cleanrooms, and these users buy research grade gases in cylinders from regional gas distributors.
Wafer fabrication is minimal, so consumption is low compared with other regions. Government programs in Brazil seek to attract chip packaging and design investments, which could raise gas needs in the longer term. Currency swings and import dependence continue to restrain growth and keep the region a small part of global sales. Costa Rica, which hosts chip packaging and medical device plants, is another local demand source, and global gas groups supply it through regional filling stations. Investment in test facilities could lift volumes gradually.
Competitive Landscape
The Semiconductor Gases Market is consolidated at the top, with a handful of global industrial gas groups supplying bulk gases, on-site plants and many specialty gases, alongside Japanese, Korean and Chinese producers of electronic specialty gases and chemical companies that make fluorinated and silicon-based gases. Long qualification cycles and large capital needs make it difficult for newcomers to enter.
Competition depends on purity, security of supply, proximity to fabs, technical service and the ability to develop new chemistries. Leading firms are building on-site plants, expanding purification, recycling noble gases and offering abatement and monitoring services. Over the forecast period, regional production close to fab clusters and long-term contracts are expected to separate strong suppliers from the rest.
Semiconductor Gases Industry Leaders
1. Linde plc
2. Air Liquide
3. Air Products and Chemicals
4. Nippon Sanso Holdings
5. Messer Group
Companies Covered in this Report
-
Air Liquide
-
Air Products and Chemicals
-
Iwatani Corporation
-
Linde plc
-
Matheson Tri-Gas
-
Messer Group
-
Nippon Sanso Holdings
-
Resonac
-
Sumitomo Seika Chemicals
Recent Industry Developments
-
June 2026: Air Liquide announced an investment of nearly EUR 200.00 Million in a nitrogen plant and supply of ultra-clean gases for SK hynix packaging and test fab P&T7 in Cheongju, South Korea.
-
July 2026: Linde announced an investment of USD 1.00 Billion at its Phoenix, Arizona gases complex, adding two air separation units to supply ultra-high-purity gases to two new semiconductor fabs.
-
September 2026: Air Products won a long-term contract to supply high-purity gases for a major semiconductor expansion in Arizona and plans a USD 250.00 Million plant for hydrogen, helium and carbon dioxide.
Scope and Research Methodology
This study sizes the Semiconductor Gases Market for 2025 and forecasts it to 2035. The scope covers bulk, specialty and noble gases and gas mixtures supplied to semiconductor wafer fabrication, measured as supplier sales value in USD, including on-site supply and cylinder, bundle and bulk delivery. Photoresists, wet chemicals, silicon wafers, gas delivery equipment and gases used only in other electronics such as displays and solar cells are excluded. Values are reported on a calendar year basis, and trade is allocated to the country of production. The historical period covers 2021 to 2024 and the forecast period covers 2026 to 2035.
Research began with a review of wafer capacity statistics, fab construction announcements, industrial gas company filings, trade data, government incentive programs and technical papers. Demand was built from the bottom up using wafer starts, process steps and gas consumption per wafer by node and device type, and it was cross-checked from the top down using the sales of leading gas suppliers to electronics customers. Segment and regional shares were set from fab capacity, process mix and supply contracts in each geography. Gas prices were reviewed by purity grade and delivery mode to convert volume into revenue, and constant exchange rates were used to remove currency effects from the series. Assumptions were documented for each major country.
Findings were validated through discussions with industrial gas suppliers, electronic gas producers, fab gas engineers and equipment makers, and the forecast was tested under scenarios for chip investment, helium and neon supply, environmental rules and technology change. Growth rates reflect expected fab openings, rising process complexity and purity requirements. Values are expressed in USD, rounded to two decimals, and the analysis is refreshed when major market or policy changes occur. Estimates for each region were checked against national industrial gas and trade statistics where available, and adjustments were made for imported and exported cylinders. Results are reviewed periodically.
Semiconductor Gases Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 11.42 Billion |
| Market Size by 2035 | USD 21.80 Billion |
| CAGR | CAGR of 6.68% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Gas Category (Electronic Specialty Gases, Noble and Rare Gases, and Bulk Gases) • By Process (Chamber Cleaning, Deposition, Etching, and Others) • By Application (Logic, Memory, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Air Liquide, Air Products and Chemicals, Iwatani Corporation, Linde plc, Matheson Tri-Gas, Messer Group, Nippon Sanso Holdings, Resonac, Sumitomo Seika Chemicals |

Frequently Asked Questions
The market was valued at USD 11.42 Billion in 2025 and is expected to reach USD 12.18 Billion in 2026 and USD 21.80 Billion by 2035.
The market is projected to grow at a CAGR of 6.68% during 2026–2035.
Asia Pacific holds the largest share, at 47.91% in 2025, led by Taiwan.
North America is the fastest growing region, with a projected CAGR of 7.42% during 2026–2035.
Electronic specialty gases, chamber cleaning and logic lead, while noble and rare gases, deposition and memory grow fastest.
