
Silicon Carbide Market Report Scope & Overview:
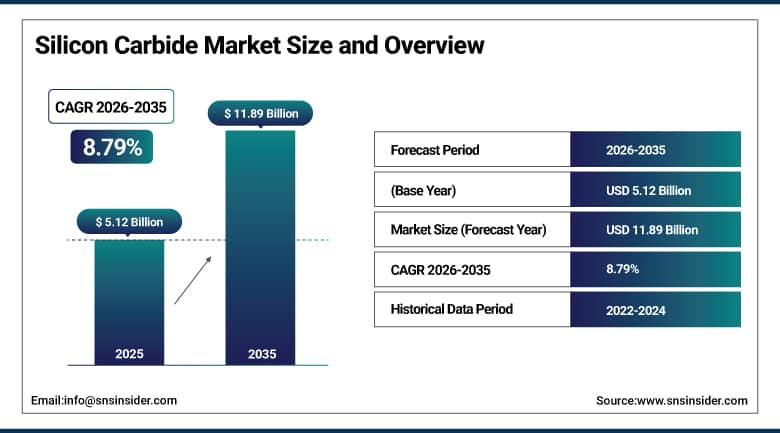
The Silicon Carbide Market was valued at USD 5.12 Billion in 2025 and is expected to reach USD 11.89 Billion by 2035, growing at a CAGR of 8.79% from 2026-2035.
The Silicon Carbide Market covers synthetic silicon carbide produced as grain, powder, ceramic, substrate wafer and finished power device. Traditional black and green grades serve grinding wheels, cutting tools, refractories, ceramics and steelmaking, while crystalline wafers carry power transistors and diodes that switch faster and withstand higher voltages and temperatures than silicon. Electric vehicles, fast chargers, solar inverters, grid equipment and data center power supplies are pulling the wide bandgap segment, and industrial users keep the material base steady. Larger wafer sizes and new thermal management uses are expanding opportunities through 2035. Suppliers able to scale wafers while keeping defects low are best placed to benefit. Government support for compound semiconductors reinforces this outlook.
⮞The International Energy Agency reported in May 2026 that electric car sales grew 20% in 2025 to exceed 20 million, about a quarter of all new cars sold, and that 23 million are expected in 2026.
To Get More Information On Silicon Carbide Market - Request Free Sample Report
Silicon Carbide Market Trends
-
Wafer diameters are moving from 150 mm to 200 mm, and early 300 mm substrates are being sampled, which promises lower cost per chip.
-
New-generation trench and planar MOSFETs with lower specific on-resistance at high temperature are reaching sampling stages across the industry.
-
Voltage classes are widening, with 750 V and 1200 V parts for vehicles and 2300 V to 3300 V modules for solar, storage and grid equipment.
-
High thermal conductivity substrates are being tested as heat spreaders for artificial intelligence processors in data centers.
-
Licensing and long-term wafer supply agreements are replacing purely in-house production as suppliers share capacity and technology.
U.S. Silicon Carbide Market Outlook
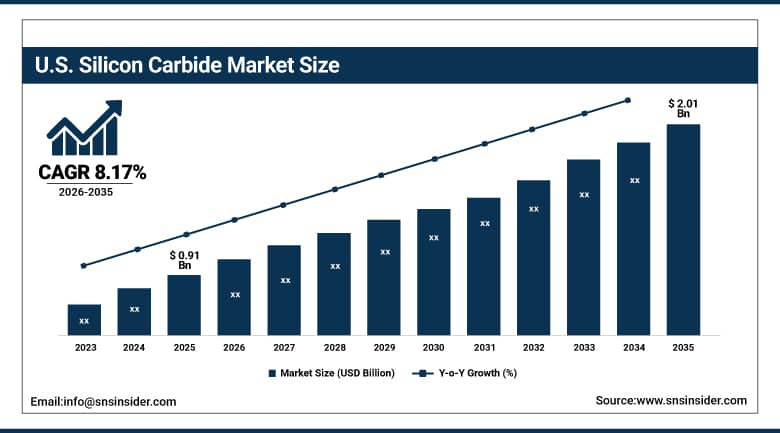
The U.S. Silicon Carbide Market was valued at USD 0.91 Billion in 2025 and is expected to reach USD 2.01 Billion by 2035, growing at a CAGR of 8.17% from 2026-2035.
The U.S. Silicon Carbide Market is the largest national market in North America, supported by leading power device designers, a major substrate and wafer producer in New York and growing electric vehicle and storage programs. Federal incentives for local chip production and critical materials encourage investment in fabs and crystal growth. Automakers, solar developers and utilities are specifying silicon carbide for chargers, inverters and converters, while aerospace and defense programs value its heat tolerance and radiation resistance. Established abrasive and ceramic producers add steady industrial demand through 2035. University research centers add materials expertise and talent. Strong venture funding supports start-ups in related materials.
⮞The U.S. Energy Information Administration reported on 20 February 2026 that developers planned 86 gigawatts of new utility-scale capacity in 2026, including 43.4 gigawatts of solar and 24 gigawatts of battery storage.
Silicon Carbide Market Segment Analysis
-
By Product, the Black Silicon Carbide segment dominated the Silicon Carbide Market with approximately 53.48% share in 2025, while the Green Silicon Carbide segment is the fastest growing with a CAGR of approximately 12.37%.
-
By Device Type, the Discrete Devices segment dominated the Silicon Carbide Market with approximately 51.74% share in 2025, while the Power Modules segment is the fastest growing with a CAGR of approximately 14.38%.
-
By Application, the Electrical & Electronics segment dominated the Silicon Carbide Market with approximately 30.72% share in 2025, while the Automotive segment is the fastest growing with a CAGR of approximately 12.41%.
By Product, Black Silicon Carbide Dominates the Silicon Carbide Market and Green Silicon Carbide Grows Fastest
Black silicon carbide holds approximately 53.48% of the Silicon Carbide Market in 2025 because it is produced in large volumes at relatively low cost and offers excellent hardness, thermal conductivity and chemical resistance. It is the workhorse grade for grinding wheels, sandblasting, refractory linings, metallurgical additives and wear-resistant ceramics. Steel plants, foundries and ceramic makers consume it in bulk, and a mature supply chain, mainly in China, keeps pricing competitive for industrial buyers. Recycling of spent grain is also growing. Industrial adoption of this product group remains steady.
Green silicon carbide is the fastest growing product, with a CAGR of approximately 12.37% during 2026-2035. Its higher purity makes it suitable for precision grinding, wafer slicing, lapping of semiconductors and photovoltaic silicon, and for high-grade ceramics. Solar and electronics manufacturers rely on it for wire-saw slurries and polishing. The grade also serves as feedstock for crystal growth in power device substrates, linking it directly to the expansion of wide bandgap semiconductors. Rising solar installation and wafer production make this grade a closely watched indicator of electronics demand. Specialty producers are expanding purification lines to meet semiconductor-grade specifications.
⮞The World Steel Association reported on 23 January 2026 that world crude steel output in 2025 was 1,849.4 million tonnes, down 2.0% from the previous year.
By Device Type, Discrete Devices Dominate the Silicon Carbide Market and Power Modules Grow Fastest
Discrete devices account for approximately 51.74% of the market in 2025, led by silicon carbide MOSFETs and Schottky diodes sold in standard packages. They are used in onboard chargers, power factor correction stages, solar string inverters, server power supplies and industrial drives, where designers value fast switching and low losses. Wide voltage choices from 650 V to 1700 V, broad distributor availability and drop-in compatibility with existing designs make discretes the easiest entry point. Distributors provide reference designs and evaluation boards that shorten design cycles. Industrial adoption of this product group remains steady.
Power modules are the fastest growing device type, with a CAGR of approximately 14.38% during 2026-2035. Traction inverters in electric vehicles, utility-scale solar, energy storage systems, railway traction and high-power chargers require modules that combine many chips with low-inductance packaging. Newer designs reach 2300 V and above for grid and storage uses. Automakers increasingly buy modules rather than discretes, because integration shortens development time and improves thermal performance. Suppliers also develop sintered silver and copper-clip interconnects to raise current capability and reliability. Evaluation kits ease prototyping.
⮞SEMI reported on 29 July 2026 that worldwide silicon wafer shipments in the second quarter of 2026 reached 3,573 million square inches, up 7.4% year on year.
By Application, Electrical & Electronics Dominates the Silicon Carbide Market and Automotive Grows Fastest
Electrical and electronics account for approximately 30.72% of the market in 2025 because silicon carbide is used in power supplies, industrial drives, renewable inverters, uninterruptible power systems, lighting, telecommunications and consumer chargers. Abrasive and ceramic uses in electronics manufacturing, such as wafer slicing and polishing, add further volume. The segment benefits from steady investment in data centers and energy infrastructure, and from designers replacing silicon in applications that demand higher efficiency. Telecom base stations are another recurring source of volume. Industrial adoption of this product group remains steady.
Automotive is the fastest growing application, with a CAGR of approximately 12.41% through 2035. Silicon carbide traction inverters extend electric vehicle range and allow faster charging at 800 V architectures, and the material also appears in onboard chargers and direct-current converters. Carmakers in China, Europe and the United States are specifying it in more models, and falling device prices are pushing adoption into mid-priced vehicles. Heavy-duty trucks, buses and off-road vehicles are beginning to follow passenger cars in specifying the technology. Fast charging networks along highways are also expanding quickly.
⮞The China Association of Automobile Manufacturers reported in January 2026 that new energy vehicle sales in China exceeded 16 million units in 2025, more than half of all new-car sales.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
83.64% |
|
Asia Pacific |
China |
46.18% |
|
Europe |
Germany |
29.37% |
|
Latin America |
Brazil |
51.26% |
|
Middle East & Africa |
South Africa |
27.43% |
Asia Pacific Silicon Carbide Market Insights
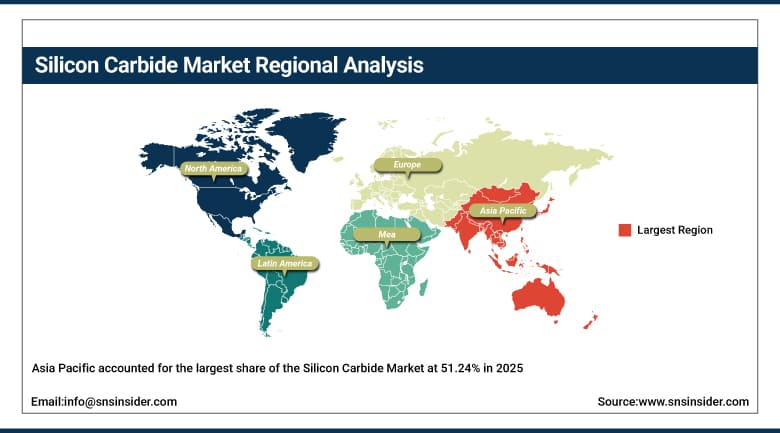
Asia Pacific accounted for the largest share of the Silicon Carbide Market at 51.24% in 2025 and is also the fastest growing region, with a CAGR of 11.86% during 2026-2035. China, Japan, South Korea, Taiwan and India combine the world’s largest silicon carbide grain production, rapidly growing electric vehicle output and extensive semiconductor manufacturing. Chinese producers dominate black and green grades and have expanded substrate capacity quickly, while Japanese firms lead in device quality and crystal growth. Local wafer capacity is expanding quickly. Trade policy influences exports of grain and wafers.
China is the largest country market, supported by vehicle electrification, solar installation and local wafer makers that are scaling 200 mm lines and showing 300 mm prototypes. Japan contributes premium MOSFETs and substrates, and South Korea adds wafer production and automotive demand. India is building steel, abrasive and renewable energy capacity, and Southeast Asian countries host assembly and packaging plants. Government support for compound semiconductors strengthens the regional chain. Strong competition on price pushes global suppliers to deepen local partnerships. Rapid scale-up also raises questions about quality consistency, which buyers track carefully.
⮞China’s National Energy Administration reported on 28 January 2026 that the country added 315.07 gigawatts of solar capacity in 2025, bringing total solar capacity to 1.20 terawatts.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Silicon Carbide Market Insights
North America held approximately 21.38% of the Silicon Carbide Market in 2025, with the United States contributing about 83.64% of regional demand and Canada the balance. The region is home to leading power semiconductor designers, a pioneering substrate producer and several abrasive and ceramics makers. Electric vehicle platforms, data center power systems, solar and storage projects and defense electronics all create demand. Policy support for local chip manufacturing is encouraging new capacity and supply agreements. Public funding programs strengthen the regional supply chain.
Canada adds demand through mining, steel and electric bus programs, while Mexico, which belongs to Latin America, hosts automotive assembly that buys devices for vehicles sold in the United States. Industrial users of abrasives and refractories maintain a stable base. Suppliers in the region emphasize secure, traceable supply chains and are negotiating long-term wafer contracts with European and Asian device makers, which provides revenue visibility. Defense programs requiring trusted supply also contribute. Oil and gas, mining and rail customers add further steady demand.
⮞The U.S. Department of Energy’s Argonne National Laboratory reported in April 2026 that about 1.5 million plug-in vehicles were sold in the United States in 2025, 9.1% of passenger vehicle sales.
Europe Silicon Carbide Market Insights
Europe accounted for approximately 17.63% of the Silicon Carbide Market in 2025, led by Germany, France, Italy, the United Kingdom and the Nordic countries. The region hosts major power semiconductor makers with large silicon carbide fabs, a strong automotive industry and leading industrial drive and renewable energy suppliers. Policies encouraging local chip production and a rapid shift to battery electric vehicles support investment, and abrasive and refractory makers add a long-established materials base. Research institutes provide training and pilot lines. Energy-intensive producers are looking at renewable power to cut emissions.
Germany is the largest market, supported by automotive and industrial automation customers, while Italy and France contribute through power electronics and ceramics. Austria and the Nordic region add capacity in wafer processing and heavy industry. European buyers prioritize reliability, sustainability and supply chain security, and several manufacturers are signing multi-year supply agreements for 200 mm substrates from overseas partners to secure volumes. Rail operators and wind turbine makers add steady orders for power modules, and public subsidies for charging infrastructure further support the market.
The European Automobile Manufacturers’ Association reported on 27 January 2026 that battery-electric cars reached 1,880,370 registrations in the European Union in 2025, a 17.4% share compared with 13.6% in 2024.
MEA & Latin America Silicon Carbide Market Insights
The Middle East and Africa and Latin America together account for approximately 9.75% of the Silicon Carbide Market in 2025, with the Middle East and Africa at 5.46% and Latin America at 4.29%. Demand is mainly for abrasives, refractories and ceramics used in steel, mining, foundry and construction, and for imported power devices in solar and storage projects. In the Middle East, Saudi Arabia and the United Arab Emirates are expanding solar and industrial zones, while South Africa and Egypt use the material in metals and mining.
Latin America is led by Brazil and Mexico. Brazil has a large steel and mining sector and a growing electrified vehicle market, and Mexico has automotive and electronics assembly that consumes devices and abrasives. Argentina, Chile and Colombia add demand through mining and renewable energy. Most advanced silicon carbide products are imported, and distributors and local grinding wheel makers are key channels. Rising electric vehicle adoption is expected to lift device use over time. Mining electrification should also add demand for power devices over the long term.
⮞Brazil’s automotive manufacturers association ANFAVEA reported on 8 May 2026 that Brazil sold 285,400 electrified cars in 2025 and projected 420,000 to 450,000 for 2026.
Market Dynamics
Growth Drivers: Electric Vehicles and Renewable Power Drive Growth in the Silicon Carbide Market
Electric vehicle adoption is the strongest force behind the Silicon Carbide Market. Traction inverters built with silicon carbide waste less energy, which extends driving range or allows smaller batteries, and they support 800 V charging that cuts stop times. Automakers are moving the technology from premium models to volume vehicles as device costs fall. Onboard chargers and direct-current converters add further content per vehicle, and charging stations rely on the same devices to reach high power levels. Government purchase incentives support this shift in many regions. Corporate fleets are also electrifying.
Renewable energy and grid modernization form the second driver. Solar inverters, battery storage converters, wind turbines and high-voltage direct-current links use silicon carbide to cut losses and shrink hardware. Data center operators adopt it in server power supplies to improve efficiency. Strong growth in the broader semiconductor industry gives suppliers capital to expand crystal growth and wafer capacity, and larger wafers lower cost per chip and widen use. Grid operators are also installing converter stations that depend on high-voltage modules.
⮞The Semiconductor Industry Association reported on 6 February 2026 that global semiconductor sales rose 25.6% in 2025, with fourth-quarter sales up 37.1% year on year.
Restraints: High Substrate Costs and Cooling Component Sentiment Restrain Growth in the Silicon Carbide Market
High production cost is the main restraint on the Silicon Carbide Market. Growing defect-free crystals takes days at temperatures above 2,000 degrees Celsius, the boules are hard to cut and polish, and yields are lower than for silicon. As a result silicon carbide devices still sell at a premium to silicon alternatives, which limits adoption in cost-sensitive products. Capital requirements for new fabs and crystal furnaces are large, and ramp-ups have sometimes slipped. Furnace downtime and power costs raise per-wafer expense.
Demand uncertainty adds pressure. Electric vehicle growth varies by region, and slower sales in some markets can leave suppliers with excess capacity and falling prices, particularly as new Chinese producers expand. Competition from gallium nitride in lower-voltage uses and from advanced silicon devices in some designs also limits the addressable market. Qualification periods in automotive and industrial settings are long, and supply chain concentration raises geopolitical concerns. Price declines for silicon carbide devices narrow the gap with silicon but also squeeze supplier margins. Trade restrictions on equipment and materials add uncertainty.
⮞The Electronic Components Industry Association reported on 1 May 2026 that its sales sentiment index was 146.6 in April 2026 but fell to 130.5 for the May outlook.
Opportunities: Larger Wafers and AI Data Centers Create Opportunities in the Silicon Carbide Market
Larger wafers create a major opportunity. Moving from 150 mm to 200 mm substrates increases the number of chips per wafer and reduces cost per device, and early work on 300 mm substrates points to further savings. Suppliers that master large-diameter crystal growth and low-defect epitaxy can win long-term supply contracts from device makers. Consolidated supply agreements also give wafer producers the revenue visibility needed to justify new capacity. Cooperation among suppliers helps spread the investment burden. Wafer reclaim and recycling programs may also help.
Artificial intelligence data centers provide a second opening. Silicon carbide has very high thermal conductivity, and sampling of high-conductivity substrates as heat spreaders for advanced processors has begun. Power conversion within server racks also benefits from the material. Renewable energy expansion in India and other emerging markets, and grid-scale storage, add large volumes of inverters and converters that use silicon carbide devices. Public funding for new fabs and research centers reinforces these efforts. Cooperative research programs speed progress. Policy support remains a key enabler.
Recent Developments:
-
2026: ROHM announced its fifth-generation SiC MOSFETs, delivering approximately 30% lower on-resistance at a junction temperature of 175 degrees Celsius than the fourth generation at the same breakdown voltage and chip size, with samples scheduled from July 2026.
-
2026: Wolfspeed launched Gen 5 SiC MOSFETs in a 5 x 5 mm footprint in 1200 V and 750 V classes, with specific on-resistance of 3.4 and 2.0 mΩ·cm² at 175 degrees Celsius, built at its 200 mm Mohawk Valley fab.
-
2026: Coherent began customer sampling of 300 mm high thermal conductivity SiC substrates for artificial intelligence semiconductor partners, providing up to 25% better heat spreading.
-
2026: Navitas Semiconductor introduced a 2300 V full-bridge SiC module family in the SiCPAK package with 8 mΩ on-resistance, aimed at solar, storage and industrial power conversion.
Silicon Carbide Market Key Players are:
-
onsemi
-
Infineon Technologies AG
-
STMicroelectronics N.V.
-
ROHM Co., Ltd.
-
Wolfspeed, Inc.
-
Navitas Semiconductor Corporation
-
Microchip Technology Incorporated
-
SemiQ Inc.
-
Magnachip Semiconductor Corporation
-
Coherent Corp.
-
Shandong SICC Co., Ltd.
-
Washington Mills Group
-
Saint-Gobain Performance Ceramics & Refractories
-
Carborundum Universal Limited
Silicon Carbide Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 5.12 Billion |
| Market Size by 2035 | USD 11.89 Billion |
| CAGR | CAGR of 8.79% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Black Silicon Carbide, Green Silicon Carbide, and Others) • By Device Type (Discrete Devices, Power Modules, and Bare Die) • By Application (Electrical and Electronics, Automotive, Steel, Aerospace and Defense, Energy, Healthcare, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | onsemi, Infineon Technologies AG, STMicroelectronics N.V., ROHM Co., Ltd., Wolfspeed, Inc., Navitas Semiconductor Corporation, Microchip Technology Incorporated, SemiQ Inc., Magnachip Semiconductor Corporation, Coherent Corp., Shandong SICC Co., Ltd., Washington Mills Group, Saint-Gobain Performance Ceramics & Refractories, Carborundum Universal Limited |

Frequently Asked Questions
The key players in the Silicon Carbide Market include onsemi, Infineon Technologies AG, STMicroelectronics N.V., ROHM Co., Ltd., Wolfspeed, Inc., among others.
Key opportunities include the shift to 200 mm and 300 mm wafers, heat spreader uses in artificial intelligence data centers, and large renewable energy and storage buildouts in emerging markets.
The major growth factor is electric vehicle adoption, supported by renewable power and grid modernization that use silicon carbide inverters and converters.
The Black Silicon Carbide segment dominated the Silicon Carbide Market with approximately 53.48% share in 2025, because it is produced in large volumes at relatively low cost for abrasives, refractories and metallurgy.
Asia Pacific dominated the Silicon Carbide Market with a 51.24% share in 2025, driven by large grain production, fast electric vehicle output and extensive semiconductor manufacturing in China, Japan and South Korea.
