
Silver Wound Dressing Market Report Scope & Overview:
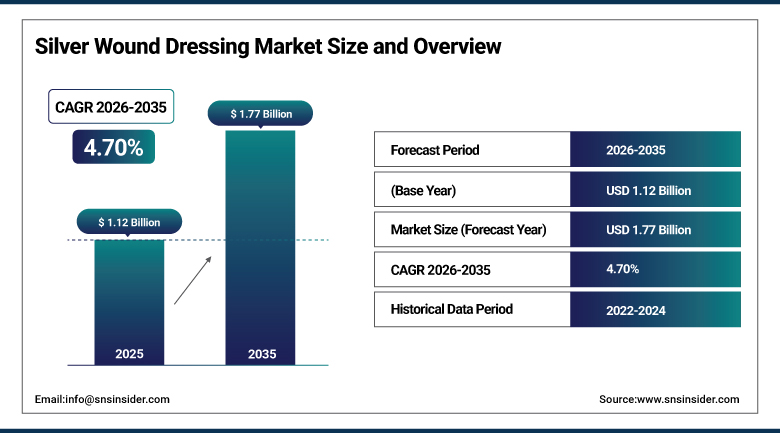
The Silver Wound Dressing Market was valued at USD 1.12 Billion in 2025 and is expected to reach USD 1.77 Billion by 2035, growing at a CAGR of 4.70% from 2026-2035.
The Silver Wound Dressing Market is expanding steadily as aging populations, diabetes and venous disease raise the number of chronic wounds, and as hospitals focus on preventing infection in burns, surgical wounds and ulcers. Silver is valued for broad-spectrum antimicrobial activity, and manufacturers incorporate it into alginate, foam, hydrofiber and nanocrystalline dressings that release silver ions in a controlled way. Growth is supported by advanced wound care adoption, expanding home healthcare, and clinical evidence that supports silver use in infected or at-risk wounds, although concerns about cytotoxicity and antibiotic stewardship encourage targeted use.
⮞In November 2024, Smith & Nephew launched a thinner silver alginate pad under its DURAFIBER brand. The launch shows how leading suppliers are refining established silver formats to improve patient comfort and ease of use in managing exudating wounds in hospitals and the community.
To Get more information Silver Wound Dressing Market - Request Free Sample Report
Silver Wound Dressing Market Trends
- Shift from traditional silver bandages toward advanced alginate, foam and hydrofiber dressings
- Rising use of nanocrystalline and nanoparticle silver for sustained antimicrobial release
- Combination dressings that add pain relief, antibiofilm or other active agents to silver
- Expansion of wound care in home healthcare settings
- Growing focus on antimicrobial stewardship and targeted use of silver
U.S. Silver Wound Dressing Market Outlook
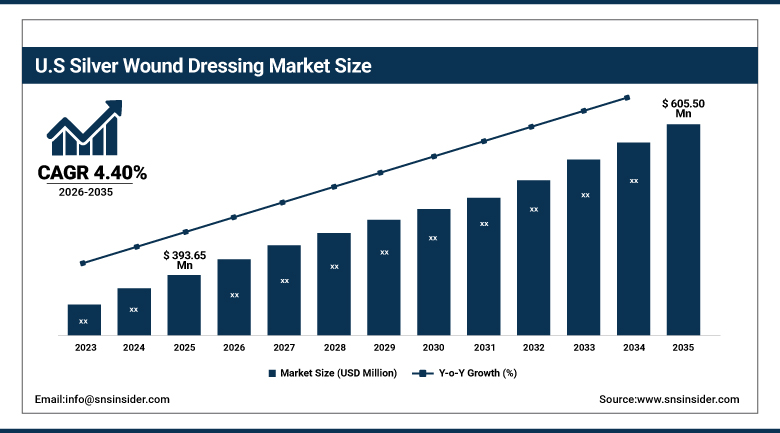
The U.S. Silver Wound Dressing Market was valued at USD 393.65 Million in 2025 and is expected to reach USD 605.50 Million by 2035, growing at a CAGR of 4.40% from 2026-2035.
The U.S. Silver Wound Dressing Market is supported by a large population with diabetes, venous disease and pressure injuries, extensive reimbursement for advanced wound care, a strong base of manufacturers and distributors, and demand for burn and surgical site infection management. Hospitals, long-term care facilities and home health agencies use silver dressings for infected or high-risk wounds, while military and emergency preparedness programs support demand for burn and trauma dressings. Growth is moderated by maturity and by scrutiny of silver use in uninfected wounds.
⮞In October 2024, Imbed Biosciences received FDA 510(k) clearance for Microlyte Ag/Lidocaine, described as the first antimicrobial wound dressing to integrate lidocaine. The clearance shows how U.S. developers are combining silver with pain relief to address both infection control and patient comfort during dressing changes.
Silver Wound Dressing Market Segment Analysis
- By Product Type, silver alginate segment dominated the Silver Wound Dressing Market in 2025 with 37.60% share; nanocrystalline silver segment is the fastest-growing segment, with an estimated CAGR of 10.10% during 2026–2035.
- By Wound Type, chronic wounds segment dominated the Silver Wound Dressing Market in 2025 with an estimated 58.00% share, and is also the fastest-growing segment, with an estimated CAGR of 5.40% during 2026–2035.
- By End User, hospitals segment dominated the Silver Wound Dressing Market in 2025 with 49.60% share; home healthcare segment is the fastest-growing segment, with an estimated CAGR of 8.00% during 2026–2035.
- By Distribution Channel, offline segment dominated the Silver Wound Dressing Market in 2025 with an estimated 83.00% share; online segment is the fastest-growing segment, with an estimated CAGR of 8.60% during 2026–2035.
By Product Type, Silver Alginate Dominates Silver Wound Dressing Market; Nanocrystalline Silver to Register Fastest Growth.
Silver alginate dressings dominate the Silver Wound Dressing Market because they combine high absorbency with antimicrobial protection, which suits moderately to heavily exuding chronic wounds, burns and surgical sites. The alginate fiber forms a gel on contact with exudate, maintaining a moist environment while silver ions act on bacteria, and clinicians value the familiarity and dependable performance of the format. Leading manufacturers continue to refine alginate pads and ropes, and established clinical guidelines for infected wounds sustain routine use across hospitals and community care.
Nanocrystalline silver is projected to register the fastest growth because its small particle size provides sustained release of silver ions and strong antimicrobial activity from thin, conformable dressings. Silver nanoparticle-embedded products are being developed to improve activity against biofilm while limiting the amount of silver delivered to tissue. Silver foams, hydrofiber and hydrogel dressings serve wounds with varying exudate levels, and traditional silver bandages and silver nitrate products remain in use where cost is a priority, although they are losing share to advanced dressings. Product launches focused on thinner, softer and longer-wear formats are expected to keep this segment innovative.
By Wound Type, Chronic Wounds Dominate Silver Wound Dressing Market and Are Also the Fastest-Growing Wound Type.
Chronic wounds dominate the Silver Wound Dressing Market because diabetic foot ulcers, venous leg ulcers and pressure injuries last for weeks or months and are prone to bacterial colonization and biofilm. Dressing changes recur frequently throughout the treatment period, so each patient consumes a large number of dressings. Rising prevalence of diabetes, obesity and vascular disease, together with population aging, expands the patient pool, and reimbursement for advanced wound care supports the use of antimicrobial products in difficult cases. Clinicians also favor them for long-term care residents.
Chronic wounds are also expected to be the fastest-growing wound type as health systems focus on preventing amputations and hospital readmissions, and as outpatient and home wound clinics expand. Acute wounds, including burns, surgical sites and traumatic injuries, remain a significant segment, supported by infection prevention protocols and by emergency preparedness programs for burn care. Some sources expect acute wounds to grow quickly from surgical volume recovery, but the higher frequency of dressing use makes chronic wounds the larger source of incremental demand. Dressing changes in these cases can be painful, so combination products add value.
By End User, Hospitals Dominate Silver Wound Dressing Market; Home Healthcare to Register Fastest Growth.
Hospitals dominate the Silver Wound Dressing Market because they treat burns, surgical wounds, severe ulcers and infected wounds that require antimicrobial dressings, and because wound care specialists there make product selection decisions. Procurement through group purchasing arrangements gives large suppliers an advantage, and inpatient stays for complex wounds add volume. Hospitals also generate demand through outpatient wound care centers, which provide debridement, compression and dressing changes under clinician supervision. Wound care nurses in hospital clinics also train patients and caregivers before discharge, which supports continued use of the same dressings at home.
Home healthcare is projected to register the fastest growth as payers and providers shift wound management out of hospitals to reduce cost and as patients prefer to recover at home. Home health nurses and trained caregivers apply dressings designed for longer wear times and easy removal, which favors alginate and hydrofiber formats with sustained silver release. Ambulatory surgical centers and clinics also grow with outpatient procedures, and telehealth tools that allow remote wound assessment are increasing confidence in care outside hospitals.
By Distribution Channel, Offline Dominates Silver Wound Dressing Market; Online to Register Fastest Growth.
Offline channels dominate the Silver Wound Dressing Market because most purchases are made by hospitals, long-term care facilities and clinics through direct contracts, distributors and hospital pharmacies. Clinical guidance is important when selecting an antimicrobial dressing, and institutional buyers value reliable supply, product training and contract pricing. Retail pharmacies also serve patients with prescriptions for dressings, with pharmacists advising on use and reimbursement. Wholesalers and specialty medical suppliers also extend reach to nursing homes and smaller clinics, offering product education, consignment stock and reliable delivery schedules that online sellers find hard to match.
Online channels are projected to register the fastest growth as home care patients and small clinics order dressings through e-commerce platforms and supplier portals. Digital ordering provides convenience, price transparency and subscription replenishment for patients with chronic wounds, and manufacturers are improving online educational content so that users select the right product. Regulatory requirements and the need for clinical advice limit online share in some countries, but growth in telehealth is expected to support channel expansion. Subscription programs are also emerging.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
82.70 |
|
Europe |
Germany |
32.00 |
|
Asia Pacific |
China |
36.00 |
|
Latin America |
Brazil |
48.00 |
|
Middle East & Africa |
Saudi Arabia |
30.00 |
North America Silver Wound Dressing Market Insights
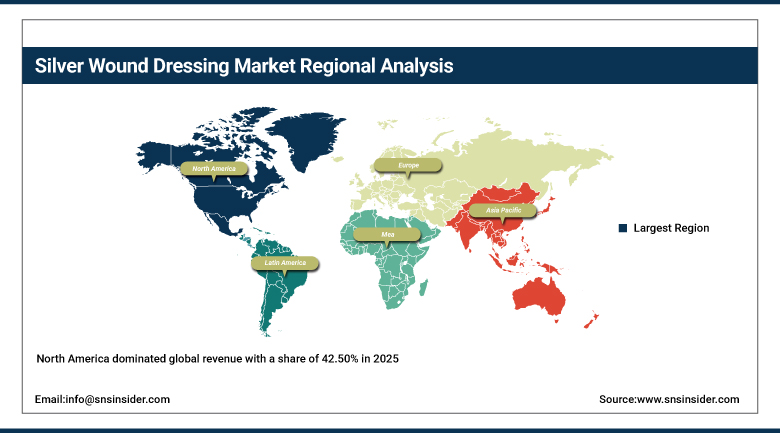
North America dominated global revenue with a share of 42.50% in 2025, supported by a large population with diabetes and chronic wounds, extensive reimbursement for advanced wound care and the presence of leading manufacturers such as 3M, Cardinal Health, Medline, Integra LifeSciences, Hollister and Ferris Mfg. The United States accounts for most regional demand, with Canada adding volume through provincial programs.
Bravida Medical's Silverlon received FDA clearance in September 2024 as the 93rd BARDA-supported medical countermeasure, reflecting government interest in burn and trauma dressings. In April 2024, 3M integrated a silver-impregnated negative-pressure kit with its V.A.C. therapy. Maturity and concerns over cost moderate growth, but demand for home wound care and infection prevention sustains steady expansion. Payers and accountable care organizations increasingly track amputation and readmission rates, which encourages providers to invest in effective infection prevention for diabetic foot ulcers and venous leg ulcers.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Silver Wound Dressing Market Insights
Germany, the United Kingdom and France account for nearly 70% of European shipments, and the region is home to major suppliers including Smith+Nephew, Mölnlycke Health Care, Coloplast, Convatec, B. Braun, Paul Hartmann, Lohmann & Rauscher, Urgo Medical and Advanced Medical Solutions. Strong wound care nursing networks and public reimbursement support use of advanced dressings. Aging populations in Italy, Spain and the Nordic countries add to the pool of patients with leg ulcers and pressure injuries.
Medical device regulation and health technology assessment bodies require clinical evidence for antimicrobial claims, and antimicrobial stewardship programs encourage targeted use of silver. Mölnlycke has installed a closed-loop silver-ion capture system at its plant in Finland, showing the attention paid to environmental management. Advanced Medical Solutions began a clinical trial of its Silver I Alginate Non-Woven Dressing in May 2023, and ConvaTec reported randomized controlled trial results for AQUACEL Ag+ Extra in venous leg ulcer healing in May 2024. Hospital tenders in several countries favor suppliers with documented evidence.
Asia Pacific Silver Wound Dressing Market Insights
Asia Pacific is projected to be the fastest-growing region, advancing at a CAGR of 5.80% from 2026-2035. China leads regional demand, followed by Japan, India, South Korea and Australia. Rising diabetes prevalence, expanding hospital capacity and growing awareness of advanced wound care drive adoption, and global suppliers are expanding distribution through local partners. Japan and South Korea contribute demand through aging populations and advanced hospital systems, while Australia's wound care clinics and Southeast Asian private hospitals are adopting imported silver products, supported by medical tourism and rising insurance coverage for chronic wound treatment.
India has a growing local manufacturing base, including companies such as Datt Mediproducts, which supply lower-cost dressings, while Japan and Australia have mature markets with strong clinical guidelines. Price sensitivity favors traditional dressings in some countries, but burn care investment, rising surgical volumes and greater reimbursement are expected to support a shift toward advanced silver products over the forecast period. Regional distributors are expanding cold chain-free, shelf-stable dressing supply into tier-two cities, and training programs for wound care nurses are improving appropriate product selection across public and private hospitals.
MEA & Latin America Silver Wound Dressing Market Insights
In Latin America, Brazil leads on the strength of its large hospital network and diabetic population, followed by Mexico, Argentina and Colombia. Public procurement and price pressures influence product choice, and multinational suppliers work through distributors to serve hospitals and clinics. Growth is supported by rising chronic disease prevalence and improved access to advanced wound care. Chile, Peru and Colombia contribute through expanding private hospital groups, and local distributors help international suppliers meet registration requirements and supply public tenders. Mexico also benefits from nearshore medical device manufacturing.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates and South Africa lead through investment in hospital infrastructure and treatment of burns and diabetic wounds. Import dependence, limited reimbursement and budget constraints restrict the use of premium silver dressings in many African markets, although donor programs and growing private healthcare create selective opportunities. Qatar and Kuwait invest in specialized burn and diabetes centers, while Nigeria and Kenya depend largely on imports through hospital procurement and non-governmental programs, so access to premium dressings varies widely across the region.
Market Dynamics
Growth Drivers: Chronic Wound Prevalence, Infection Control and Advanced Dressings
The rising prevalence of chronic wounds is the main driver of the Silver Wound Dressing Market. Diabetes, obesity, vascular disease and aging populations increase the number of patients with ulcers and pressure injuries, and these wounds are prone to infection and biofilm. Silver dressings give clinicians a practical option to reduce bacterial load, protect wounds between visits and support healing, particularly where systemic antibiotics are undesirable because of resistance concerns. Growth in the elderly population further widens the base of at-risk patients. Government programs for diabetic foot care and burn preparedness, along with growth in outpatient wound clinics, create a steady demand base for antimicrobial dressings across public and private providers.
Infection control priorities in hospitals add further demand. Surgical site infections and burn infections extend stays and raise costs, and many hospitals include silver dressings in protocols for high-risk wounds. Advanced dressings that combine antimicrobial action with high absorbency allow longer wear times and fewer changes, which reduces nursing time and supports adoption by payers seeking lower total cost of care. Greater clinician awareness of biofilm also supports demand for silver products that act against persistent bacterial communities in stalled wounds.
Restraints: Safety Concerns, Cost and Evidence Requirements
The concerns associated with the cytotoxicity, delayed healing in non-infected wounds, and emergence of silver resistance have led to guidelines recommending limited usage to wounds with signs of infections and those at high risks. Such guidelines restrict time-limited usage that means limited volumes per patient. The allergic response and staining are less frequent, but still are the factors causing caution. There is inconsistency among different countries’ guidelines, which raises uncertainties for manufacturers and physicians.
Silver dressings are more expensive than plain dressings, and payers in cost-conscious markets will restrict reimbursement to indications. Clinical evidence needs to be provided for antimicrobial effect, and the increased regulatory attention to product claims will increase costs. Competition from other antimicrobials, such as honey, iodine, polyhexanide, as well as new nitric oxide technologies, restrains the growth. Price pressure in commodity dressings limits premium prices possible for silver dressings in tenders. Antibiotic stewardship policies that are supportive of silver as an antibiotic alternative still restrain physicians from long-term use.
Opportunities: Combination Dressings, Home Care and Emerging Markets
Combination dressings that combine silver with pain relief, gallium, nitric oxide or other materials result in higher value and biofilm prevention, which is one of the major reasons for non-healing wounds. Imbed Biosciences has received regulatory clearance for a silver dressing with lidocaine and has been approved for a feasibility study of a matrix with silver and gallium ions, showing how the market evolves from a product perspective. Collaborations with wound clinics and academic institutions will help get the outcome data and make arguments to get reimbursement for these innovations.
Volume growth comes from home care and emerging markets. Combination dressings designed for patient self-management and remote monitoring will enable treating patients at home, while increased reimbursement opportunities and chronic diseases' rising prevalence in the Asia Pacific region, Latin America and the Middle East create new demand. Local production and training can enable building of business in such markets. Sustainable practices, such as silver reclamation and recyclable packaging, can be used by manufacturers to distinguish themselves from others when dealing with institutional customers. Remote wound imaging and monitoring tools combined with silver dressings can detect infections faster and enable treating patients at home.
Recent Developments:
- In September 2024, Bravida Medical's Silverlon received FDA clearance as the 93rd BARDA-supported medical countermeasure. The clearance supports the use of silver-based burn and wound dressings in emergency preparedness stockpiles.
- In May 2024, ConvaTec reported randomized controlled trial results for AQUACEL Ag+ Extra in venous leg ulcer healing. The data provide clinical evidence supporting the use of its silver hydrofiber dressing in chronic wounds.
- In April 2024, 3M integrated a silver-impregnated negative-pressure kit with its V.A.C. therapy. The integration combines antimicrobial protection with negative pressure wound therapy for complex wounds.
- In May 2023, Advanced Medical Solutions began a clinical trial of its Silver I Alginate Non-Woven Dressing. The trial is intended to generate clinical data supporting its silver alginate product line.
Silver Wound Dressing Market Key Players are:
- 3M Company
- Smith & Nephew plc
- Mölnlycke Health Care AB
- ConvaTec Group plc
- Coloplast A/S
- Cardinal Health, Inc.
- B. Braun Melsungen AG
- Integra LifeSciences
- Medline Industries, LP
- Advanced Medical Solutions Group plc
- Hollister Incorporated
- PAUL HARTMANN AG
- Lohmann & Rauscher
- URGO Medical
- Ferris Mfg. Corp.
- Bravida Medical
- Imbed Biosciences, Inc.
- DermaRite Industries, LLC
- Datt Mediproducts Private Limited
- Baxter International Inc.
Silver Wound Dressing Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.12 Billion |
| Market Size by 2035 | USD 1.77 Billion |
| CAGR | CAGR of 4.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Silver Alginate, Silver Foam, Hydrofiber and Hydrogel, Nanocrystalline Silver, Silver Bandages, and Others) • By Wound Type (Chronic Wounds and Acute Wounds) • By End User (Hospitals, Ambulatory Surgical Centers and Clinics, and Home Healthcare) • By Distribution Channel (Offline and Online) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | 3M Company; Smith & Nephew plc; Mölnlycke Health Care AB; ConvaTec Group plc; Coloplast A/S; Cardinal Health, Inc.; B. Braun Melsungen AG; Integra LifeSciences; Medline Industries, LP; Advanced Medical Solutions Group plc; Hollister Incorporated; PAUL HARTMANN AG; Lohmann & Rauscher; URGO Medical; Ferris Mfg. Corp.; Bravida Medical; Imbed Biosciences, Inc.; DermaRite Industries, LLC; Datt Mediproducts Private Limited; Baxter International Inc. |

Frequently Asked Questions
Key players include 3M Company, Smith & Nephew plc, Mölnlycke Health Care AB, ConvaTec Group plc, Coloplast A/S, Cardinal Health, B. Braun Melsungen AG and Integra LifeSciences.
Key opportunities include combination dressings that integrate silver with pain relief or other agents, home wound care, and expansion in Asia Pacific and other emerging regions.
The major growth factor is the rising prevalence of chronic wounds, driven by diabetes and aging, together with hospital priorities for preventing infection.
By Product Type, the Silver Alginate segment dominated the market in 2025, supported by high absorbency and dependable antimicrobial performance in exuding wounds.
North America dominated the market with a share of 42.50% in 2025, driven by chronic wound prevalence, reimbursement and the presence of leading manufacturers.
