
Slurry Oil Market Report Scope & Overview:
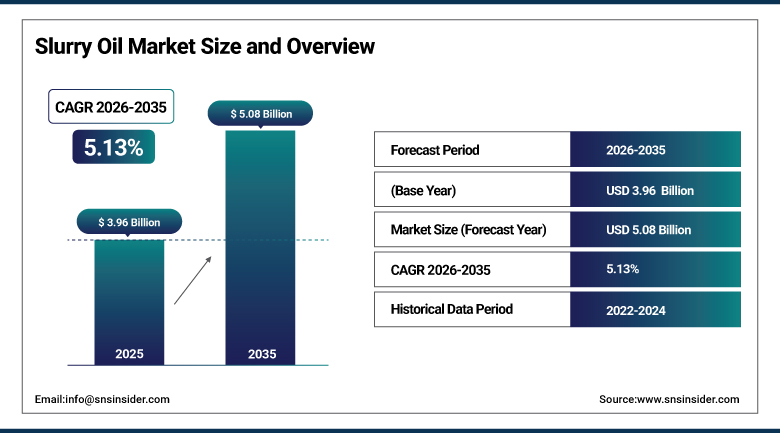
The Slurry Oil Market was valued at approximately USD 3.96 Billion in 2025 and is projected to reach USD 5.08 Billion by 2035, growing at an estimated CAGR of 5.13% during 2026–2035.
The Slurry Oil market is growing due to the need for higher value uses of heavy aromatic residues from fluid catalytic cracking plants and also since carbon black manufacturers, needle coke, and graphite manufacturers need a feedstock source. Slurry oil is also referred to as decant oil or clarified slurry oil and it has polycyclic aromatic hydrocarbons that make it ideal for use as carbon black for tires and rubber products and needle coke for graphite electrodes and battery anodes. The increased manufacturing of vehicles and tires means that carbon black feedstock will continue to be consumed. The increased production of electric arc furnaces means that more graphite electrodes are needed, and the increased production of electric vehicle and energy storage batteries means there is a demand for synthetic graphite anode.
⮞Alternative feedstock blending in carbon black production advanced when Orion began, in June 2026, producing circular carbon black at its ISCC PLUS-certified plant in Qingdao, China, using tire pyrolysis oil fed as a separate stream alongside carbon black oil to launch three ECORAX Circular grades.
To Get more information Slurry Oil Market - Request Free Sample Report
Slurry Oil Market Trends
-
Rising use of slurry oil as feedstock for needle coke in battery anode materials.
-
Growing demand for carbon black feedstock from tire and rubber manufacturers.
-
Expanding refinery investment in catalyst fines removal and slurry oil upgrading.
-
Increasing blending of slurry oil with alternative feedstocks such as tire pyrolysis oil.
-
Rising electric arc furnace steelmaking supporting graphite electrode demand.
-
Growing focus on low-sulfur slurry oil grades for fuel and specialty applications.
U.S. Slurry Oil Market Outlook
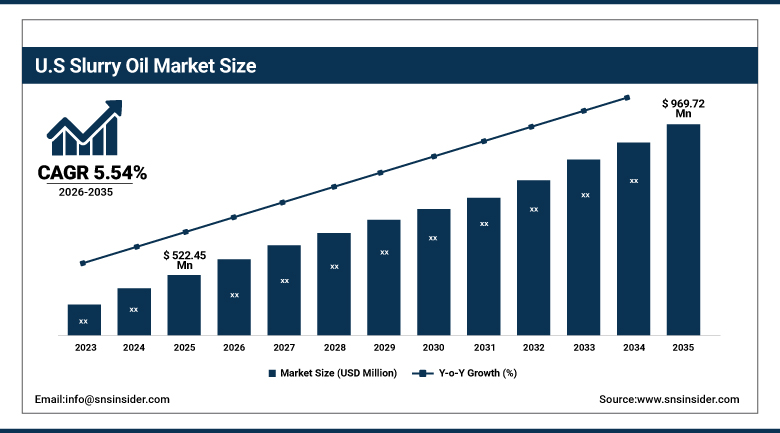
The U.S. Slurry Oil Market was valued at USD 522.45 Million in 2025 and is expected to reach USD 969.72 Million by 2035, growing at a CAGR of 6.38% from 2026-2035.
The U.S. Slurry Oil Market is expanding due to its solid refinery fluid catalytic cracking capacity base, robust carbon black production, and investments into synthetic graphite supply chains. Slurry oil is produced by refineries located on the Gulf Coast in Texas and Louisiana and delivered to carbon black plants belonging to such companies as Cabot, Orion, Birla Carbon, and Continental Carbon. Needle coke and anode-grade coke are produced from carefully selected decant oils by Phillips 66 and other refiners for graphite electrodes and batteries anodes manufacturers. Favorable federal policies aimed at the development of the U.S. domestic battery material production market together with ant-dumping duties imposed on Chinese anode-grade graphite contribute to the development of anode plants that rely on coke produced out of petroleum products. Increased electric arc furnace steel production leads to higher graphite electrode demand.
⮞Synthetic graphite supply chains in the United States advanced when Epsilon Advanced Materials signed, in September 2025, an agreement with Phillips 66 to source anode-grade green petroleum coke and calcined needle coke from the Lake Charles refinery in Louisiana for its planned 30,000 t/yr graphite anode plant in North Carolina.
Slurry Oil Market Segment Analysis
-
By Source, the FCC Unit segment dominated the Slurry Oil Market with approximately 72.48% share in 2025, while the RFCC Unit segment is the fastest growing with a CAGR of approximately 7.64%.
-
By Sulfur Content, the High Sulfur segment dominated the Slurry Oil Market with approximately 58.24% share in 2025, while the Low Sulfur segment is the fastest growing with a CAGR of approximately 7.86%.
-
By Application, the Carbon Black Feedstock segment dominated the Slurry Oil Market with approximately 46.82% share in 2025, while the Needle Coke Production segment is the fastest growing with a CAGR of approximately 8.94%.
-
By End-Use Industry, the Tire & Rubber segment dominated the Slurry Oil Market with approximately 44.36% share in 2025, while the Battery Anode Materials segment is the fastest growing with a CAGR of approximately 11.42%.
By Source, FCC Unit Dominates the Slurry Oil Market and RFCC Unit Grows Fastest
FCC units led the market in 2025, given that fluid catalytic cracking is one of the most common conversion technologies used in refineries all around the world, generating gasoline, diesel, and light olefins from vacuum gas oil. Slurry oil is the heaviest oil that can be extracted from the FCC main fractionator and usually constitutes a small percentage of total unit capacity but still amounts to a considerable quantity on the worldwide refining system. Hundreds of FCC units operate in the U.S., Europe, and Asia and provide sufficient slurry oil.
RFCC units are the fastest-growing source as refiners in Asia and the Middle East build residue fluid catalytic cracking capacity to convert heavier crude fractions into higher-value products. These units are also increasingly common in new refining projects. RFCC units process atmospheric residue and other heavy feeds, often producing larger volumes of slurry oil with different aromatic and metals profiles. New integrated refining and petrochemical complexes in China, India, and the Middle East frequently include RFCC units to maximize propylene and gasoline output. Rising investment in residue upgrading capacity and integrated petrochemical complexes continues to drive the fastest growth in this source segment over the forecast period.
⮞October 2026: Valero Energy completed a USD 230 million fluid catalytic cracking unit optimization project at its St. Charles refinery in Louisiana. The upgrade increased FCC throughput capacity by 15,000 barrels per day, illustrating continued investment in refinery conversion infrastructure.
By Sulfur Content, High Sulfur Dominates the Slurry Oil Market and Low Sulfur Grows Fastest
High sulfur slurry oil led the market in 2025, as many refineries process medium and heavy sour crudes that produce FCC residues with elevated sulfur content. Sour crude processing remains common in many large refining centers. High sulfur grades are widely used as carbon black feedstock, where sulfur content is managed through blending and emissions control at carbon black plants. They are also used in industrial fuel applications and blended into heavy fuel oil where regulations allow. The large volume of sour crude processed globally, particularly in the United States Gulf Coast, the Middle East, and Asia, continues to secure high sulfur grades as the largest segment.
Low sulfur slurry oil is the fastest-growing segment as needle coke producers, specialty carbon black manufacturers, and marine fuel blenders seek cleaner feedstocks. Low sulfur grades often command a premium over standard slurry oil. Premium needle coke for graphite electrodes and battery anodes requires low sulfur and low metals content to achieve desired crystalline structure and performance. The International Maritime Organization's 0.50% sulfur limit has increased the value of low sulfur components for compliant fuel blending. Refiners processing sweet crudes or using hydrotreated FCC feeds are capturing premium pricing. Rising demand for high-quality feedstocks continues to drive the fastest growth in the low sulfur segment.
⮞October 2026: Valero completed its St. Charles FCC unit optimization project, designed to increase throughput and improve the refinery’s production of higher-value petroleum products. The development reflects ongoing refinery investment in conversion capacity; the announcement did not specify a change in slurry oil sulfur content
By Application, Carbon Black Feedstock Dominates the Slurry Oil Market and Needle Coke Production Grows Fastest
Carbon black feedstock led the market in 2025, as slurry oil's high aromatic content and carbon-to-hydrogen ratio make it an efficient raw material for furnace black production. These producers often secure supply through long-term contracts with refiners. Carbon black manufacturers including Cabot, Orion, Birla Carbon, Tokai Carbon, and PCBL purchase large volumes of slurry oil and blend it with coal tar and ethylene cracker residues. Carbon black is used primarily in tires, mechanical rubber goods, plastics, coatings, and inks. Steady growth in vehicle production, tire replacement, and industrial rubber demand continues to secure carbon black feedstock as the largest application segment in the slurry oil market.
Needle coke production is the fastest-growing application as demand rises for graphite electrodes used in electric arc furnace steelmaking and for synthetic graphite anodes used in lithium-ion batteries. Premium coke grades command significantly higher prices than standard fuel-grade products. Petroleum-based needle coke is produced from carefully selected low sulfur, highly aromatic decant oils through delayed coking and calcination. Phillips 66, ENEOS, Sinopec, and other producers supply needle coke to graphite manufacturers worldwide. New anode material plants in the United States, Europe, and India are seeking reliable feedstock supplies. Rapid growth in electric vehicles and energy storage continues to drive the fastest growth among application segments in the market.
⮞September 2026: NextSource Materials signed a binding agreement with Japan’s Hanwa and JOGMEC for a planned USD 30 million investment in its UAE battery anode facility. Phase 1 is designed for approximately 14,000 tonnes per year of anode material, with ramp-up expected to begin in the second half of 2027.
By End-Use Industry, Tire & Rubber Dominates the Slurry Oil Market and Battery Anode Materials Grows Fastest
The tire and rubber industry led the market in 2025, as carbon black produced from slurry oil is an essential reinforcing filler in passenger, commercial, and off-road tires. Carbon black also improves the electrical properties of rubber. Each tire contains a significant share of carbon black by weight, providing strength, abrasion resistance, and durability. Mechanical rubber goods such as belts, hoses, and seals add further demand. Rising vehicle ownership in Asia, Latin America, and Africa, along with steady replacement tire demand worldwide, supports consistent consumption. The scale of global tire production continues to secure tire and rubber as the largest end-use industry segment in the slurry oil market.
Battery anode materials are the fastest-growing end-use industry as synthetic graphite becomes the dominant anode material in lithium-ion batteries for electric vehicles and energy storage. Synthetic graphite offers consistent quality and long cycle life in battery cells. Synthetic graphite is produced from needle coke and other petroleum cokes derived from selected slurry oils. Governments in the United States, Europe, and India are supporting local anode material production to reduce dependence on Chinese supply, creating demand for non-Chinese coke feedstocks. Companies such as Epsilon Advanced Materials are building new anode plants. Rising battery production continues to drive the fastest growth among end-use industry segments in the market.
⮞September 2026: NextSource Materials secured a binding agreement for a USD 30 million strategic investment from Hanwa and JOGMEC in its planned UAE battery anode facility. The project is intended to diversify battery-material supply chains, with a multi-year offtake agreement supporting the planned production of anode materials.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.48% |
|
Asia Pacific |
China |
46.82% |
|
Europe |
Germany |
22.64% |
|
Latin America |
Brazil |
48.36% |
|
Middle East & Africa |
Saudi Arabia |
38.24% |
North America Slurry Oil Market Insights
North America accounted for approximately 24.36% of the global Slurry Oil Market in 2025, supported by one of the world's largest fluid catalytic cracking refining bases and strong carbon black and needle coke production. Carbon black producers in the region often secure feedstock through long-term refinery contracts. Refineries operated by ExxonMobil, Valero, Marathon Petroleum, Phillips 66, Chevron, and Shell along the Gulf Coast produce large volumes of slurry oil, much of which supplies regional carbon black plants. Phillips 66's needle coke operations make the region an important source of premium coke for graphite electrodes and battery anode materials, supported by growing investment in local battery supply chains.
The United States anchors regional demand through carbon black plants in Texas, Louisiana, Oklahoma, and other states, along with exports of slurry oil to carbon black and fuel blending markets in Asia, Europe, and Latin America. Export cargoes are typically shipped from Gulf Coast terminals. Canada contributes through refineries in Alberta and Ontario that supply carbon black and industrial fuel markets. Mexico's refineries produce slurry oil for regional use. Growing investment in synthetic graphite anode plants, supported by federal battery material incentives and trade measures, is expected to increase demand for premium coke feedstocks and support steady regional growth over the forecast period.
⮞October 2026: Valero Energy completed a USD 230 million FCC unit optimization project at its St. Charles refinery in Louisiana, increasing throughput capacity by 15,000 barrels per day. The investment demonstrates continued modernization of U.S. refining infrastructure and conversion capacity.
Europe Slurry Oil Market Insights
Europe holds a significant share of the Slurry Oil Market, supported by an established refining base and carbon black production serving the region's automotive and tire industries. European carbon black producers also emphasize specialty grades for plastics, coatings, and batteries. Germany is the largest country market, with strong tire, rubber goods, and specialty carbon black demand from manufacturers serving European automakers. Refineries operated by Shell, TotalEnergies, BP, Repsol, and ExxonMobil produce slurry oil for carbon black plants operated by Orion, Cabot, and Birla Carbon in Germany, Italy, Hungary, Spain, and other countries, while graphite electrode producers source needle coke for steel applications.
Europe is also investing in battery anode material production to support its growing electric vehicle and battery industry, creating new demand for needle coke and other petroleum-based coke feedstocks. Several European projects are also testing bio-based and circular carbon black feedstocks. Refinery closures and conversions in some countries are tightening regional slurry oil supply, increasing imports from the United States and the Middle East. The EU Emissions Trading System and sustainability requirements are encouraging carbon black producers to adopt circular and lower-carbon feedstocks. Despite these supply changes, steady tire demand and emerging battery material projects are expected to support stable growth in Europe over the forecast period.
⮞June 2026: Orion began commercial production of three circular carbon black grades at its ISCC PLUS-certified facility in Qingdao, China, using tire pyrolysis oil alongside conventional carbon black oil. The development follows the company’s earlier expansion of circular carbon black production at its Jasło facility in Poland.
Asia Pacific Slurry Oil Market Insights
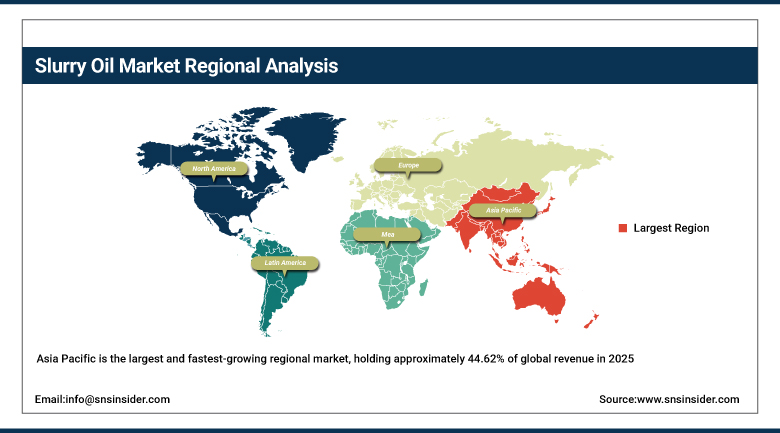
Asia Pacific is the largest and fastest-growing regional market, holding approximately 44.62% of global revenue in 2025 and expanding at a CAGR of approximately 7.42% from 2026 to 2035. Chinese carbon black and needle coke producers continue to add capacity to serve regional and export customers. The region's leadership reflects China's position as the world's largest producer of carbon black, needle coke, graphite electrodes, and synthetic graphite anodes. Chinese refiners including Sinopec and PetroChina, along with independent refiners, produce large volumes of slurry oil, while China also imports slurry oil to meet strong demand from carbon black and needle coke producers serving the tire and battery industries.
India is a major growth contributor, supported by expanding refining capacity at Reliance Industries, Indian Oil, and Hindustan Petroleum, along with growing carbon black production by PCBL, Birla Carbon, and Himadri. Southeast Asian refiners also supply regional carbon black plants. India's rising vehicle production and plans for local battery material manufacturing add further demand. Japan and South Korea contribute through refiners such as ENEOS and SK Energy, which supply needle coke and carbon black feedstocks. Thailand and Indonesia host growing carbon black capacity. Rapid industrial growth, expanding tire production, and battery manufacturing across the region are expected to keep Asia Pacific the largest and fastest-growing market.
⮞October 2026: BKT completed a carbon black expansion at its Bhuj facility in India, raising annual capacity to 360,000 tonnes. The company also expanded associated power generation capacity from 40 MW to 64 MW, supporting its wider tire manufacturing growth plans.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Slurry Oil Market Insights
The Middle East & Africa represents a growing market, led by Saudi Arabia, the United Arab Emirates, Kuwait, and South Africa. Several refiners in the region are also exploring export opportunities to Asian buyers. Large new refineries and integrated petrochemical complexes in the Gulf region, including RFCC units, are increasing slurry oil production for export and regional use. Saudi Aramco and other national oil companies are evaluating higher-value uses for heavy refinery streams, including carbon black and coke production. South Africa's refining and carbon black industries support regional tire manufacturing, while growing industrial activity across the region is creating additional demand.
Latin America is developing steadily, supported by Brazil, Mexico, Argentina, and Colombia. Regional refiners are also upgrading units to improve product yields. Brazil's Petrobras operates several FCC units that produce slurry oil for carbon black plants supplying the country's tire and automotive industries. Mexico's refineries supply regional carbon black and fuel blending markets, while Colombia hosts carbon black production serving Andean and Central American customers. Argentina's refining sector supports local rubber goods and industrial fuel demand. Rising vehicle ownership, tire production, and industrial activity across the region are expected to support steady growth in slurry oil demand across both regions over the forecast period.
⮞September 2026: NextSource Materials signed a binding agreement with Hanwa and JOGMEC for a USD 30 million strategic investment in its planned battery anode facility in Abu Dhabi. The facility is designed to produce approximately 14,000 tonnes of anode material annually in its first phase, with ramp-up expected from the second half of 2027.
⮞October 2026: Brazil’s Petrobras and other regional refiners remain relevant to the slurry oil supply chain through FCC-based refinery operations. However, I could not verify a sufficiently specific, recent Brazil-based slurry oil development from the sources reviewed, so a new event is not asserted here.
Market Dynamics
Growth Drivers: Rising Carbon Black Demand from Tire Production and Growing Needle Coke Demand for Graphite Electrodes and Battery Anodes
Rising carbon black demand from tire production represents the primary driver of Slurry Oil Market growth, as carbon black remains the most important reinforcing filler in tires and rubber goods. Asian carbon black capacity additions are expected to continue. Global vehicle production, expanding vehicle fleets in emerging economies, and steady replacement tire demand support consistent carbon black consumption. Electric vehicles require durable tires that can handle higher weight and torque, supporting demand for high-performance carbon black grades. Carbon black producers depend on slurry oil as a key aromatic feedstock, and new carbon black capacity in India, Thailand, and other Asian markets continues to expand feedstock demand.
Growing needle coke demand for graphite electrodes and battery anodes is further strengthening market growth, as electric arc furnace steelmaking expands and lithium-ion battery production accelerates. Demand for battery-grade graphite is expected to grow strongly over the next decade. Graphite electrodes made from needle coke are essential consumables in electric arc furnaces, which are gaining share as steelmakers decarbonize. Synthetic graphite anodes, produced from needle coke and other petroleum cokes, are widely used in electric vehicle and energy storage batteries. Governments promoting local battery supply chains are encouraging new anode material plants outside China, increasing demand for premium slurry oil feedstocks from refiners worldwide.
⮞October 2026: BKT completed its carbon black capacity expansion in India, increasing annual production capacity by 95,000 tonnes to 360,000 tonnes. The investment is intended to support the company’s tire manufacturing expansion, illustrating continued investment across the tire and carbon black value chain.
Restraints: Feedstock Quality Variability and Environmental and Emissions Regulations
Feedstock quality variability remains a key restraint on the Slurry Oil Market, as slurry oil composition varies widely depending on crude oil type, FCC operating conditions, and catalyst performance. Feedstock testing and certification also add cost for producers and buyers. Catalyst fines, sulfur, metals, and asphaltene content affect suitability for carbon black and needle coke production. Only a small share of global slurry oil meets the strict specifications required for premium needle coke. Producers must invest in filtration, testing, and blending to achieve consistent quality. These challenges can limit supply of high-grade feedstocks and create price differences between premium and standard slurry oil grades.
Environmental and emissions regulations further restrain market growth, as slurry oil contains polycyclic aromatic hydrocarbons and sulfur compounds that face increasing scrutiny. Stricter health and safety rules for handling aromatic oils may also increase operating costs. Carbon black plants must meet strict air emissions standards for sulfur dioxide, nitrogen oxides, and particulate matter, requiring costly control equipment. The International Maritime Organization's sulfur limits have reduced the use of high sulfur slurry oil in marine fuel blending. Refinery closures and conversions to renewable fuels in Europe and North America may reduce regional supply. These factors can increase compliance costs and constrain growth in certain applications.
Opportunities: Synthetic Graphite Anode Supply Chain Localization and Slurry Oil Upgrading and Specialty Carbon Materials
Synthetic graphite anode supply chain localization presents significant opportunities for the Slurry Oil Market, as the United States, Europe, India, Japan, and South Korea seek to reduce dependence on Chinese graphite anode materials. Premium feedstock suppliers can also benefit from rising prices for battery-grade coke. New anode plants require reliable supplies of needle coke and anode-grade coke derived from suitable slurry oils. Refiners that can produce premium low sulfur decant oils or partner with coke and anode producers can capture higher margins. Long-term supply agreements, such as those between refiners and anode developers, are creating stable demand and encouraging investment in feedstock quality improvements.
Slurry oil upgrading and specialty carbon materials present a further opportunity, as refiners and chemical companies develop technologies to convert slurry oil into higher-value products such as mesophase pitch, carbon fiber precursors, and specialty carbon blacks. Research partnerships between refiners and universities are also exploring new carbon materials from heavy aromatic oils. Advanced filtration and hydrotreating can remove catalyst fines and sulfur, broadening the range of applications. Carbon fiber demand from aerospace, wind energy, and automotive lightweighting supports interest in pitch-based precursors. Companies that combine refinery integration with carbon materials expertise can unlock new revenue streams from a traditionally low-value refinery byproduct.
⮞September 2026: NextSource Materials signed a binding agreement with Hanwa and JOGMEC for a planned USD 30 million investment in its UAE battery anode facility. The project aims to establish an alternative supply source for battery anode materials, creating potential demand for suitable petroleum-based coke and other carbon feedstocks.
Recent Developments:
-
February 2026 – Marathon Petroleum Corporation reported strong refining performance for 2025, with annual refining utilization reaching 94%. The company also announced additional refinery optimization investments at its Garyville and El Paso facilities, including feedstock optimization and fluid catalytic cracker upgrades. These developments support refining efficiency and product-yield optimization, although the announcement does not specifically confirm a new slurry oil product.
-
April 2026 – Valero Energy Corporation reported progress on a USD 230 million fluid catalytic cracking (FCC) unit optimization project at its St. Charles refinery, expected to begin operations in the third quarter of 2026. As slurry oil is a residual stream associated with FCC operations, the project is relevant to refinery process optimization, but Valero has not stated that it will increase slurry oil production specifically.
Slurry Oil Market Key Players
-
Exxon Mobil Corporation
-
Shell plc
-
BP p.l.c.
-
Chevron Corporation
-
Phillips 66
-
Valero Energy Corporation
-
Marathon Petroleum Corporation
-
TotalEnergies SE
-
China Petroleum & Chemical Corporation (Sinopec)
-
PetroChina Company Limited
-
Saudi Arabian Oil Company (Saudi Aramco)
-
Reliance Industries Limited
-
Indian Oil Corporation Limited
-
Hindustan Petroleum Corporation Limited
-
Petróleo Brasileiro S.A. (Petrobras)
-
Repsol S.A.
-
PETRONAS
-
SK Energy Co., Ltd.
-
ENEOS Holdings, Inc.
-
Idemitsu Kosan Co., Ltd.
Slurry Oil Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.96 Billion |
| Market Size by 2035 | USD 4.81 Billion |
| CAGR | 6.84% from 2026-2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source: Dominant – FCC Unit (72.48% share in 2025); Fastest-Growing – RFCC Unit (CAGR 7.64%) • By Sulfur Content: Dominant – High Sulfur (58.24% share in 2025); Fastest-Growing – Low Sulfur (CAGR 7.86%) • By Application: Dominant – Carbon Black Feedstock (46.82% share in 2025); Fastest-Growing – Needle Coke Production (CAGR 8.94%) • By End-Use Industry: Dominant – Tire & Rubber (44.36% share in 2025); Fastest-Growing – Battery Anode Materials (CAGR 11.42%) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Exxon Mobil Corporation, Shell plc, BP p.l.c., Chevron Corporation, Phillips 66, Valero Energy Corporation, Marathon Petroleum Corporation, TotalEnergies SE, China Petroleum & Chemical Corporation (Sinopec), PetroChina Company Limited, Saudi Arabian Oil Company (Saudi Aramco), Reliance Industries Limited, Indian Oil Corporation Limited, Hindustan Petroleum Corporation Limited, Petróleo Brasileiro S.A. (Petrobras), Repsol S.A., PETRONAS, SK Energy Co., Ltd., ENEOS Holdings, Inc., Idemitsu Kosan Co., Ltd. |

Frequently Asked Questions
Key players include Exxon Mobil Corporation, Shell plc, BP p.l.c., Chevron Corporation, Phillips 66, Valero Energy Corporation, and Sinopec, among other global refiners.
Synthetic graphite anode supply chain localization, along with slurry oil upgrading and specialty carbon materials, represent the primary opportunities.
Growth is primarily driven by rising carbon black demand from tire production combined with growing needle coke demand for graphite electrodes and battery anodes.
By Application, Carbon Black Feedstock dominated the market with approximately 46.82% share in 2025, reflecting slurry oil's role as a key aromatic feedstock for tire-grade carbon black.
Asia Pacific dominated the market with approximately 44.62% share in 2025, driven by China's leadership in carbon black, needle coke, and graphite anode production.
