
Smart Home Automation Market Report Scope & Overview:
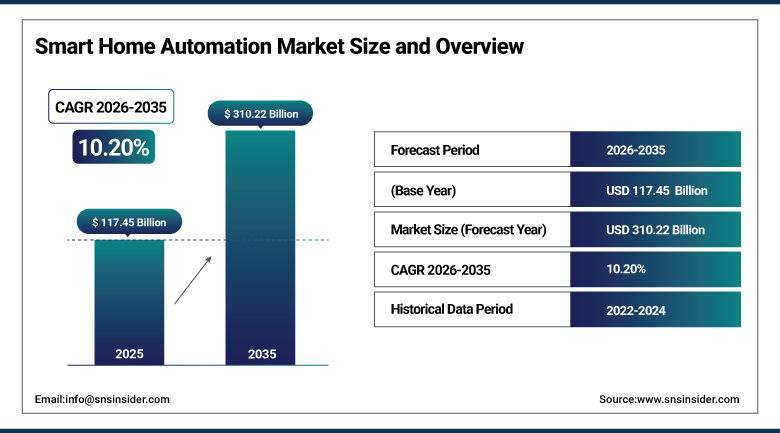
The Smart Home Automation Market was valued at USD 117.45 Billion in 2025 and is expected to reach USD 310.22 Billion by 2035, growing at a CAGR of 10.20% from 2026-2035.
The Smart Home Automation Market covers connected devices, hubs, sensors, controllers, software and services that let households control lighting, climate, security, entertainment and appliances automatically or by voice and app. Systems range from single smart speakers and plugs to whole-home platforms installed in new houses. Growth is supported by rising broadband and smartphone use, interest in energy saving and home security, voice assistants and artificial intelligence, and open standards such as Matter, while privacy concerns, device incompatibility and installation cost shape adoption.
⮞On August 20, 2026, the Broadband Forum released TR-517, the MatterService Data Model for USP Enabled Devices, also called the Matter Service API. It gives service providers a view of all Matter-powered devices on a home network, regardless of manufacturer, through broadband gateways, routers and smart home hubs, and supports diagnostics, automation and energy management.
To Get more information Smart Home Automation Market - Request Free Sample Report
Smart Home Automation Market Trends
-
Adoption of the Matter standard to connect devices from different brands
-
Use of generative artificial intelligence in voice assistants and home hubs
-
Growth of energy management, smart thermostats and solar-linked home systems
-
Shift from standalone gadgets to bundled whole-home subscription services
-
Rising retrofit and do-it-yourself installations through online channels
-
Integration of home devices with electric vehicles and utility demand programs
U.S. Smart Home Automation Market Outlook
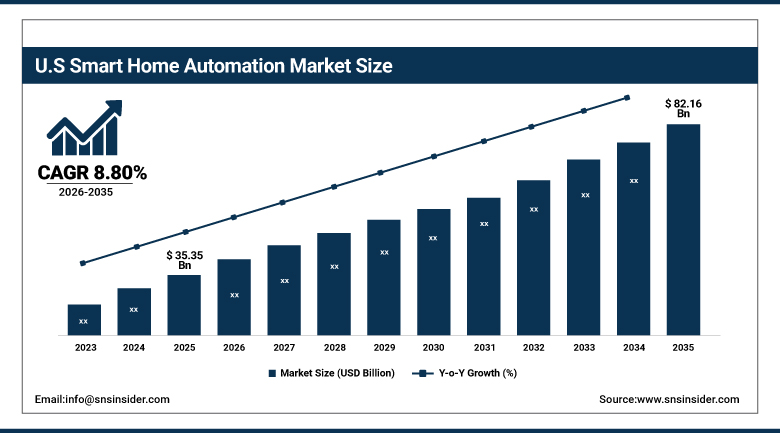
The U.S. Smart Home Automation Market was valued at USD 35.35 Billion in 2025 and is expected to reach USD 82.16 Billion by 2035, growing at a CAGR of 8.80% from 2026-2035.
The U.S. Smart Home Automation Market is the largest national market, supported by high broadband and smartphone use, high home ownership among higher-income households, and the presence of leading platform companies. Security cameras, doorbells, thermostats, smart speakers and lighting are widely sold through online and big-box retail, while professional installers serve high-end homes. Growth is moderated by market maturity, price sensitivity, privacy concerns and the need to replace devices that do not work across ecosystems.
⮞On September 16, 2026, Google began early access to its Google Home MCP server, which lets agents that support the Model Context Protocol read device event history and control Google Home and Matter devices through natural language. Access is limited to U.S. subscribers of the Google Home Premium Advanced tier.
Smart Home Automation Market Segment Analysis
-
By Product, entertainment and media devices segment dominated the Smart Home Automation Market in 2025 with an estimated 26.00% share; HVAC and energy management segment is the fastest-growing segment, with an estimated CAGR of 12.00% during 2026–2035.
-
By Technology, Wi-Fi segment dominated the Smart Home Automation Market in 2025 with an estimated 38.00% share; Matter segment is the fastest-growing segment, with an estimated CAGR of 17.50% during 2026–2035.
-
By Installation Type, retrofit segment dominated the Smart Home Automation Market in 2025 with an estimated 61.00% share; new construction segment is the fastest-growing segment, with an estimated CAGR of 11.60% during 2026–2035.
-
By Sales Channel, online segment dominated the Smart Home Automation Market in 2025 with an estimated 53.00% share, and is also the fastest-growing segment, with an estimated CAGR of 11.30% during 2026–2035.
By Product, Entertainment and Media Devices Dominates Smart Home Automation Market; HVAC and Energy Management to Register Fastest Growth.
Entertainment and media devices dominate the Smart Home Automation Market because smart speakers, displays, televisions and streaming devices are the most common first purchase for households and are replaced on short cycles. These products are sold widely at modest prices, serve as control points for other devices, and are tied to voice assistants from large platform companies. Their reach into many homes creates an installed base for later sales of lighting, locks and sensors. Sales of replacement devices keep revenue steady even in mature markets, and software updates extend useful life.
HVAC and energy management is projected to register the fastest growth because rising power prices, building efficiency rules and electrification make connected thermostats, heat pump controls and energy monitors attractive. Utilities offer rebates and demand response programs, while solar and battery owners need systems to shift loads automatically. Manufacturers of heating and cooling equipment are adding connectivity to new units, and AI scheduling tools promise visible savings that help justify the purchase. Heat pump makers, utilities and device suppliers are also cooperating on open interfaces to make control easier.
By Technology, Wi-Fi Dominates Smart Home Automation Market; Matter to Register Fastest Growth.
Wi-Fi dominates the Smart Home Automation Market because nearly every home already has a router, and Wi-Fi devices connect directly to the internet without a separate hub. Cameras, speakers, plugs, bulbs and appliances widely use Wi-Fi modules, which are low in cost and supported by large chip suppliers. Ease of setup through a smartphone app makes Wi-Fi the default for first-time buyers, even though battery-powered sensors often prefer lower power radios. Chip suppliers also ship ready modules that cut development time for new brands entering the market.
Matter is projected to register the fastest growth as major platform companies and device makers certify products under the Matter standard, which works across ecosystems from Amazon, Apple, Google and Samsung. Consumers gain freedom to mix brands, and installers gain simpler projects, which reduces a long-standing barrier to adoption. Certification programs and test labs also help new products reach shelves with fewer compatibility problems.
By Installation Type, Retrofit Dominates Smart Home Automation Market; New Construction to Register Fastest Growth.
Retrofit dominates the Smart Home Automation Market because the large stock of existing houses and apartments can be upgraded device by device without construction work. Households add plugs, bulbs, cameras, thermostats and locks over time, and wireless products can be installed by owners themselves. Renters favor devices that can be removed, and low entry prices let owners start small and expand as they see value in convenience, safety and energy savings. Subscription video and monitoring plans also add value once basic devices are in place.
New construction is projected to register the fastest growth as builders and developers include integrated systems for lighting, climate, security and energy as standard features to differentiate homes. Smart building codes and green building labels reward efficient design, and builders can pre-wire for networks and sensors at low incremental cost. Large housing projects in Asia Pacific and the Middle East are also bundling smart systems with sales, which adds volume for professional integrators. Utilities and insurers are also offering incentives for homes that include connected safety and energy systems.
By Sales Channel, Online Dominates Smart Home Automation Market and Is Also the Fastest-Growing Segment.
Online sales dominate the Smart Home Automation Market because buyers research and compare connected devices through e-commerce sites, brand stores and app marketplaces. Ratings, reviews, frequent discounts and bundled starter kits make online channels convenient for low-cost devices that owners install themselves. Platform companies sell hardware directly and push promotions during major shopping events, while subscription services for video storage and monitoring are also bought online. Easy returns and clear product comparisons also encourage first-time buyers to try connected devices at low risk.
Online sales are also projected to register the fastest growth as logistics improve in emerging markets and more consumers become comfortable buying electronics through mobile apps. Direct-to-consumer brands use social media and video to explain products, and app-based setup reduces the need for in-store help. Offline channels, including electronics chains and professional installers, remain important for premium systems and for consumers who want hands-on demonstration. Offline stores also remain useful for large appliances and for high-end systems that require design advice and site visits.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.00 |
|
Asia Pacific |
China |
38.00 |
|
Europe |
Germany |
24.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
Saudi Arabia |
32.00 |
North America Smart Home Automation Market Insights
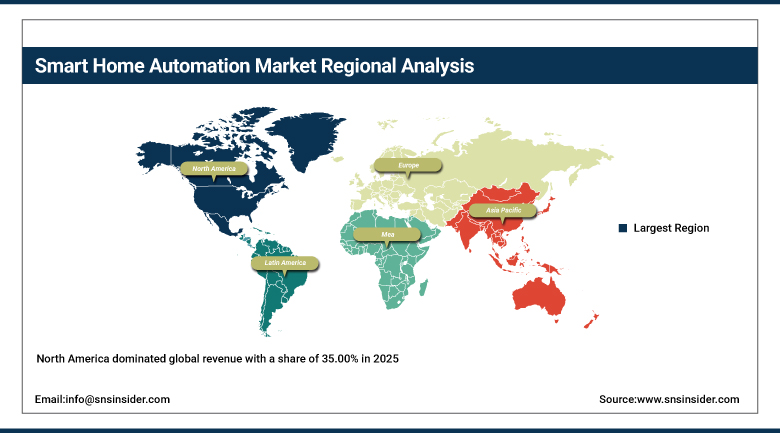
North America dominated global revenue with a share of 35.00% in 2025, and is projected to grow at a CAGR of 8.80% during 2026-2035. The United States accounts for about 86.00% of regional demand, with Canada adding volume. Amazon, Google, Apple, Honeywell, Johnson Controls, ADT, Control4, Crestron, Lutron and Resideo serve consumers and professional installers across the region. Canada adds demand through energy efficiency incentives and cold-climate heating controls, while Mexico adds smaller volumes through online retail and growing urban middle-class households.
High broadband use, high household incomes and early adoption of voice assistants and security cameras support leadership. Home insurers and utilities offer discounts and rebates for connected devices, and professional security providers bundle monitoring services. Market maturity, replacement of devices that lack standard support, and concerns over data privacy moderate growth, but demand for energy management and AI-based features keeps spending rising. Utilities in several states and provinces also run demand response programs that reward households for allowing automatic adjustment of thermostats and appliances at peak hours.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Smart Home Automation Market Insights
Europe is the third-largest region, growing at a CAGR of 8.60% during 2026-2035. Germany leads regional demand, followed by the United Kingdom, France, Italy and the Nordic countries, supported by energy efficiency regulation and high costs of electricity and heating. Schneider Electric, Siemens, Legrand, Robert Bosch, ABB and ASSA ABLOY are headquartered in the region. The United Kingdom, France and Italy add large volumes through retail chains and energy supplier programs, and the Nordic countries add steady demand through well-insulated homes with advanced heating controls.
European buyers value energy saving and privacy, and building rules push heat pumps and smart meters that connect to home systems. Established wired standards such as KNX remain strong in new construction, while wireless devices dominate retrofit. Strict data protection rules, fragmented national markets and high installation costs restrain growth, but subsidies for energy efficiency are widening demand. European standards bodies and industry alliances also work on shared specifications for energy data, which makes it easier for heat pumps, solar systems and home controllers to cooperate across brands and borders.
⮞In July 2024, LG Electronics announced the acquisition of an 80% stake in Athom, the Netherlands-based maker of the Homey smart home hub, with a plan to buy the remaining 20% within three years. LG said it aims to strengthen connectivity within open smart home ecosystems.
Asia Pacific Smart Home Automation Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 12.40% during 2026-2035. China leads regional demand, followed by Japan, South Korea, India and Australia, supported by large urban populations, rapid housing construction and strong local device makers. Xiaomi, Haier Smart Home, Samsung Electronics, LG Electronics and Panasonic are among the main suppliers in the region. Japan and South Korea add demand through premium appliances and apartment complexes with built-in platforms, while India, Indonesia and Vietnam add rising volumes as mobile data and online retail spread.
Chinese platform firms offer cheap connectivity-enabled products in bulk quantities and package them together with cell phones, TV sets, and home appliances. India and Southeast Asia are emerging fast due to the improved broadband infrastructure and adoption of smart speakers, cameras, and appliances by households in cities. However, the lack of standardized systems, price sensitivity, and installation network beyond big cities limits their adoption, although new residential units have been installed with pre-packaged systems. Moreover, the governments in a number of countries promote smart city and smart buildings initiatives, hence more opportunities for integrators and platforms.
⮞On August 7, 2026, Xiaomi launched its Mijia by Xiaomi sub-brand in India to cover home and lifestyle products, including air purifiers, robotic vacuums and security cameras. The launch supports the company's Human × Car × Home strategy.
MEA & Latin America Smart Home Automation Market Insights
In Latin America, Brazil leads, followed by Mexico, Argentina and Colombia, with regional demand growing at about 10.40% annually. Smart speakers, cameras and connected appliances are sold through online marketplaces and retail chains, and security concerns support demand for cameras and alarms. Currency swings, import costs and uneven broadband slow adoption outside large cities. Mexico, Argentina and Colombia add smaller volumes through retail chains and online marketplaces, and home security concerns encourage purchases of cameras, smart locks and alarm systems among middle-income households in large cities.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar and South Africa lead demand, with growth of about 11.00% annually. Large housing and giga-project developments in the Gulf include built-in automation, and affluent buyers favor voice control. In May 2024, Amazon reported that about 6 million smart devices were connected to Alexa in Saudi Arabia and the UAE in 2023, with smart home customers up 50% year over year. The United Arab Emirates and Qatar add demand through luxury apartments and villas with built-in control, and South Africa adds demand through solar and backup power systems that need smart monitoring.
Market Dynamics
Growth Drivers: Connectivity, Energy Efficiency and Artificial Intelligence
Wide availability of broadband, smartphones and low-cost wireless chips is a main driver of the Smart Home Automation Market. Prices of cameras, plugs and sensors have fallen, and app-based setup lets owners install systems themselves. Interoperability under Matter reduces fear of choosing the wrong ecosystem. Growth in remote work and time spent at home has also encouraged households to invest in comfort, security and entertainment upgrades.
Rising energy costs and efficiency rules increase interest in connected thermostats, lighting and energy monitors. Artificial intelligence in voice assistants and hubs adds convenience, while security and elder care uses expand the range of buyers beyond technology enthusiasts. Ageing populations also create demand for monitoring, fall detection and reminders that help older adults live independently.
Restraints: Privacy, Fragmentation and Cost
Privacy and cybersecurity concerns remain a barrier, since cameras, microphones and hubs collect sensitive data. Breaches or unclear data policies can reduce trust and slow purchases among cautious households. Security vulnerabilities in low-cost devices can also expose home networks to attacks, which has drawn regulatory attention.
Despite Matter, many older devices and regional platforms do not work together, and setup can be complex. Premium systems and professional installation are costly, and economic pressure can delay discretionary spending on non-essential devices. Short product support periods also leave some devices without updates, which discourages cautious buyers from investing in whole-home systems.
Opportunities: Whole-Home Subscriptions, Energy Services and Emerging Markets
Bundled subscriptions for security, video storage, energy savings and home care create recurring revenue for platform companies and installers. Partnerships with utilities, insurers and service providers can lower customer acquisition cost and expand reach. Home builders can offer packages that bundle devices, installation and support at the time of sale.
Emerging markets in Asia Pacific, Latin America and the Middle East offer large first-time buyer pools as broadband spreads and housing is built. Generative AI assistants, vehicle integration and home health monitoring are further opportunities for new services. Healthcare providers and insurers may also support remote monitoring devices that reduce hospital visits and costs.
Recent Developments:
-
2026: Google began early access to its Google Home MCP server for U.S. Google Home Premium Advanced subscribers. The server lets compatible AI agents read event history and control Google Home and Matter devices.
-
2026: Apple introduced HomeView, combining a seven-inch display, Siri AI, entertainment and household controls. The device supports smart home management, including lighting, thermostat adjustments and connected security.
-
2025: Resideo unveiled the Honeywell Home X2S smart thermostat at CES. Matter compatibility, energy-saving features and accessible pricing positioned the product for households seeking simpler connected climate control.
Smart Home Automation Market Key Players are
-
Amazon.com, Inc.
-
Google LLC
-
Apple Inc.
-
Samsung Electronics Co., Ltd.
-
LG Electronics Inc.
-
Haier Smart Home Co., Ltd.
-
Xiaomi Corporation
-
Schneider Electric SE
-
Siemens AG
-
Honeywell International Inc.
-
Johnson Controls International plc
-
ABB Ltd.
-
Legrand SA
-
Robert Bosch GmbH
-
ASSA ABLOY AB
-
ADT Inc.
-
Control4 Corporation
-
Crestron Electronics, Inc.
-
Lutron Electronics Co., Inc.
-
Resideo Technologies, Inc.
Smart Home Automation Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 117.45 Billion |
| Market Size by 2035 | USD 310.22 Billion |
| CAGR | CAGR of 10.20% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product (Entertainment and Media Devices, Security and Access Control, HVAC and Energy Management, Lighting Control, Smart Appliances, and Others) • By Technology (Wi-Fi, Zigbee and Z-Wave, Bluetooth, Matter, Thread, and Others) • By Installation Type (Retrofit and New Construction) • By Sales Channel (Online and Offline) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amazon.com, Inc., Google LLC, Apple Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Haier Smart Home Co., Ltd., Xiaomi Corporation, Schneider Electric SE, Siemens AG, Honeywell International Inc., Johnson Controls International plc, ABB Ltd., Legrand SA, Robert Bosch GmbH, ASSA ABLOY AB, ADT Inc., Control4 Corporation, Crestron Electronics, Inc., Lutron Electronics Co., Inc., Resideo Technologies, Inc. |

Frequently Asked Questions
Key players include Amazon.com, Inc., Google LLC, Apple Inc., Samsung Electronics Co., Ltd., LG Electronics Inc., Haier Smart Home Co., Ltd., Xiaomi Corporation and Schneider Electric SE.
Key opportunities include whole-home subscription services, energy management with utilities, and first-time buyers in Asia Pacific, Latin America and the Middle East.
The major growth factor is wider broadband and low-cost wireless devices, supported by energy efficiency needs, voice assistants and open standards such as Matter.
By Product, the Entertainment and Media Devices segment dominated the market in 2025 with an estimated 26.00% share, supported by smart speakers and streaming devices.
North America dominated the market with a share of 35.00% in 2025, driven by high broadband use, incomes and early adoption of connected devices.
