
Social and Emotional Learning (SEL) Market Report Scope & Overview:
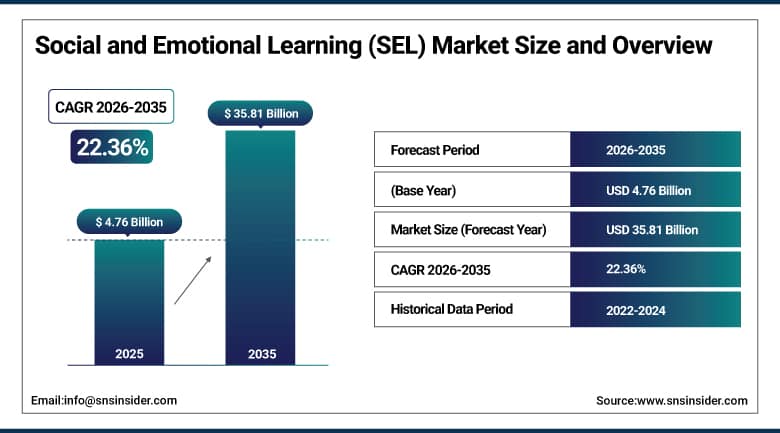
The Social and Emotional Learning (SEL) Market was valued at USD 4.76 Billion in 2025 and is estimated at USD 5.82 Billion in 2026. It is projected to reach USD 35.81 Billion by 2035, advancing at a CAGR of 22.36% from 2026 to 2035. Social and emotional learning covers the curricula, digital platforms, assessments, and training services that help students build self-awareness, self-management, empathy, relationship skills, and responsible decision-making. Student mental health concerns, government funding, and evidence linking these skills to academic results are expanding adoption in schools. Subscription models are common.
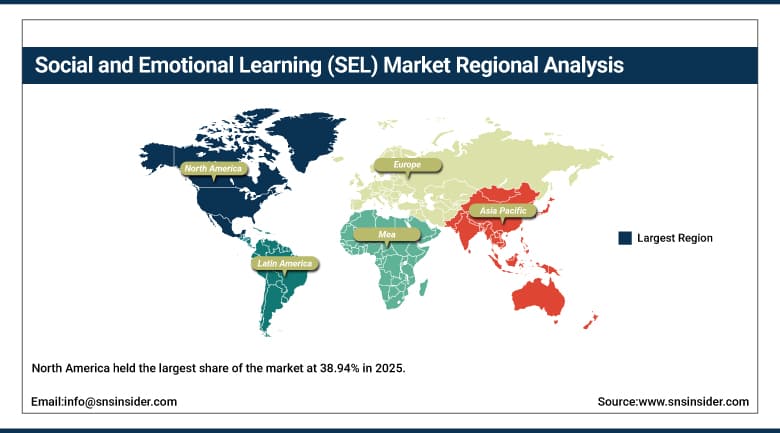
The North American region held the largest market share with 38.94% because of the presence of state learning standards, purchases at the district level, and the availability of established curriculum and assessment providers. On the other hand, the Asia Pacific region holds the second place in terms of size; however, the fastest growth is expected to be achieved by this region during the forecasted period due to the introduction of well-being programs in countries like India, China, Japan, and Australia. The European region is capitalizing on well-being programs as part of the national curriculum, while Latin America and the MEA regions are implementing well-being programs through reforms at the school level.
To Get More Information On Social and Emotional Learning (SEL) Market - Request Free Sample Report
Key Report Takeaways:
-
By component, solutions held a 68.12% share in 2025, while services are the fastest growing.
-
By type, web-based delivery accounted for a 58.34% share in 2025, while application-based delivery is the fastest growing.
-
By end user, middle and high schools represented a 41.36% share in 2025, while Pre-K is the fastest growing.
-
By core competency, self-management commanded a 28.46% share in 2025, while relationship skills are the fastest growing.
-
By region, North America led with a 38.94% share in 2025, while Asia Pacific is the fastest growing.
Market Trends and Insights:
Platforms are replacing stand-alone curricula. Districts increasingly buy systems that bundle lessons, student surveys, assessments, and reporting, so staff can screen needs, assign interventions, and track progress in one place.
Artificial intelligence is entering the classroom workflow. Vendors are adding tools that analyze survey responses, suggest interventions, and give teachers feedback, while districts weigh privacy and fairness before turning these features on.
Funding is moving from temporary relief grants to recurring operating budgets. Districts that launched programs with emergency money are now deciding which products to keep, which favors vendors that can show measurable results.
Demand is spreading beyond K-12. Early childhood centers, colleges, and employers are adopting social and emotional skills programs, and mobile applications and immersive formats are broadening how lessons are delivered.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Government Mandates, Standards, and School Funding |
+8.92% |
North America and Asia Pacific |
Short term (2 years or less) |
|
Rising Youth Mental Health Concerns |
+6.86% |
Global |
Short term (2 years or less) |
|
Evidence Linking SEL to Academic and Career Outcomes |
+5.32% |
Global |
Medium term (2 to 4 years) |
|
Digital Platforms and Artificial Intelligence Personalization |
+4.74% |
North America and Europe |
Medium term (2 to 4 years) |
|
Expansion into Higher Education and Corporate Training |
+3.32% |
Global |
Long term (4 years or more) |
Government Mandates, Standards, and School Funding
Public authorities are writing social and emotional skills into learning standards and school improvement plans, and they are funding the services that deliver them. The U.S. Department of Education announced more than USD 208 million in new school-based mental health awards in December 2025, directed to state and local education agencies. Such funding lets districts purchase curricula, screening tools, and training. National programs in Asia and Europe add similar requirements, which creates a steady pipeline of public purchases and encourages vendors to align products with each jurisdiction's standards.
Rising Youth Mental Health Concerns
Schools are now a primary setting for early support. According to the Centers for Disease Control and Prevention, 39.70 percent of American high school students felt persistently sad or hopeless during 2023. Both educators and parents try to find courses that will teach their children how to cope with their problems and regulate emotions as well as screen tools that will allow finding those who need help. This is why wellbeing remains a priority of school districts and helps to spend money on programs on a regular basis despite all other constraints.
Evidence Linking SEL to Academic and Career Outcomes
Research increasingly connects social and emotional skills to attendance, behavior, test results, and later employment, which strengthens the case for purchase. The Organisation for Economic Co-operation and Development published its Survey on Social and Emotional Skills in April 2024, measuring five skill domains among 10-year-old and 15-year-old students. Such measurement gives policymakers and school leaders benchmarks and encourages comparisons across systems. Vendors that publish outcome studies and align products with recognized competency frameworks gain credibility and win larger multi-year district contracts.
Digital Platforms and Artificial Intelligence Personalization
The use of online and mobile apps makes it possible to facilitate delivery of lessons, gather feedback from the students, and deliver reports more easily. Vendors are now incorporating analytics that alert educators on students who may require support, suggest certain activities for them, and minimize the paperwork teachers do. Interactive lessons, games, and video clips keep young students engaged, and delivery via cloud makes it inexpensive to implement. These features make it possible to broaden the addressable market and sustain programs where there is no well-being staff at schools.
Expansion into Higher Education and Corporate Training
Social and emotional skills such as collaboration, empathy, and resilience are increasingly valued by colleges and employers. Universities are adding wellbeing and student success programs, and companies are using similar content for leadership, communication, and team building. These buyers fund licenses, assessments, and coaching services that extend the market beyond school districts. Corporate demand also supports adult-focused products and gives established providers a second revenue stream as the evidence base grows and acceptance spreads. Wellbeing benefits are becoming part of employer packages.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
High Implementation Costs and Teacher Time Demands |
-2.64% |
Global |
Short term (2 years or less) |
|
Policy Volatility and Political Opposition |
-1.92% |
North America |
Medium term (2 to 4 years) |
|
Student Data Privacy Concerns |
-1.38% |
North America and Europe |
Medium term (2 to 4 years) |
|
Lack of Standardized Measurement |
-0.86% |
Global |
Long term (4 years or more) |
High Implementation Costs and Teacher Time Demands
Effective programs need licenses, training, coaching, and protected class time, and many schools struggle to provide all of them. Teachers already carry heavy workloads, and adding lessons or surveys can meet resistance without strong leadership support. Smaller districts and schools in lower-income countries often lack the budget and staff to sustain programs once pilot funding ends. Vendors offer bundled pricing and training, but total cost and time requirements remain a barrier that slows adoption among smaller buyers. Pilot results are often not scaled.
Policy Volatility and Political Opposition
Funding and policy for social and emotional programs can change quickly. In April 2025, the U.S. Department of Education ended about USD 1 billion in school mental health grants to roughly 260 recipients, which forced districts to reconsider planned purchases. Some communities also object to the content of social and emotional lessons, and several state legislatures have debated limits. This uncertainty makes districts cautious about long contracts and can delay launches, although other awards and local funding continue to support programs. Parent groups influence board decisions.
Student Data Privacy Concerns
The digital applications capture personal data relating to student emotions, behaviors, and wellbeing, and parents fear about their storage and usage. The law and policies related to education privacy mandate that there must be due diligence by the vendors in this matter and data processing agreements along with security audits. The problem increases in case of usage of artificial intelligence technologies on the student’s responses as any mistakes or biases may influence student labeling. This makes procurement cycle lengthy and expensive for the vendors.
Lack of Standardized Measurement
Social and emotional skills are difficult to measure, and districts use different surveys, rubrics, and definitions. Results can vary across cultures and age groups, and self-reported data may not reflect actual behavior. Without common benchmarks, it is hard to compare programs or prove return on investment, which weakens the case for continued funding. Researchers and vendors are working on validated, culturally inclusive assessments, but adoption of shared standards remains uneven across systems. Cultural differences in how emotions are expressed complicate comparisons, and translated surveys can shift meaning, so scores from different countries are hard to interpret consistently.
Social and Emotional Learning (SEL) Market Segment Analysis:
By Component, Solutions Dominates Social and Emotional Learning (SEL) Market; Services to Register Fastest Growth.
Solutions held a 68.12% share in 2025 because districts first purchase curricula, digital lessons, assessment tools, and reporting platforms that form the core of any program. These products are licensed per student or per school, and renewals provide recurring revenue. Vendors continually add content aligned with state standards and competency frameworks, and large districts often standardize on a single platform, which keeps solution revenue well ahead of other categories. Content libraries are refreshed each year to match standards.
The services segment is projected to experience the highest rate of growth, with a CAGR of 24.18% between 2026 and 2035. School districts require training, coaching, and implementation as well as analysis of data in order to realize the outcomes of tools purchased by them. Many schools do not have in-house experts for this purpose. The need for consulting in designing and evaluating the programs adds to this growth. Vendors price these services per school or per teacher. Longer contracts follow.
By Type, Web-Based Dominates Social and Emotional Learning (SEL) Market; Application to Register Fastest Growth.
Web-based delivery accounted for a 58.34% share in 2025 because browser access works on school computers, tablets, and shared devices without installation. District technology teams value central administration, single sign-on, and simple updates, and teachers can assign lessons and view reports from one dashboard. Established platforms also integrate with student information systems, which supports consistent roll-out across many schools and keeps web-based tools at the center of purchasing. Vendors also support mobile browsers for families. Updates arrive automatically.
It is estimated that application delivery is likely to experience the highest growth rate with a CAGR of 25.12% during 2026-2035. Mobile applications will appeal to students who work on their phones and tablets at home and help in conducting short daily assessments, games, and coaching sessions. Higher education institutions and corporates favor app-based access. The inclusion of offline capability and push notifications in these apps helps make applications available to students and adults beyond the classroom environment. Push reminders keep students engaged.
By End User, Middle and High Schools Dominate Social and Emotional Learning (SEL) Market; Pre-K to Register Fastest Growth.
Middle and high schools held a 41.36% share in 2025 because adolescents face the highest rates of stress, bullying, and mental health concerns, and schools serving them invest heavily in screening and prevention. Larger enrollments and dedicated counselors support bigger purchases, and older students can use digital tools independently. Many districts also connect programs to graduation, attendance, and career readiness goals, which keeps this end user the largest. Counselors use findings to plan group sessions. Parents also support these programs.
Pre-K is expected to register the fastest growth, with a CAGR of 25.48% from 2026 to 2035. Public early learning programs are expanding, and research shows that early skills influence later outcomes, which attracts funding from governments and foundations. Play-based curricula, storybooks, and teacher guides suit young children. Elementary schools remain a large, steady buyer, and higher education and other users add smaller volumes, but early childhood shows the steepest increase in adoption. Parents also request home activities.
By Core Competency, Self-Management Dominates Social and Emotional Learning (SEL) Market; Relationship Skills to Register Fastest Growth.
Self-management represented a 28.46% share in 2025 because skills such as emotional regulation, impulse control, goal setting, and stress management are directly tied to classroom behavior and attendance. Teachers see immediate benefits when students can stay focused, and many curricula begin with these lessons. Discipline reform and behavior support programs also draw on self-management content, which gives this competency the strongest base of purchases. Many programs measure progress through short surveys each term. Teachers value its link to behavior.
The skill area where the highest growth will be seen is relationship skills, having a Compound Annual Growth Rate equal to 24.12% within 2026 to 2035. The importance of communication skills, cooperation skills, conflict resolution skills, and prevention of bullying has increased in schools because of the appearance of issues connected with online behavior and social isolation. This skill area is appreciated not only by schools but also by employers, and it helps to create demand both from corporations and higher educational establishments.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
75.48% |
|
Europe |
Germany |
24.86% |
|
Asia Pacific |
China |
41.73% |
|
Latin America |
Brazil |
46.92% |
|
Middle East & Africa |
Saudi Arabia |
27.14% |
North America Social and Emotional Learning (SEL) Market
North America held the largest share of the market at 38.94% in 2025, supported by state learning standards, district-level purchasing, and a mature base of curriculum and assessment vendors. The United States accounted for most regional demand, with a 2025 value of USD 1.40 Billion, and is expected to grow at a CAGR of 21.01% from 2026 to 2035. Canada adds demand through provincial wellbeing frameworks and school health programs. Demand is broad-based across school levels. Provincial ministries guide Canadian purchases.
Many states now publish social and emotional learning standards, and districts use federal and state grants, along with local budgets, to fund purchases. Large vendors of curricula, surveys, and behavior support platforms are based in the region and compete with newer providers of artificial intelligence feedback tools. Consolidation among assessment and intervention firms continues. Teacher unions and parent groups also influence adoption choices, and vendors invest in evidence studies to win approval from review committees that decide which programs districts may buy.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Social and Emotional Learning (SEL) Market
Europe is a mature market shaped by national wellbeing frameworks and public education systems. The UK, Germany, France, and the Nordic states provide the bulk of funding within the region. Local programs and curricula are used by schools, while government supports pilot programs for mental health and bullying prevention. Collaboration among research groups in the region allows sharing of evidence-based research results, which encourages gradual implementation based on common standards. Health and wellbeing curricula of Scotland and Ireland ensure stable demand, along with coordinated staff training at the regional level.
Product Design is greatly affected by Data Protection Laws, where data must be hosted in the region and proper consent must be taken. Training for teachers forms an important part of spending, and both universities and nonprofits actively participate as suppliers. Procurement is usually done in a centralized manner within the region or municipality, which increases the sales cycle period; however, framework agreements ensure steady income for vendors. Public funding rules also favor programs with independent evaluations. Framework contracts typically last several years and reward consistent service.
Asia Pacific Social and Emotional Learning (SEL) Market
The Asia Pacific region is projected to lead the regional market with a CAGR of 24.56% between 2026 and 2035. The countries such as India, China, Japan, South Korea, and Australia are redesigning their curriculums in terms of well-being and life skills, while parents prefer programs that do not put stress on children academically. With huge numbers of students, the region provides a strong foundation for the digital platform, and private schools and tutoring services quickly incorporate these programs.
The Indian government has mandated schools to focus on counseling programs and training for mental health. School chains in the private sector in India are procuring curriculum and assessment material. The Chinese government is focusing on moral and psychological development, whereas Japan and South Korea are running pilots on well-being surveys. Frameworks exist in Australia and New Zealand. The curriculum developers localize the content according to language and cultural conditions. Singapore and Hong Kong add demand through character and citizenship education programs, and international schools across the region buy curricula from global providers to serve expatriate families.
Latin America Social and Emotional Learning (SEL) Market
Latin America is a developing market, with Brazil and Mexico accounting for most spending. The curricula of private school chains are based on the international curricula, while the public system brings in socioemotional competences to their national standards. The national curriculum of Brazil incorporates socioemotional competencies, thereby providing a foundation for teacher training and material preparation. Foundations and developmental organizations finance their programs in poor regions, while Mexico provides its contribution through public school programs, and private bilingual schools implement international curricula that promote well-being and leadership. The demand grows steadily.
Limited budgets and poor connectivity hamper the use of digital technologies, so printed materials and teachers' lessons are popular. Colombia, Chile, and Argentina bring their contribution through reform programs and programs aimed at violence prevention, while regional developers prepare local versions of global curricul. Mobile access is improving, and applications are making low-cost delivery more feasible in schools that lack reliable computers or broadband. Public universities and teacher training colleges in the region are beginning to add socioemotional modules to their courses, which should widen the pool of qualified instructors over time.
Middle East & Africa Social and Emotional Learning (SEL) Market
The Middle East & Africa region holds a small share, yet Gulf countries are investing in wellbeing and character education as part of education reform strategies. The countries leading expenditure are Saudi Arabia and the UAE, which have international schools using a global curriculum. South Africa is still the key country in sub-Saharan Africa, where programs are delivered by NGOs in poorly resourced schools. In addition, Qatar and Kuwait provide smaller volumes via wellness programs. Ministries of education in the region are collaborating with global companies for localization of the curriculum in Arabic language.
Many African countries rely on donor-funded projects and community programs, which limits scale but builds local expertise. Connectivity and teacher shortages constrain digital adoption outside major cities. Growth is expected to continue from a small base as governments expand mental health policies in schools and as mobile-based tools lower the cost of reaching students and teachers. Faith-based and community schools also deliver character education, which creates openings for programs that respect local traditions while teaching communication and resilience skills. Donor support is common.
Competitive Landscape:
The competitive landscape is fragmented, with curriculum developers, assessment and survey platforms, student support and behavior systems, learning companies, nonprofits, and a long tail of small program developers. Leading suppliers compete on evidence of results, alignment with state standards, platform integration, and the breadth of professional development, while newer entrants compete on artificial intelligence feedback and mobile delivery. No firm holds a dominant share, because districts combine products from several providers.
Strategies revolve around acquiring those products that connect assessment to instruction, development of digital platforms, partnering with assessment companies, and launching units dealing with wellness in the artificial intelligence era. The companies also engage in research projects, provide training programs for teachers, and integrate with student information systems. Small companies distinguish themselves from the competition by targeting certain age groups, languages, or culture.
Social and Emotional Learning (SEL) Market Industry Leaders
1. Committee for Children: Nonprofit developer of the Second Step programs for early learning through high school, covering social and emotional learning, bullying prevention, and child protection.
2. Panorama Education: Provider of student surveys, analytics, and intervention tools used by school districts to support student success and wellbeing.
3. Riverside Insights: Assessment company whose portfolio includes the DESSA social and emotional assessment and instruction tools acquired through its recent purchases.
4. Rethink Ed: Provider of cloud-delivered instruction and assessment for wellness skills, behavior support, and special education in schools.
5. Vector Solutions: Training and safety software company whose education business serves K-12 and higher education institutions with online courses and learning tools.
Companies Covered in this Report:
-
Committee for Children
-
Panorama Education
-
Riverside Insights
-
Rethink Ed
-
Vector Solutions
-
Branching Minds
-
CharacterStrong
-
ERB
-
McGraw Hill
-
Renaissance
Recent Industry Developments:
-
October 2024: ERB partnered with a social and emotional curriculum developer to offer its SelfWise student inventory alongside classroom lessons.
-
February 2025: FullBloom acquired CharacterStrong, a provider of character and social and emotional learning programs for schools.
-
October 2025: Panorama Education launched Solara with Class Companion, an artificial intelligence tool that gives rubric-aligned feedback on student writing.
-
March 2026: Riverside Insights acquired Move This World to link the DESSA assessment with social and emotional instruction.
-
May 2026: Committee for Children launched a digital wellbeing unit within Second Step for K-12 students.
-
June 2026: Vector Solutions introduced Learning Studio for customizable training in K-12 and higher education.
Scope and Research Methodology
This report defines the Social and Emotional Learning (SEL) Market as the commercial value of curricula, digital platforms, assessment and survey tools, and related training and implementation services sold to schools, early learning programs, colleges, and employers to build social and emotional skills. General academic software and stand-alone counseling services are excluded. Values are stated in USD at vendor selling prices, including subscription revenue. The base year is 2025 and the forecast runs from 2026 to 2035. Content sold to parents directly through consumer apps without school involvement is included only where it follows a recognized competency framework, and adult coaching sold outside education is excluded.
Primary research comprised interviews with district wellbeing directors, school principals, counselors, curriculum coordinators, procurement officers, and executives at curriculum, assessment, and platform vendors. Secondary research drew on education agency releases, public health surveys, international assessments, company filings, product documentation, and association publications. Enrollment and spending were linked to student counts and program adoption in each country, then converted to value using license and service pricing. Each interview followed a structured guide covering program selection, pricing, evidence requirements, implementation effort, and adoption barriers, and responses were coded by region and school level so that patterns could be compared across countries and sizes of institution.
A bottom-up build by component, end user, and country was cross-checked against a top-down view based on education technology and professional development spending. Forecasts apply growth rates by segment that reflect funding changes, policy shifts, and pricing trends, with scenarios for grant availability. Regional shares were validated against enrollment and program coverage, and the five regions sum to the global figure. Findings were reviewed by internal analysts and external experts before release. Where estimates differed, analysts revisited assumptions on license pricing and enrollment coverage and consulted additional experts until the figures converged on a single view. Documentation is retained for audit.
Social and Emotional Learning (SEL) Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 4.76 Billion |
| Market Size by 2035 | USD 35.81 Billion |
| CAGR | CAGR of 22.36% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Component (Solutions and Services) • By Type (Web-Based and Application) • By End User (Pre-K, Elementary School, Middle and High School, and Others) • By Core Competency (Self-Awareness, Self-Management, Social Awareness, Relationship Skills, and Responsible Decision-Making) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Committee for Children, Panorama Education, Riverside Insights, Rethink Ed, Vector Solutions, Branching Minds, CharacterStrong, ERB, McGraw Hill, Renaissance |

Frequently Asked Questions
The market was valued at USD 4.76 Billion in 2025 and is estimated at USD 5.82 Billion in 2026. It is forecast to reach USD 35.81 Billion by 2035.
The market is projected to expand at a CAGR of 22.36% from 2026 to 2035.
North America led with a 38.94% share in 2025, while Asia Pacific is the fastest-growing region, with a CAGR of 24.56% from 2026 to 2035.
Solutions held the largest share, at 68.12% in 2025, while services are expected to grow fastest.
Pre-K is expected to record the fastest growth, with a CAGR of 25.48% from 2026 to 2035.
Government mandates and funding, rising youth mental health concerns, evidence linking skills to outcomes, digital platforms with artificial intelligence personalization, and expansion into higher education and workplaces.
High implementation costs, policy volatility, student data privacy concerns, and a lack of standardized measurement.
