
Strategic Consulting Services Market Report Scope & Overview:
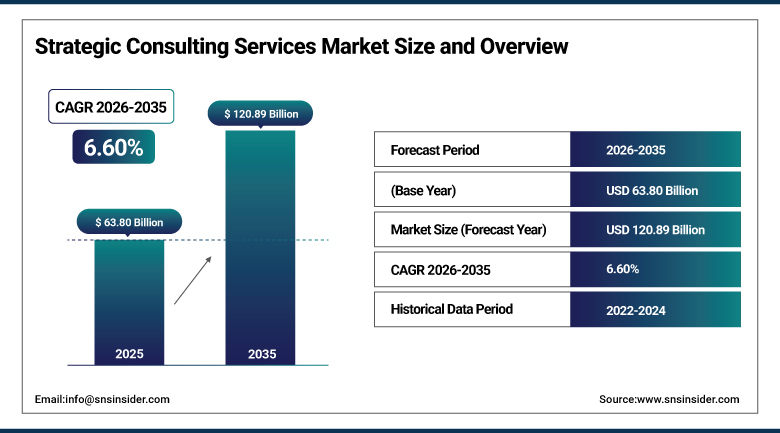
The Strategic Consulting Services Market was valued at USD 63.80 Billion in 2025 and is expected to reach USD 120.89 Billion by 2035, growing at a CAGR of 6.60% from 2026-2035.
The Strategic Consulting Services Market covers advisory work in which firms help corporations, governments and investors set direction on growth, portfolio choices, mergers and acquisitions, operating models, transformation and technology. Engagements range from short diagnostics to multi-year programs and increasingly combine advice with delivery of technology and data tools. Growth is supported by economic uncertainty, digital and AI transformation, deal activity and sustainability agendas, while client cost control, in-house strategy teams and AI tools that automate analysis shape pricing and demand.
⮞Consulting firms are tying advice to AI partnerships. On December 1, 2025, Accenture and OpenAI announced a collaboration to bring agentic AI into the core of client businesses. Accenture is giving tens of thousands of its professionals access to ChatGPT Enterprise, and the companies launched a client program aimed at financial services, healthcare, the public sector and retail.
To Get more information Strategic Consulting Services Market - Request Free Sample Report
Strategic Consulting Services Market Trends
-
Use of generative and agentic AI inside consulting delivery and client solutions
-
Move from slide-based advice to execution support and managed outcomes
-
Growth of technology strategy work on cloud, data and cybersecurity
-
Rising demand for sector-specific advice on energy transition and supply chains
-
Consolidation of service lines and acquisition of specialist boutiques and software assets
-
Wider use of digital and remote delivery for mid-sized clients
U.S. Strategic Consulting Services Market Outlook
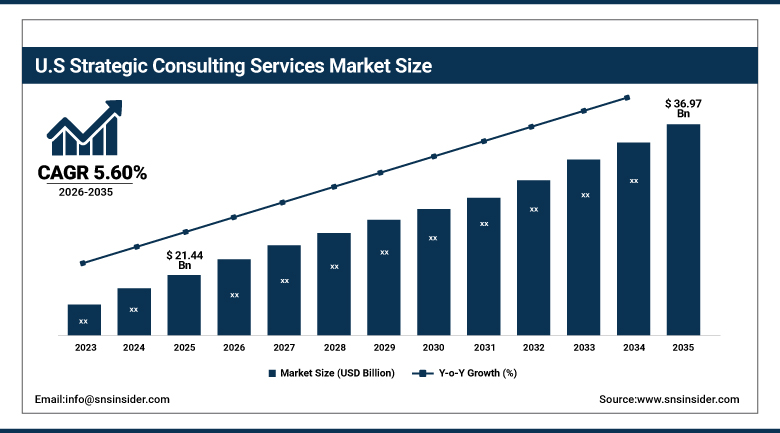
The U.S. Strategic Consulting Services Market was valued at USD 21.44 Billion in 2025 and is expected to reach USD 36.97 Billion by 2035, growing at a CAGR of 5.60% from 2026-2035.
The U.S. Strategic Consulting Services Market is the largest national market, supported by the headquarters of leading consulting firms, a deep base of large corporations, active private equity and deal markets, and heavy corporate spending on technology. Financial services, healthcare, technology and energy are major buyers, and federal agencies add public sector demand. Growth is moderated by market maturity, client pressure on fees and the growth of in-house strategy and analytics teams.
⮞Large firms are buying software to scale advice. On January 27, 2025, Deloitte announced the acquisition of substantially all assets of SimplrOps, a SaaS company that automates cloud ERP and human capital management work for platforms such as Workday, SAP and Oracle. Deloitte described it as one of its first standalone SaaS products for its Human Capital practice.
Strategic Consulting Services Market Segment Analysis
-
By Service Type, corporate strategy segment dominated the Strategic Consulting Services Market in 2025 with an estimated 31.00% share; technology strategy segment is the fastest-growing segment, with an estimated CAGR of 9.50% during 2026–2035.
-
By Enterprise Size, large enterprises segment dominated the Strategic Consulting Services Market in 2025 with an estimated 58.00% share; small and medium enterprises segment is the fastest-growing segment, with an estimated CAGR of 8.40% during 2026–2035.
-
By Industry Vertical, BFSI segment dominated the Strategic Consulting Services Market in 2025 with an estimated 24.00% share; healthcare and life sciences segment is the fastest-growing segment, with an estimated CAGR of 8.90% during 2026–2035.
-
By Delivery Mode, on-site and hybrid segment dominated the Strategic Consulting Services Market in 2025 with an estimated 72.00% share; digital and remote segment is the fastest-growing segment, with an estimated CAGR of 10.50% during 2026–2035.
By Service Type, Corporate Strategy Dominates Strategic Consulting Services Market; Technology Strategy to Register Fastest Growth.
Corporate strategy dominates the Strategic Consulting Services Market because boards and chief executives rely on outside advisers for portfolio choices, growth plans, mergers and acquisitions, restructuring and market entry. These engagements carry high fees and involve senior partners, and demand rises during periods of uncertainty or deal activity. Established firms with strong brands and sector knowledge keep the largest share of this work, and repeat relationships with large clients support steady revenue. Fees on these projects are also less sensitive to price, since the stakes for the client are high.
Technology strategy is projected to register the fastest growth as companies decide how to apply artificial intelligence, cloud, data platforms and cybersecurity across their operations. Executives want advice on investment priorities, build or buy choices and operating model changes, and consulting firms are combining strategy with delivery teams and partner ecosystems. Large technology vendors, hyperscalers and consultancies are building joint offers, which brings additional work for firms that can link strategy to implementation. Smaller advisory houses specializing in data and cybersecurity strategy are also winning projects alongside the large firms.
By Enterprise Size, Large Enterprises Dominates Strategic Consulting Services Market; Small and Medium Enterprises to Register Fastest Growth.
Large enterprises dominate the Strategic Consulting Services Market because they have complex portfolios, global operations and budgets for multi-year programs. They engage firms for transformation, cost programs, mergers and regulatory change, and they sign framework agreements with a few preferred advisers. Boards also use outside views to validate major investments, and listed companies facing activist or investor pressure frequently commission strategy reviews. Annual planning cycles also bring repeat projects, which gives large firms predictable revenue from major accounts. Procurement panels also favor firms with global reach.
Small and medium enterprises are projected to register the fastest growth as smaller firms seek advice on growth, digital adoption, financing and expansion into new markets. Boutique consultancies, digital platforms and lower-cost packaged offers are opening the market to clients that could not afford large firms. Government programs and growth capital from private investors also fund advisory work, and remote delivery reduces the travel cost of serving mid-sized clients. Banks and development agencies also support advisory programs for smaller firms, which widens the buyer base.
By Industry Vertical, BFSI Dominates Strategic Consulting Services Market; Healthcare and Life Sciences to Register Fastest Growth.
BFSI dominates the Strategic Consulting Services Market because banks, insurers and asset managers face regulatory change, digital competition, cost pressure and constant deal activity. They commission advice on growth strategy, risk, capital allocation, operating models and technology modernization. Large financial groups have sizable budgets and long-standing relationships with consulting firms, and new rules on capital, climate disclosures and operational resilience create steady demand for specialist advice. Compliance programs also keep financial clients buying from advisers who know the rules in many countries.
Healthcare and life sciences is projected to register the fastest growth as drug makers, hospitals, payers and device companies adjust to pricing pressure, new therapies, digital health and supply chain risk. Portfolio and pipeline decisions, market access strategy, mergers and manufacturing footprints are frequent topics. Private equity interest in healthcare services and the use of AI in drug discovery and care delivery add more strategy projects for advisers with sector expertise. Public health spending and aging populations also keep pushing healthcare clients to seek outside strategic advice.
By Delivery Mode, On-Site and Hybrid Dominates Strategic Consulting Services Market; Digital and Remote to Register Fastest Growth.
On-site and hybrid delivery dominates the Strategic Consulting Services Market because senior-level strategy work depends on workshops, interviews and close contact with executives and boards. Teams combine in-person sessions with remote analysis, and large projects often need staff embedded within clients. Trust built through direct engagement is important for sensitive topics such as restructuring, mergers and leadership change, which supports the lead of this mode. Executives also prefer face-to-face meetings for decisions that affect jobs, ownership and reputation, which keeps this mode ahead.
Digital and remote delivery is projected to register the fastest growth as firms use video, collaboration tools, data platforms and AI assistants to serve clients across regions at lower cost. Subscription research, benchmarking tools and on-demand expert networks are becoming parts of consulting offers. Mid-sized clients and public bodies accept remote work for diagnostics and analysis, and global firms use distributed teams to extend capacity. Pay-per-use research and on-demand expert calls also let smaller teams buy advice without a large commitment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
84.00 |
|
Europe |
United Kingdom |
27.00 |
|
Asia Pacific |
India |
18.00 |
|
Latin America |
Brazil |
45.00 |
|
Middle East & Africa |
Saudi Arabia |
34.00 |
North America Strategic Consulting Services Market Insights
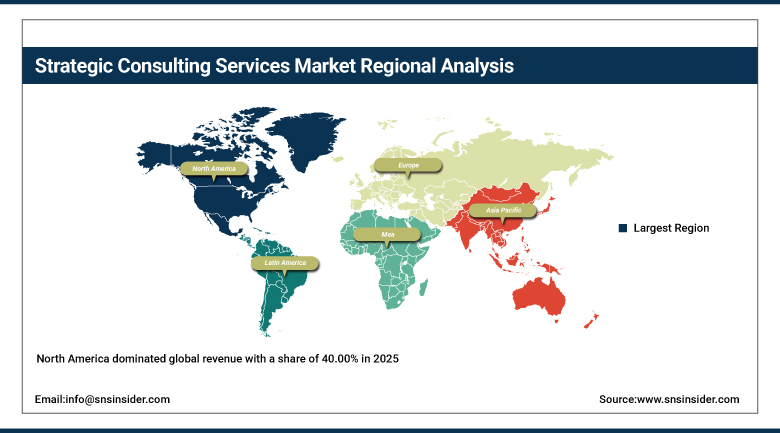
North America dominated global revenue with a share of 40.00% in 2025, and is projected to grow at a CAGR of 5.60% during 2026-2035. The United States accounts for the majority of the regional demand, with Canada adding volume through banking, resources and public sector work. McKinsey & Company, Boston Consulting Group, Bain & Company, Deloitte, Accenture, PwC, EY, KPMG and Oliver Wyman serve clients in the region. Canada adds demand through its large banks, energy and mining companies and federal programs, while Mexico adds smaller volumes through manufacturing and consumer goods clients linked to cross-border supply chains.
The region has the largest concentration of corporate headquarters, private equity firms and technology companies, which keeps demand for growth, deal and transformation advice high. Spending on AI strategy is increasing, and firms are expanding digital and managed services. Market maturity, fee pressure from procurement teams and in-house strategy groups moderate growth, but regulatory change and deal cycles support steady project flow. Large firms in the region are also expanding data science and AI teams, and acquisitions of specialist advisers help them offer sector-specific products.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Strategic Consulting Services Market Insights
Europe is the second-largest region. The United Kingdom, Germany, France, Switzerland and the Nordic countries lead regional demand, supported by large industrial groups, banks and public bodies. Roland Berger, Capgemini Invent, Arthur D. Little, Kearney, Oliver Wyman and the major global firms are active in the region. Germany adds large industrial and automotive mandates, France and Italy add demand through luxury, energy and banking clients, and Spain, Switzerland and the Netherlands add steady work in finance and pharmaceuticals.
European clients seek advice on energy transition, industrial competitiveness, regulation, supply chain resilience and defense spending. Local firms compete with global brands through sector knowledge and regional networks. Slow economic growth in some countries, cautious budgets and differences in language and regulation moderate growth, though demand for AI and sustainability advice remains solid. The European Union also funds recovery and digital programs that employ advisers, and mid-sized family-owned industrial groups are increasingly buying advice on succession and international growth. Brexit effects and trade rules also keep cross-border clients buying advice.
⮞On May 27, 2026, Capgemini set mid-term targets of 5.50% to 7.50% average annual revenue growth for 2025-2028, as it positions itself as an AI consultant with industry-specific knowledge, with the WNS unit central to wiring AI into large legacy companies.
Asia Pacific Strategic Consulting Services Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 8.80% during 2026-2035. India leads regional growth, with China, Japan, Australia, Singapore and South Korea also important, supported by economic expansion, foreign investment, digital transformation and cross-border deals. Global firms and regional players such as local advisory houses compete for work from conglomerates and governments. China adds demand through market-entry and localization projects for global companies, while Japan and South Korea add work on restructuring, corporate governance and overseas expansion, and Australia adds mining and public sector assignments.
Companies in the region seek advice on market entry, supply chain diversification, digital platforms, sustainability and mergers. Global firms are adding offices in secondary cities and building delivery centers, and local boutiques are gaining clients among mid-sized firms. Talent competition, pricing pressure and varied regulation across countries restrain growth, but expanding corporate balance sheets support strong demand. Government-backed growth programs and a rising number of start-ups and unicorns also create advisory demand, and private equity funds are active in deals that need strategy and diligence support.
⮞On October 16, 2025, Deloitte opened an office in Indore, expanding its Indian footprint to 16 cities, following PwC's opening of a sixth location in the National Capital Region at Gurugram on July 28, 2025.
MEA & Latin America Strategic Consulting Services Market Insights
In Latin America, Brazil leads, followed by Mexico, Colombia, Chile and Argentina. Demand is driven by banking, energy, mining and consumer goods companies, and by governments seeking help on infrastructure and public finance. Global firms operate regional offices, while local advisers serve mid-sized clients, and economic volatility and currency swings moderate project budgets. Mexico, Colombia and Chile add steady work through banks and mining groups, and Argentina adds projects tied to restructuring and energy investments, while Central American countries buy smaller advisory packages.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar, Egypt and South Africa lead demand. National diversification programs, giga-projects and privatizations create large advisory mandates. On June 18, 2026, Roland Berger marked 20 years in the Middle East, with offices in Bahrain, the UAE, Qatar and Saudi Arabia, and said it is shifting from pure strategic advice toward execution support. Qatar and the United Arab Emirates add large mandates through sovereign funds and national plans, while Egypt, Nigeria and South Africa add demand through banking, telecom and public sector reform programs.
Market Dynamics
Growth Drivers: Uncertainty, AI Transformation and Deal Activity
Economic uncertainty, shifting trade rules and geopolitical risk push executives to seek outside views on strategy, supply chains and capital allocation. Transformation programs linked to AI, cloud and data require help on choices and sequencing. Rising interest rates and capital cost shifts also lead boards to revisit investment plans and operating models. Pressure on boards from investors also raises demand.
Mergers and acquisitions, private equity activity and restructuring create steady demand for due diligence, integration and portfolio advice. Sustainability rules and energy transition planning add a further stream of advisory work. Climate disclosure rules and supply chain scrutiny also generate advisory projects for companies in many industries.
Restraints: Fee Pressure, In-House Teams and AI Substitution
Procurement teams push for lower fees, fixed-price work and outcome-based contracts, which compress margins. Many large companies have built internal strategy and analytics teams that handle work once sent to outside firms. Clients also compare firms on price more closely than before, which weakens traditional premium pricing. Cyclical downturns can cut discretionary projects quickly.
AI tools can automate research, modeling and slide production, which may reduce the hours that clients are willing to pay for. Demand for senior advice can also fall quickly during economic downturns. Talent costs and turnover at junior levels also affect project delivery and profitability for consulting firms.
Opportunities: Execution Services, Sector Specialization and Emerging Markets
Firms that combine strategy with implementation, managed services and proprietary software can capture larger and longer engagements. Acquisitions of boutiques and software assets help broaden capability. Partnerships with cloud, software and AI vendors also open channels to new clients and joint offers.
Sector specialization in areas such as energy transition, healthcare, defense and public finance offers premium pricing. Growth in Asia Pacific, the Middle East and Latin America opens new client bases for firms that invest in local teams. Public sector reform and infrastructure programs also supply multi-year advisory mandates.
Recent Developments:
-
2026: FTI Consulting, Inc. expanded its transactions, shareholder activism, and issues-management capabilities through two senior hires in its Strategic Communications segment.
-
2026: KPMG announced a strategic alliance with OpenAI to help organizations redesign enterprise workflows around AI, with a focus on AI-native experiences and process transformation.
-
2025: IBM Consulting opened an Innovation Hub powered by Red Hat at its Client Innovation Center in Bengaluru to help clients explore hybrid cloud and AI transformation.
Strategic Consulting Services Market Key Players
-
McKinsey & Company
-
Boston Consulting Group
-
Bain & Company
-
Deloitte Touche Tohmatsu Limited
-
Accenture plc
-
PricewaterhouseCoopers
-
Ernst & Young Global Limited (EY-Parthenon)
-
KPMG International Limited
-
Oliver Wyman LLC
-
Roland Berger GmbH
-
Capgemini Invent
-
Kearney
-
L.E.K. Consulting
-
Arthur D. Little
-
IBM Consulting
-
Alvarez & Marsal
-
FTI Consulting, Inc.
-
Altman Solon
-
Simon-Kucher & Partners
-
OC&C Strategy Consultants
Strategic Consulting Services Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 63.80 Billion |
| Market Size by 2035 | USD 120.89 Billion |
| CAGR | CAGR of 6.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Service Type (Corporate Strategy, Operations Strategy, Financial Advisory, Human Capital Strategy, Technology Strategy, Others) • By Enterprise Size (Large Enterprises, Small and Medium Enterprises) • By Industry Vertical (BFSI, Healthcare and Life Sciences, Manufacturing, IT and Telecom, Retail and Consumer Goods, Energy and Utilities, Public Sector, Others) • By Delivery Mode (On-Site and Hybrid, Digital and Remote) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | McKinsey & Company, Boston Consulting Group, Bain & Company, Deloitte Touche Tohmatsu Limited, Accenture plc, PricewaterhouseCoopers, Ernst & Young Global Limited (EY-Parthenon), KPMG International Limited, Oliver Wyman LLC, Roland Berger GmbH, Capgemini Invent, Kearney, L.E.K. Consulting, Arthur D. Little, IBM Consulting, Alvarez & Marsal, FTI Consulting, Inc., Altman Solon, Simon-Kucher & Partners, OC&C Strategy Consultants |

Frequently Asked Questions
Key players include McKinsey & Company, Boston Consulting Group, Bain & Company, Deloitte Touche Tohmatsu Limited, Accenture plc, PricewaterhouseCoopers (Strategy&), Ernst & Young Global Limited (EY-Parthenon) and KPMG International Limited.
Key opportunities include execution and managed services alongside advice, sector specialization in areas such as energy transition and healthcare, and growth in emerging markets.
The major growth factor is demand for advice on AI-led transformation, deals and restructuring amid economic and geopolitical uncertainty.
By Service Type, the Corporate Strategy segment dominated the market in 2025 with an estimated 31.00% share, supported by board-level demand for growth and portfolio advice.
North America dominated the market with a share of 40.00% in 2025, driven by corporate headquarters, private equity activity and technology spending.
