
Stretch Sleeve & Shrink Sleeve Labels Market Report Scope & Overview:
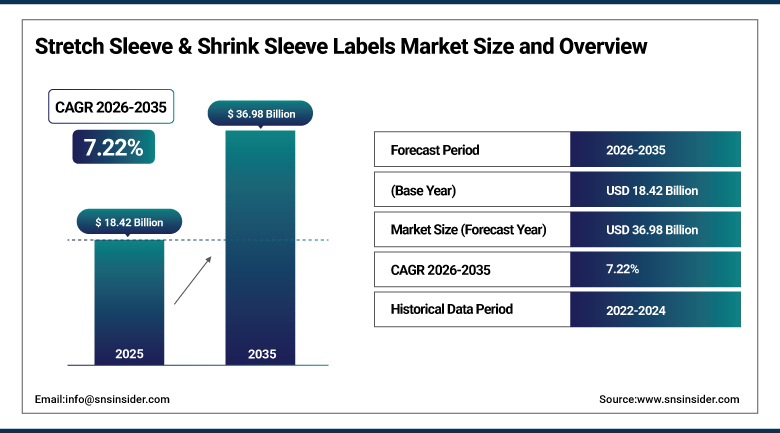
The Stretch Sleeve & Shrink Sleeve Labels Market was valued at USD 18.42 Billion in 2025 and is expected to reach USD 36.98 Billion by 2035, growing at a CAGR of 7.22% from 2026-2035.
The Stretch Sleeve & Shrink Sleeve Labels market includes full body and partial film polymer labels for bottles, containers, and packaging in beverages, food, personal care, and pharmaceutical industries which provide comprehensive branding solutions, secure tamper evidence seals, and shelf differentiation not possible with pressure-sensitive labels. The major demand driver for this market is from the beverage brand owners who are utilizing the shrink sleeve labels for full body graphic decoration on contoured bottles and cans which enables high-end shelf presentation. Pressure on the reduction of usage of PVC based on regulatory requirements such as the European Union's limit of lead in PVC packaging set to take effect from November 2024 is leading to increased use of materials such as PETG along with other recyclable polymer films despite being expensive compared to PVC. Digital printing is bringing down the minimum order quantity which gives small-scale craft beverage and specialty food producers access to sleeve labels.
In March 2026, CCL Industries signed a binding option agreement to acquire Sleever, a shrink sleeve label manufacturer headquartered near Paris with 11 manufacturing sites across Canada, France, Germany, Belgium, Ireland, Poland, China, and Brazil, generating approximately USD 213 million in 2025 sales.
To Get more information Stretch Sleeve & Shrink Sleeve Labels Market - Request Free Sample Report
Stretch Sleeve & Shrink Sleeve Labels Market Trends
-
Accelerating shift from PVC toward PETG and other recyclable polymer films amid tightening EU packaging regulation.
-
Growing adoption of digital inkjet printing to lower minimum order quantities for craft and niche beverage brands.
-
Rising demand for wash-off and light-blocking sleeve technologies that support bottle-to-bottle PET recycling.
-
Expanding use of tamper-evident and serialized shrink sleeves in pharmaceutical and healthcare packaging.
-
Continued consolidation among global converters pursuing acquisitions to expand international manufacturing footprints.
U.S. Stretch Sleeve & Shrink Sleeve Labels Market Outlook
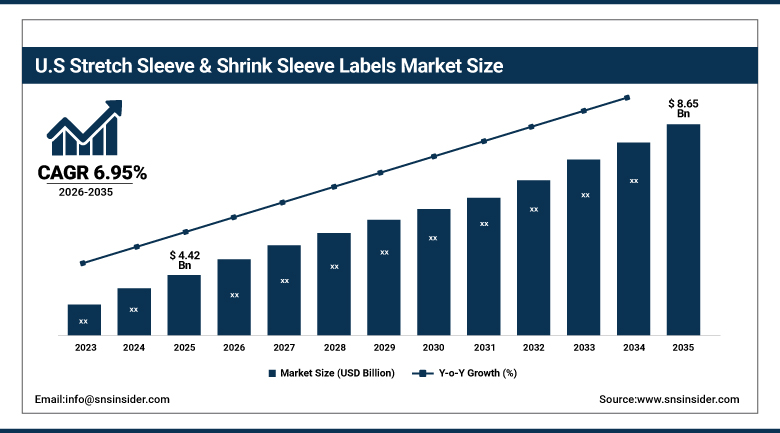
The U.S. Stretch Sleeve & Shrink Sleeve Labels Market was valued at USD 4.42 Billion in 2025 and is expected to reach USD 8.65 Billion by 2035, growing at a CAGR of 6.95% from 2026-2035.
Stretch sleeves and shrink sleeves labels continue to see significant demand from the United States for use in premium shelf differentiation and promotion, supported by an abundant presence of beverage and personal care manufacturers in the country using full body sleeve labeling to achieve such aims. Leading U.S. sleeve converters include Berry Global, CCL Industries, and Multi-Color Corporation, all of which have developed robust manufacturing capabilities in the region in order to provide their clients with beverages and consumer goods with the quick turnaround time that is demanded by seasonal label programs. Increasing demands for recyclability from brand owners will favor mono-material sleeve labeling options including PETG.
In September 2025, Berry Global opened a new manufacturing facility in Mexico to expand production of stretch sleeve labels, enhancing its ability to serve the North American market with reduced shipping costs and improved delivery times. The investment reflects a broader nearshoring trend among converters serving.
Stretch Sleeve & Shrink Sleeve Labels Market Segment Analysis
-
By Polymer Film, the PVC segment dominated the Stretch Sleeve & Shrink Sleeve Labels Market with approximately 44.85% share in 2025, while the PETG segment is the fastest growing with a CAGR of approximately 9.60%.
-
By Embellishing Type, the Hot Foil segment dominated the Stretch Sleeve & Shrink Sleeve Labels Market with approximately 67.00% share in 2025, while the Cold Foil segment is the fastest growing with a CAGR of approximately 8.75%.
-
By Embellelishing, the Soft Drinks segment dominated the Stretch Sleeve & Shrink Sleeve Labels Market with approximately 25.00% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 9.85%.
By Polymer Film, PVC dominates, and PETG grows fastest
PVC was the largest polymer film type in 2025 due to its low-cost nature, shrink properties, and the fact that it has been the standard sleeve film type used for beverages and food for many years. The converters have chosen to use PVC in cost-conscious high volume applications due to its superior shrinking ratio and printing properties despite the increased regulation pressure on the product.
PETG is the fastest-growing polymer film market owing to increasing regulation and efforts by brand owners to switch from PVC to PETG films in their production process due to the increased regulations such as the EU cap on lead in PVC in packaging products set to take effect in November 2024. Beverage companies have especially been focusing on PETG sleeves to promote bottle-to-bottle recycling without removing the sleeves.
By Embellishing Type, Hot Foil dominates, and Cold Foil grows fastest
In 2025, hot foil decoration represented the market leader in terms of market share owing to the brand owner's preference for premium metallic and holographic effects that make their beverages, spirits, and personal care packages stand out on retail shelves. The time-tested suitability of hot foil decoration in combination with high-speed gravure and flexographic printing equipment has ensured that hot foil becomes the standard premium decoration method of choice in the manufacture of high volume sleeve labels.
The cold foil segment represents the fastest growing segment due to the similarities of cold foil decoration with hot foil decoration in terms of offering premium visual effects but at reduced energy input and increased press speed. Cold foil decoration's technological advancements in recent years have significantly decreased the visual gap between hot foil and cold foil decoration, thus making it a better option for brand owners with low energy production requirements.
By Embellelishing, Soft Drinks dominates, and Healthcare grows fastest
The Soft Drinks sector accounted for the largest application market share in 2025, owing to the extensive use of the full-body shrink sleeves for beverages, which enable brilliant branding all around the bottle or can to ensure premium shelf presence and regular packaging redesigns in this industry. The high turn-over rate in soft drink packagings, along with seasonal and limited edition label printing, enables consistent high sleeve label volumes in the application.
Healthcare is the fastest growing segment among all applications due to increasing usage of tamper-proof and serialized shrink sleeve labels by pharmaceutical firms to satisfy the needs of regulation compliance, counterfeiting issues, and product traceability in the wide range of pharmaceutical and medical devices packaging. Increasing demands for serialization on a global scale, as well as counterfeiting concerns regarding pharmaceutical products, drive continuous investments into security enhanced sleeve labels.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
80.15 |
|
Europe |
Germany |
31.40 |
|
Asia Pacific |
China |
42.65 |
|
Middle East & Africa |
United Arab Emirates |
34.20 |
|
Latin America |
Brazil |
50.85 |
North America Stretch Sleeve & Shrink Sleeve Labels Market Insights
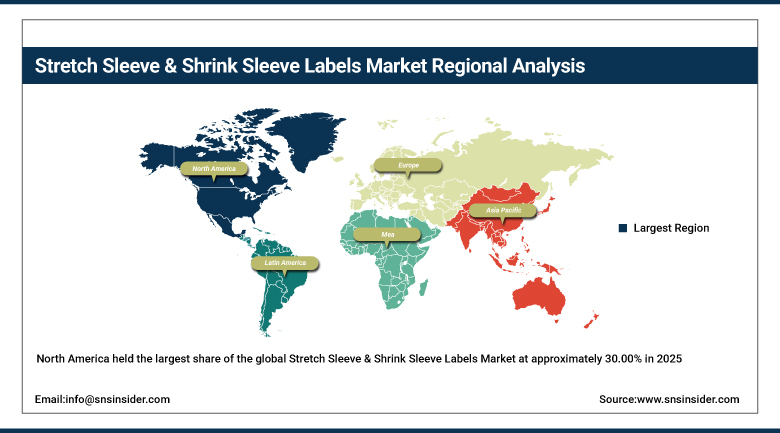
North America held the largest share of the global Stretch Sleeve & Shrink Sleeve Labels Market at approximately 30.00% in 2025, driven by a mature beverage and personal care manufacturing base that relies heavily on full-body sleeve labeling for premium shelf differentiation. The United States accounted for the substantial majority of regional demand, supported by extensive converter manufacturing networks operated by Berry Global, CCL Industries, and Multi-Color Corporation.
Growing brand owner commitments to packaging recyclability are reshaping regional material specifications toward PETG and other mono-material sleeve constructions, while continued nearshoring investment, including new converter manufacturing capacity in Mexico, is strengthening the region's ability to serve North American beverage and consumer goods brands with shorter lead times. Canada contributes additional regional demand through its own beverage and food manufacturing sectors.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Stretch Sleeve & Shrink Sleeve Labels Market Insights
Asia Pacific is the fastest-growing region within the Stretch Sleeve & Shrink Sleeve Labels Market, estimated to grow at a CAGR of around 8.30% during the forecast period of 2026-2035, backed by the rapid consumption growth in beverages, growth in the middle class, and the increasing trend towards eye-catching packaging in China, India, and Southeast Asia. In China, the large number of local converters supports not only the rapidly growing local demand in beverages and personal care, but also high exports of products to other developing nations.
In India, the growth in the manufacture of soft drinks and personal care products, along with the increasing packaging requirements of pharmaceutical packaging due to serialization requirements, is generating strong incremental regional demand. The growing urbanization and increasing consumer preference for premium packaging are anticipated to keep Asia Pacific on its strong growth path during the forecast period.
Europe Stretch Sleeve & Shrink Sleeve Labels Market Insights
Europe represents a mature stretch sleeve and shrink sleeve labels market, shaped significantly by evolving packaging waste regulation, including the European Union's cap on lead content in PVC packaging that took effect in November 2024, which is accelerating converter and brand owner transitions toward PETG and other more readily recyclable polymer films. Germany leads regional demand, supported by its large beverage and personal care manufacturing base and a well-established converter industry.
France, Italy, and the United Kingdom contribute significant additional regional demand through their own beverage, wine and spirits, and personal care sectors, each with strong traditions of premium packaging design that favor full-coverage sleeve labeling. Continued regulatory tightening under the EU's packaging and packaging waste rules is expected to keep material innovation and recyclability at the center of regional competitive strategy through the forecast period.
MEA & Latin America Stretch Sleeve & Shrink Sleeve Labels Market Insights
The Middle East & Africa stretch sleeve and shrink sleeve labels market is expanding as Gulf Cooperation Council states invest in beverage bottling and consumer goods manufacturing capacity, with the United Arab Emirates driving the bulk of regional demand given its large beverage distribution and hospitality sectors. Growing retail modernization across the broader region is expected to support continued adoption of premium sleeve labeling over the forecast period.
Latin America is led by Brazil, where a large domestic beverage industry and growing personal care manufacturing sector are driving sustained demand for sleeve labels, supported by regional converter manufacturing capacity including facilities operated by global players such as Sleever. Mexico's expanding role as a nearshore manufacturing base for North American beverage and consumer goods brands is contributing additional regional demand as converters expand capacity to serve the broader North American market from Mexican facilities.
Market Dynamics
Growth Drivers: Beverage Branding Demand and Packaging Regulation
Continued strong demand for high-value full-surface branding on bottles and cans will continue to drive demand for stretch sleeves and shrink sleeves, with brand owners utilizing the 360-degree graphics capability to get their products noticed on the shelves through continuous promotional campaigns and differentiate themselves in extremely competitive beverage sectors.
Increasing regulation, specifically in the form of the cap on lead content in PVC packaging in the European Union along with overall increased recycled content requirements for packaging and packaging waste according to the EU packaging and packaging waste directive, is adding momentum behind new-generation sleeve materials, including PETG and wash-off ink systems, which enable bottle-to-bottle recycling.
This regulatory push is creating a product cycle driven by regulations alongside the existing beverage-driven organic demand cycle.
Restraints: Recyclability Challenges and Material Cost Volatility
Despite growing adoption of more recyclable polymer films, shrink and stretch sleeve labels continue to face recyclability challenges relative to pressure-sensitive labels, since full-body sleeves must be removed or must share identical polymer composition with the underlying container to avoid contaminating recycling streams. This technical constraint continues to draw scrutiny from packaging waste regulators and sustainability-focused brand owners evaluating alternative labeling formats.
Polymer film manufacturing costs remain exposed to petrochemical feedstock price volatility, creating margin pressure for converters during periods of raw material price spikes that cannot always be immediately passed through to brand owner customers under existing supply agreements. This cost volatility is a persistent restraint on converter profitability, particularly as the industry simultaneously invests in transitioning production lines toward newer, often more expensive recyclable film formulations.
Opportunities: Wash-Off Technology and Digital Printing for Short Runs
Innovations in wash-off ink and adhesives, which make it possible to easily remove shrink sleeves from PET bottles through existing recycling methods, offer an important chance for converters to meet brand owners' requirements for recyclability without moving away from their current sleeve materials. Manufacturers of systems that provide efficient wash-off solutions are in prime position to enjoy a premium on their products, since beverage brands looking for circular packaging solutions are very likely buyers.
The growth of digital inkjet printing technology provides another chance through the reduction of the minimum quantity of orders for sleeve labels. The result is the opening up of the segment for craft beverages and smaller personal care brands, which had been priced out of the traditional gravure-printed sleeve labels market.
Recent Developments:
-
March 2026- CCL Industries signed a binding option agreement to acquire Sleever, a shrink sleeve label manufacturer with 11 manufacturing sites across 8 countries generating approximately USD 213 million in 2025 sales.
-
January 2025- Klöckner Pentaplast launched SmartCycle, a recyclable shrink film designed for beverage PET bottles to support brand owner circular packaging commitments.
-
September 2025- Berry Global opened a new manufacturing facility in Mexico to expand production of stretch sleeve labels serving the North American market.
-
April 2024- Nestlé launched a new recyclable shrink sleeve label with light-blocking print technology across its Nesquik ready-to-drink beverage line to support PET bottle recycling.
-
February 2024- CCL Industries officially inaugurated its new sustainable sleeve label hub in Dornbirn, Austria, a EUR 50 million investment relocating and expanding capacity from its previous Hohenems facility.
Stretch Sleeve & Shrink Sleeve Labels Market Key Players
-
CCL Industries Inc.
-
Berry Global, Inc.
-
Avery Dennison Corporation
-
Huhtamaki Oyj
-
Klöckner Pentaplast Group
-
Amcor plc
-
Fuji Seal International, Inc.
-
Taghleef Industries
-
Multi-Color Corporation
-
Mondi plc
-
Schreiner Group GmbH & Co. KG
-
WestRock Company
-
Macfarlane Group plc
-
Fort Dearborn Company
-
Bonset America Corporation
-
Sleever International
-
Inovar Packaging Group
-
Resource Label Group, LLC
-
The Dow Chemical Company
-
Edwards Label, Inc.
Stretch Sleeve & Shrink Sleeve Labels Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 18.42 Billion |
| Market Size by 2035 | USD 36.98 Billion |
| CAGR | CAGR of 7.22% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Polymer Film (PVC, PETG, OPS, PE, and Others) • by Embellishing Type (Hot Foil and Cold Foil) • by Embellelishing (Soft Drinks, Food, Personal & Beauty Care, Healthcare, and Wine & Spirit) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CCL Industries Inc., Berry Global, Inc., Avery Dennison Corporation, Huhtamaki Oyj, Klöckner Pentaplast Group, Amcor plc, Fuji Seal International, Inc., Taghleef Industries, Multi-Color Corporation, Mondi plc, Schreiner Group GmbH & Co. KG, WestRock Company, Macfarlane Group plc, Fort Dearborn Company, Bonset America Corporation, Sleever International, Inovar Packaging Group, Resource Label Group, LLC, The Dow Chemical Company, Edwards Label, Inc. |
Frequently Asked Questions
Key players in the Stretch Sleeve & Shrink Sleeve Labels Market include CCL Industries Inc., Berry Global, Inc., Avery Dennison Corporation, Huhtamaki Oyj, and Klöckner Pentaplast Group, among others.
Key opportunities lie in wash-off ink and adhesive technology that improves sleeve label recyclability, and in expanding digital printing capacity that lowers minimum order quantities for craft and specialty brands.
Sustained beverage industry demand for premium, full-coverage branding, combined with evolving packaging regulation accelerating the shift toward recyclable polymer films, is the major growth factor.
By Polymer Film, the PVC segment dominated the Stretch Sleeve & Shrink Sleeve Labels Market with approximately 44.85% share in 2025.
North America dominated the Stretch Sleeve & Shrink Sleeve Labels Market with approximately 30.00% share in 2025, supported by a mature beverage and personal care manufacturing base.
