
Sustainable Plastic Packaging Market Report Scope & Overview:
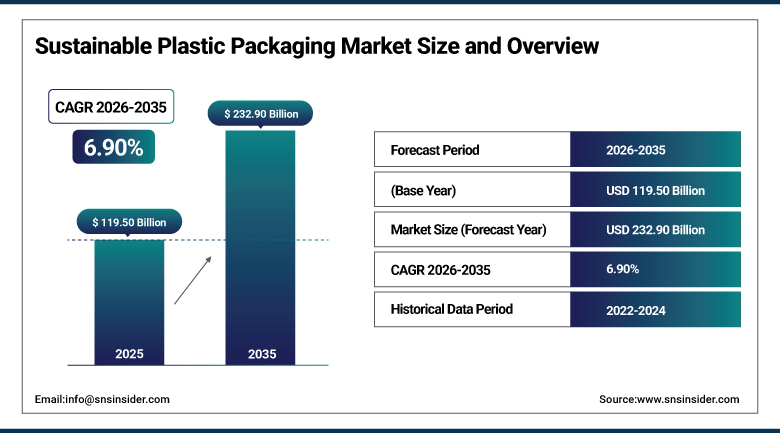
The Sustainable Plastic Packaging Market was valued at USD 119.50 Billion in 2025 and is expected to reach USD 232.90 Billion by 2035, growing at a CAGR of 6.90% from 2026-2035.
Sustainable plastic packaging has evolved from a voluntary corporate compliance category into a genuinely regulated industry, as recycled-content mandates in the United States, extended producer responsibility laws across Europe, and outright plastic taxes in the UK now push brand owners toward measurable, verifiable sustainability outcomes rather than marketing claims alone. Flexible formats, including mono-material films and recycled-content laminates, continue to carry the bulk of volume because they deliver comparable barrier performance to conventional plastic at a lower cost premium than rigid alternatives. Fresh produce, snacks, dairy, and ready-to-eat meals sit at the center of demand, since these categories generate some of the highest single-use plastic volumes and face the sharpest regulatory scrutiny as governments target the most visible sources of packaging waste.
Berry Global and Mars announced a partnership in March 2025 aimed at transitioning Mars' confectionery and pet food packaging toward 100% recyclable materials, a deal that matters less for its individual volume than for what it signals about how large consumer packaged goods companies are now locking in multi-year recycled-content commitments with their core suppliers rather than treating sustainability as a marketing initiative layered on top of existing packaging specifications. Poland separately implemented a deposit return system for plastic bottles in 2025 alongside tightening national recycling laws, part of a broader wave of EU member-state regulation that continues to push converters toward genuinely recyclable, mono-material film and bottle designs across the region.
To Get more information Sustainable Plastic Packaging Market - Request Free Sample Report
Sustainable Plastic Packaging Market Trends
-
Recycled-content mandates across the U.S., UK, and EU are converting sustainable packaging from a voluntary initiative into a binding compliance requirement.
-
Mono-material flexible film adoption continues accelerating as brand owners prioritize genuine curbside recyclability over composite multilayer structures.
-
Retailers including Carrefour and Tesco are expanding recycled-content shrink wrap, stretch film, and pallet wrap adoption across logistics and transport packaging.
-
Bioplastic and biodegradable material investment continues rising as brands seek alternatives that reduce end-of-life environmental impact beyond recyclability alone.
-
Healthcare and pharmaceutical packaging is increasingly adopting recycled and recyclable plastic formats as regulatory scrutiny expands beyond food and beverage categories.
U.S. Sustainable Plastic Packaging Market Outlook
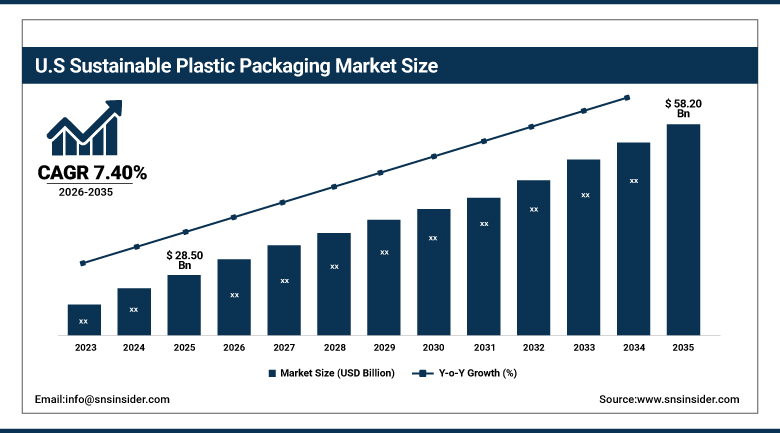
The U.S. Sustainable Plastic Packaging Market was valued at approximately USD 28.50 Billion in 2025 and is expected to reach approximately USD 58.20 Billion by 2035, growing at a CAGR of approximately 7.40%.
The U.S. market is increasingly shaped by state-level recycled-content mandates, particularly in California and Washington, which require minimum recycled plastic percentages in specific packaging categories and are pushing national brand owners toward standardized, compliance-ready specifications across their entire product portfolios. Growing retailer sustainability scorecards from major grocery chains continue to accelerate this shift, converting what was once a differentiated brand positioning into a baseline supplier requirement across food, beverage, and personal care categories.
Berry Global expanded its recycled-content flexible film production capacity in the United States through 2024 and 2025, aiming to meet growing demand from national food and beverage brands navigating California's recycled-content mandate ahead of its compliance deadlines. The investment reflects a broader pattern among large U.S. converters, who are increasingly building dedicated recycled-resin processing lines rather than treating recycled content as an incremental blend into existing virgin-resin production, a shift that better positions them to guarantee consistent recycled-content percentages across large national brand contracts.
Sustainable Plastic Packaging Market Segment Analysis
-
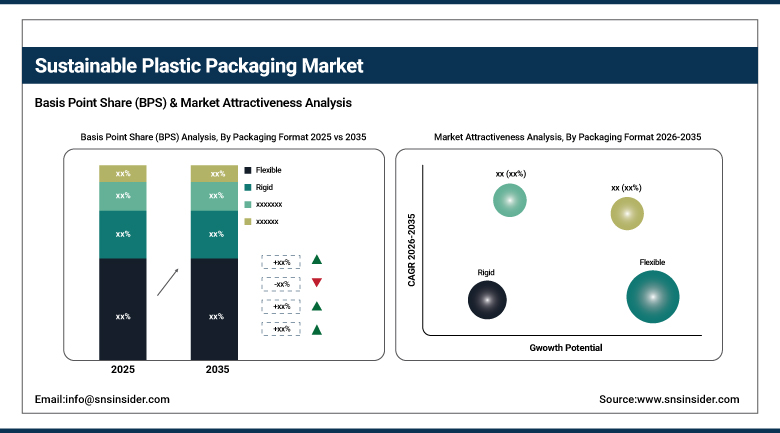
By Packaging Format, the Flexible segment dominated the Sustainable Plastic Packaging Market with approximately 65.00% share in 2025, while the Rigid segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Function, the Primary segment dominated the Sustainable Plastic Packaging Market with approximately 58.40% share in 2025, while the Secondary segment is the fastest growing with a CAGR of approximately 8.60%.
-
By Material, the Recycled/PCR Plastics segment dominated the Sustainable Plastic Packaging Market with approximately 42.30% share in 2025, while the Bioplastics segment is the fastest growing with a CAGR of approximately 9.40%.
-
By End-User, the Food & Beverage segment dominated the Sustainable Plastic Packaging Market with approximately 48.60% share in 2025, while the Healthcare segment is the fastest growing with a CAGR of approximately 8.90%.
By Packaging Format, flexible dominates, rigid grows fastest
Flexible packaging was the most successful category in terms of format in 2025, accounting for roughly 65.00% of the market share, offering mono-material films and recycled content laminates that provide barrier properties on par with traditional plastics but have a lesser cost premium compared to rigid materials. Flexible packaging is also more cost-effective and sustainable since it is lighter and less bulky and therefore emits fewer transport emissions than rigid material options, which make it more attractive to brands looking at the overall sustainability performance of their products.
Rigid packaging is the fastest-growing format segment, expanding at a CAGR of approximately 8.20% over the forecast period, as brands increasingly specify recycled PET and rPP for bottles, tubs, and clamshells where structural protection matters more than material minimization. Growing retailer demand for shelf-stable, tamper-evident rigid formats in fresh produce and healthcare categories continues reinforcing this segment's above-market growth. E-commerce shipping growth is also reinforcing rigid format demand, as protective, stackable containers increasingly replace flexible pouches for products requiring greater impact resistance during parcel delivery.
By Function, primary dominates, secondary grows fastest
Primary packaging dominated the function segment in 2025 with approximately 58.40% share, since this is the packaging layer in direct contact with the product and therefore the layer most visible to consumers and most heavily scrutinized under recycled-content and recyclability regulation across food, beverage, and personal care categories. Brand owners face the most direct consumer and regulatory visibility at this packaging layer, making primary packaging the first target for recycled-content specification and sustainability marketing claims alike.
Secondary packaging is the fastest-growing function segment, expanding at a CAGR of approximately 8.60% over the forecast period, as major retailers including Carrefour and Tesco expand recycled-content shrink wrap, stretch film, and pallet wrap adoption across logistics operations. Growing e-commerce shipping volumes continue to add incremental secondary packaging demand that increasingly must meet the same recyclability standards as primary formats. Growing warehouse automation adoption is also reshaping secondary packaging specifications, as automated handling systems increasingly require more standardized, machine-compatible recycled-content film dimensions.
By Material, recycled/PCR plastics dominates, bioplastics grows fastest
Recycled and post-consumer resin plastics led the material type segment in 2025 with a market share of around 42.30%, owing to mandatory content requirements for PCR adoption in the U.S., UK, and EU countries, which render PCR adoption a necessity rather than an optional sustainability measure for brand owners selling their goods in these regulated markets. There has been a tendency among converters to enter into long-term supply agreements for recycled resins directly with recyclers in order to ensure consistent quality and availability of materials before impending compliance deadlines.
The fastest growing material type segment is the bioplastics segment, which is projected to grow with a CAGR of approximately 9.40%. Brands are seeking out plant-based solutions that provide them a more sustainable solution, beyond recyclability, by minimizing environmental impact at the end of life. Further reductions in the price differential of bio-based resins compared to conventional and recycled resins is expected as the cost of producing bio-based resins continues to decline.
By End-User, food & beverage dominates, healthcare grows fastest
Food and beverage dominated the end-user segment in 2025 with approximately 48.60% share, driven by the category's scale and the intensity of regulatory scrutiny it faces, since fresh produce, snacks, dairy, and ready-to-eat meals generate some of the highest volumes of single-use plastic packaging of any consumer category. Personal care and cosmetics brands are also increasingly adopting recycled and recyclable plastic packaging, driven by similar retailer sustainability scorecard pressure seen across food and beverage categories.
Healthcare emerges as the fastest-growing end-user market, growing at a CAGR of around 8.90% during the forecast period, as the packaging of drugs and medical devices increasingly turns toward the use of recycled and recyclable plastics. The increasing focus on the issue of recycling healthcare packaging, which had been excluded largely from the regulations that food packaging has to adhere to, keeps boosting the growth rates of this segment. Medical devices companies are also starting to consider recycled content packaging for their non-sterile products, an area which was totally untouched until now.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
39.60% |
|
North America |
United States |
80.20% |
|
Europe |
Germany |
25.80% |
|
Latin America |
Brazil |
32.40% |
|
Middle East & Africa |
Saudi Arabia |
23.60% |
North America Sustainable Plastic Packaging Market Insights
North America is the fastest-growing region in the Sustainable Plastic Packaging Market, expanding at a CAGR of approximately 8.70% over the forecast period, driven by binding state-level recycled-content mandates in California and Washington alongside strong retailer sustainability scorecard pressure across major grocery and consumer goods chains. Growing investor and consumer attention to corporate sustainability performance continues to reinforce this regulatory momentum, pushing brand owners to treat compliance timelines as a competitive differentiator.
The United States accounts for the substantial majority of regional demand, with converters increasingly building dedicated recycled-resin processing capacity to meet growing compliance requirements. Canadian packaging regulation is following a similar trajectory, reinforcing the region's overall growth momentum. U.S. converters are also increasingly investing in domestic chemical recycling capacity, aiming to reduce reliance on imported recycled resin as compliance deadlines accelerate.
Europe Sustainable Plastic Packaging Market Insights
Europe represents a heavily regulated and mature sustainable plastic packaging market, with Germany leading regional demand through its large consumer goods manufacturing base and strict national recycling infrastructure. EU-wide extended producer responsibility laws continue to push converters toward genuinely recyclable, mono-material designs. Germany's advanced deposit return and recycling collection infrastructure continues to give the country a meaningfully higher effective recycling rate than most other European markets.
Poland has emerged as one of the fastest-developing European markets, implementing a plastic bottle deposit return system in 2025 alongside tightening national recycling laws. France and the UK contribute additional demand, both enforcing plastic taxes that directly incentivize recycled-content adoption. Scandinavian countries continue to serve as an early proving ground for next-generation recyclable packaging formats, often influencing broader EU regulatory standards before wider adoption follows.
Asia Pacific Sustainable Plastic Packaging Market Insights
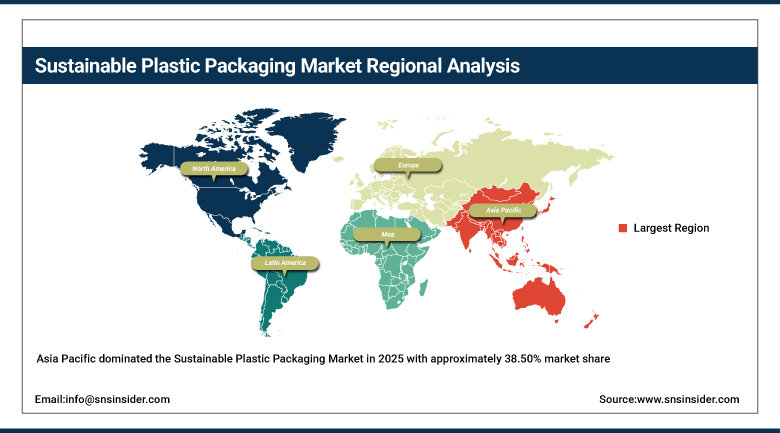
Asia Pacific dominated the Sustainable Plastic Packaging Market in 2025 with approximately 38.50% market share, supported by large-scale packaging manufacturing capacity and rapidly expanding consumer goods production across China and India, where growing domestic environmental regulation is increasingly pushing converters toward recyclable material specifications. Government-backed recycling infrastructure investment across several regional economies continues to expand the domestic supply of high-quality recycled resin available to converters.
China's massive packaging manufacturing base continues to anchor regional demand, while India's expanding food and beverage sector is driving rising adoption of recycled and recyclable plastic formats. Japan and South Korea continue contributing advanced material science research supporting the broader regional innovation base. Growing regional e-commerce penetration continues to add incremental demand for both primary and secondary sustainable packaging formats across the fast-growing Asia Pacific consumer goods sector.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Sustainable Plastic Packaging Market Insights
The Middle East and Africa constitute a smaller market which is emerging, with demand being driven in the region by Saudi Arabia through sustainability efforts in packaging and other areas related to its economic diversification objectives. The UAE is also adopting the same approach by positioning itself as a center for sustainable packaging innovation in the region to serve the neighboring Gulf states.
Latin America constitutes another emerging market with Brazil taking the lead. Increased regulation concerning plastic waste, alongside growth in the consumer goods market, continues to fuel the uptake of sustainable packaging. Mexico adds significant secondary demand due to its exports of food and beverages. The secondary demand for recycled and recyclable packaging is made up of Argentina and Colombia.
Market Dynamics
Growth Drivers: Regulatory mandates and corporate sustainability commitments fueling adoption
Binding recycled-content mandates and extended producer responsibility regulations across the U.S., UK, and EU continue converting sustainable plastic packaging from a voluntary brand initiative into a legal compliance requirement, creating durable, regulation-reinforced demand that is far less sensitive to economic cycles than purely discretionary sustainability spending would be. Non-compliance penalties under several of these regulatory frameworks are becoming steep enough that brand owners increasingly treat packaging sustainability investment as a direct cost-avoidance measure rather than a purely reputational one.
Corporate sustainability commitments continue expanding, with more than 60% of companies having pledged to use sustainable packaging, pushing brand owners to lock in multi-year recycled-content supply agreements with converters well ahead of regulatory compliance deadlines to ensure adequate material availability. Investor pressure through environmental, social, and governance reporting frameworks continues to reinforce this trend, as packaging sustainability metrics increasingly factor into corporate sustainability disclosures reviewed by institutional shareholders.
Restraints: Recycled material supply constraints and performance trade-offs limiting growth
The limited supply of high-quality post-consumer recycled resin continues to inhibit converters' ability to produce recycled products, sometimes forcing brand owners to fight over the limited available pool of recycled content in the periods when the resource is not abundant. The problem becomes even more pronounced in the case of food-grade recycled resin, which requires much higher quality compared to recycled content used in non-food applications.
Both recycled and bio-materials generally perform worse in barrier properties and clarity than virgin plastic, which leads to ongoing technical trade-offs and hampers the conversion process in cases where the best possible performance in terms of shelf life is required, especially for oxygen-sensitive food and pharmaceutical products. Perception barriers remain relevant, as the recycled and bio-packaging solutions continue to have the reputation of being low quality despite equal performance in most cases.
Opportunities: Chemical recycling advancement and healthcare category expansion widening demand
Advancement of chemical recycling technology, capable of processing previously non-recyclable multilayer plastic waste back into food-grade resin, presents a significant opportunity to expand the effective recycled material supply pool beyond what mechanical recycling alone can currently provide. Several major converters have announced dedicated chemical recycling facility investments, signaling growing confidence that this technology can reach commercial scale within the current decade.
The increased focus on regulation regarding waste generated from healthcare and pharmaceutical packaging provides an opportunity for converters to increase the adoption of recycled plastics in a market segment which has traditionally been behind food and beverage packaging in sustainability standards. Those companies which develop recycled packaging specifications early on that are compliant with healthcare requirements will have a competitive edge when pharma firms start adopting sustainability standards for procurement.
Recent Developments:
-
March 2025- Berry Global and Mars announced a partnership to transition Mars' confectionery and pet food packaging toward 100% recyclable materials across multiple global product lines.
-
2025- Poland implemented a deposit return system for plastic bottles alongside tightening national recycling laws, reinforcing EU-wide sustainable packaging compliance requirements.
-
2024- Berry Global expanded recycled-content flexible film production capacity in the United States to meet growing demand from national food and beverage brands.
-
2023- Amcor plc announced expanded investment in recyclable mono-material packaging development, targeting food and beverage customers seeking curbside-recyclable flexible film alternatives.
Sustainable Plastic Packaging Market Key Players
-
Amcor plc
-
Berry Global Inc.
-
Sealed Air Corporation
-
Sonoco Products Company
-
Mondi Group
-
Huhtamaki Oyj
-
Constantia Flexibles
-
Coveris Holdings
-
Winpak Ltd.
-
Uflex Ltd.
-
Sabic
-
Novolex Holdings, LLC
-
TotalEnergies Corbion
-
NatureWorks LLC
-
Tetra Pak International S.A.
-
Klockner Pentaplast
-
ProAmpac LLC
-
International Paper Company
-
DS Smith plc
-
Better Packaging Co.
Sustainable Plastic Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 119.50 Billion |
| Market Size by 2035 | USD 232.90 Billion |
| CAGR | CAGR of 14.77% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Packaging Format (Flexible, Rigid) • By Function (Primary, Secondary, Tertiary/Transport) • By Material (Recycled/PCR Plastics, Bioplastics, Biodegradable Plastics) • By End-User (Food & Beverage, Healthcare, Cosmetics & Personal Care, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor plc, Berry Global Inc., Sealed Air Corporation, Sonoco Products Company, Mondi Group, Huhtamaki Oyj, Constantia Flexibles, Coveris Holdings, Winpak Ltd., Uflex Ltd., Sabic, Novolex Holdings, LLC, TotalEnergies Corbion, NatureWorks LLC, Tetra Pak International S.A., Klockner Pentaplast, ProAmpac LLC, International Paper Company, DS Smith plc, Better Packaging Co. |
Frequently Asked Questions
Key players in the Sustainable Plastic Packaging Market include Amcor plc, Berry Global Inc., Sealed Air Corporation, Sonoco Products Company, and Mondi Group, among others.
Key opportunities include advancement of chemical recycling technology expanding the recycled material supply pool, and growing regulatory attention to healthcare and pharmaceutical packaging sustainability.
The market is driven by binding recycled-content mandates and extended producer responsibility regulations across major markets, alongside expanding corporate sustainability commitments.
The Flexible segment dominated the Sustainable Plastic Packaging Market, accounting for approximately 65.00% market share.
Asia Pacific dominated the Sustainable Plastic Packaging Market in 2025 with approximately 38.50% share, supported by large-scale manufacturing capacity across China and India.
