
Texture Paint Market Report Scope & Overview:
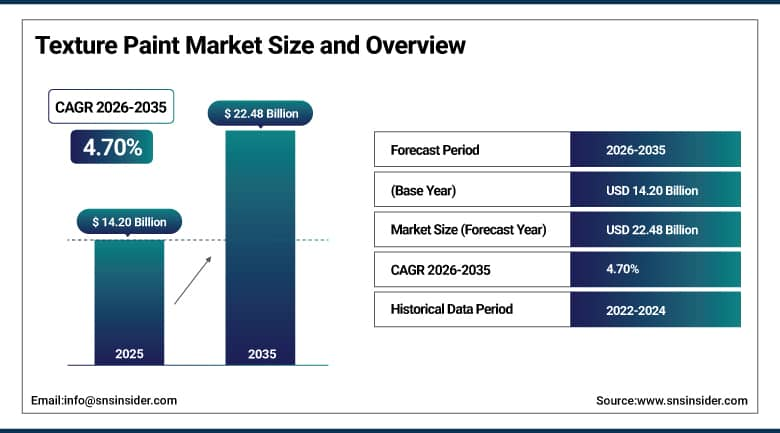
The Texture Paint Market was valued at USD 14.20 Billion in 2025 and is expected to reach USD 22.48 Billion by 2035, growing at a CAGR of 4.70% from 2026-2035.
The Texture Paint Market is growing at a steady pace as homeowners, builders and designers use sand, stucco, plaster-effect and metallic finishes to add depth, hide surface flaws and create distinctive interiors and facades. Growth is supported by rising residential construction and renovation in Asia Pacific, demand for premium decorative finishes, the spread of water-based low-VOC formulations and the popularity of do-it-yourself repair and decoration products. Manufacturers are widening color and texture ranges, introducing ready-to-apply systems that reduce skilled labor needs, and using visualization tools and experience stores that let customers see finishes before buying. Dealer networks, painter training and brand strength strongly influence purchase decisions in this category.
⮞Paint companies are investing in physical showrooms where customers can see and touch finishes. In May 2024, Nippon Paint partnered with Hoysala Associates to open the Nspire store in Bengaluru, India, equipped with interactive panels that show texture, finish and color options. The format reflects the importance of tactile selection in a category in which buyers want to see how a finish looks under real lighting before committing to an entire wall.
To Get More Information On Texture Paint Market - Request Free Sample Report
Texture Paint Market Trends
-
Shift from solvent-based to low-VOC water-based texture formulations
-
Growth of ready-to-apply and aerosol texture products for repairs and do-it-yourself projects
-
Rising demand for metallic, plaster-effect and natural stone-look finishes
-
Investment in experience stores and digital visualization tools
-
Expansion of painter training and dealer networks by leading brands
-
Use of recycled fillers and bio-based binders to lower environmental impact
U.S. Texture Paint Market Outlook
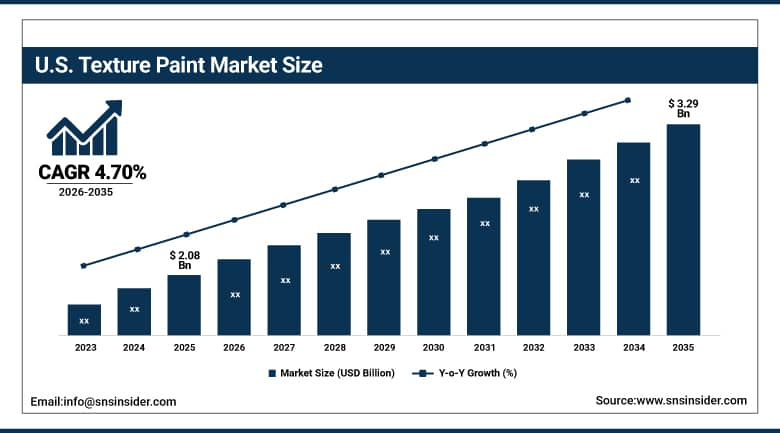
The U.S. Texture Paint Market was valued at USD 2.08 Billion in 2025 and is expected to reach USD 3.29 Billion by 2035, growing at a CAGR of 4.70% from 2026-2035.
The U.S. Texture Paint Market is the largest market in North America, supported by a large housing stock in which textured walls and ceilings, such as orange peel, knockdown and popcorn finishes, are common, and by an active repair and remodeling sector. Contractors apply texture over drywall and stucco, and homeowners buy aerosol and pail products for patching and updating. Retail channels such as home centers dominate sales to do-it-yourself buyers, while professional supply stores serve contractors. Demand for decorative plaster-effect and mineral finishes is rising in premium residential and hospitality projects. Regulations on volatile organic compounds and lead-safe renovation influence product design and application practice.
⮞Repair-focused texture products are being redesigned for convenience. On November 4, 2025, the Pittsburgh Paints Company's HOMAX brand launched HOMAX PRO GRADE Wall and Ceiling Texture, an aerosol that it says stays suspended in the can to resist clogging. Offered in Orange Peel and Knockdown finishes, with a patented adjustable nozzle intended to match original textures, each can covers up to 100 square feet. The product is sold at Home Depot, Menards and Lowe's stores across the United States and targets small drywall repairs for which a spray can is faster than a hopper gun.
Texture Paint Market Segment Analysis
-
By Resin Type, acrylic segment dominated the Texture Paint Market in 2025 with an estimated 88% share; epoxy segment is the fastest-growing, with an estimated CAGR of 7.2% from 2026 to 2035.
-
By Technology, water-based segment dominated the market in 2025 with an estimated 85% share; solvent-based segment is the fastest-growing, with an estimated CAGR of 6.5% from 2026 to 2035.
-
By Product Type, interior segment dominated the market in 2025 with an estimated 74% share; exterior segment is the fastest-growing, with an estimated CAGR of 7.1% from 2026 to 2035.
-
By Texture Finish, sand and granular segment dominated the market in 2025 with an estimated 30% share; stone effect segment is the fastest-growing, with an estimated CAGR of 8.0% from 2026 to 2035.
-
By Application, residential segment dominated the market in 2025 with an estimated 75% share; non-residential segment is the fastest-growing, with an estimated CAGR of 7.4% from 2026 to 2035.
By Resin Type, Acrylic Dominates Texture Paint Market; Epoxy to Register Fastest Growth.
Acrylic dominates the texture paint market owing to its flexibility, adhesion capabilities, color retention, and weather-resistance attributes. The acrylic formulations ensure durability, visual appeal, and easy application for residential interior and exterior walls, as well as compatibility with various decorative finishes and textures. Moreover, these paints have low maintenance capabilities and water-based formulations enabling lower emissions construction. Such characteristics explain why acrylic resins are widely used for decorative wall coatings in numerous construction projects.
Epoxy is expected to register the fastest growth due to growing preference for texture coatings providing better adhesion, hardness, and chemical, wear, and moisture resistance characteristics. Epoxy coatings are appropriate for specific applications requiring high-performance capabilities of decorative surfaces. The rising investments in commercial and industrial buildings, as well as refurbishment projects, create growth opportunities for high-end textured coatings. Moreover, such coatings can serve as a protective film ensuring low maintenance in certain cases. Nevertheless, epoxy usage is more limited in conventional decorative wall painting than the acrylic one and is dependent on performance requirements.
⮞In March 2026, China's Sengu New Materials launched Ceramic Coating Artistic Paint, incorporating silicone-acrylic odorless eco-friendly emulsion and porcelain-sand materials to deliver decorative wall textures with durability and environmental performance.
By Technology, Water-Based Dominates Texture Paint Market; Solvent-Based to Register Fastest Growth.
Water-based technology dominates the texture paint market owing to its low emissions of VOCs, lack of odor, easy applicability, and simple clean-up procedure. The water-based formulation is thus ideal for interior use due to its compatibility with indoor air quality concerns. The compatibility with acrylic binding agents and decorative textures also promotes the use of water-based products. The toughening of environmental standards, as well as the preference for sustainable materials, motivates manufacturers to include more water-based paints in their offerings. Water-based products are appropriate for both renovation, regular maintenance, and new building projects.
Solvent-based technology is expected to register the fastest growth in specialized applications where good adhesion, excellent film formation, and resistance to adverse environmental factors are essential properties of the formulation. While certain solvent-based formulations perform better than water-based ones in specific technical cases, such as challenging substrates, moisture, and extreme temperatures, demands from selected commercial, industrial, and outdoor projects can drive their expansion. Nevertheless, the increase in emissions regulations and occupational safety factors, as well as a trend towards low-VOC products, may limit their growth.
By Product Type, Interior Dominates Texture Paint Market; Exterior to Register Fastest Growth.
Interior texture paint dominates the market because homeowners and property developers increasingly use decorative wall finishes to enhance indoor aesthetics and conceal minor surface imperfections. Textured coatings provide visual depth, distinctive patterns, and design flexibility across living rooms, bedrooms, corridors, and other interior spaces. Rising residential renovation activity and demand for personalized interiors support their widespread application. Interior products are also available in multiple finishes and colors, allowing consumers to coordinate wall treatments with different architectural styles. Their suitability for new housing, remodeling, and interior refurbishment sustains demand across residential construction markets.
Exterior texture paint is expected to register the fastest growth as property owners seek durable finishes that improve building appearance while protecting façades against weather exposure. These coatings can help conceal minor surface irregularities and provide resistance to moisture, sunlight, and environmental deterioration, depending on formulation. Urban development, infrastructure expansion, and renovation of aging buildings are increasing opportunities for exterior decorative coatings. Growing interest in long-lasting façades that require less frequent maintenance further supports demand. Product innovations that improve weatherability, crack resistance, and color retention are expected to strengthen adoption across residential and non-residential construction projects.
⮞In April 2025, Birla Opus Paints introduced its Designer Finish range in India, featuring Dream and Timeless collections with 3D patterns, metallic effects and handcrafted decorative finishes designed for premium interior walls.
By Texture Finish, Sand and Granular Dominates Texture Paint Market; Stone Effect to Register Fastest Growth.
Sand and granular finishes dominate the texture paint market because they offer a practical combination of decorative appeal, surface concealment, and application versatility. Their distinctive textured appearance helps mask minor wall imperfections while creating visually appealing finishes for residential and commercial buildings. These coatings are available in different particle sizes and patterns, allowing users to achieve varied decorative effects without extensive surface modifications. Their suitability for interior and exterior applications, together with compatibility with established application techniques, supports broad market acceptance. Demand for cost-effective decorative wall treatments further strengthens the segment's position.
Stone effect finishes are expected to register the fastest growth as property owners increasingly seek premium architectural appearances without the installation complexity and structural burden associated with natural stone. These textured coatings can replicate the visual character of stone surfaces while offering flexibility in color, pattern, and application. Growing interest in contemporary façades, decorative feature walls, and upscale residential and commercial interiors is supporting adoption. Their potential to deliver distinctive architectural finishes at comparatively accessible installation costs further strengthens demand. Product innovations that improve realism, durability, and weather resistance are expected to expand their appeal across renovation and new construction projects.
⮞In March 2026, India's OnePlus Spark Paints introduced Marble Texture Coating, featuring processed coloured marble grains, multiple texture grades and stone-like decorative effects for interior and exterior walls, including commercial buildings and premium residential projects.
By Application, Residential Dominates Texture Paint Market; Non-Residential to Register Fastest Growth.
Residential applications dominate the texture paint market because homeowners increasingly prioritize decorative finishes that improve interior aesthetics and enhance exterior appearance. Texture paints offer varied patterns, surface depth, and the ability to conceal minor wall imperfections, making them suitable for new homes and renovation projects. Growing housing construction, urbanization, and rising interest in customized living spaces support demand. Their availability across multiple finishes and price points also enables adoption among different consumer groups. Continued investment in home improvement and property refurbishment is expected to sustain the residential segment's leading position.
Non-residential applications are expected to register the fastest growth as commercial property development and renovation increase demand for durable, visually distinctive wall finishes. Offices, hotels, retail outlets, educational institutions, healthcare facilities, and hospitality venues use texture paints to create attractive environments while addressing surface durability and maintenance requirements. Investment in commercial infrastructure and modernization of existing buildings is creating additional opportunities for decorative coatings. Architects and property developers are also incorporating specialized textures into contemporary design concepts. Demand for finishes that combine aesthetic differentiation with long-term performance is expected to support further adoption across non-residential construction projects.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
44.80 |
|
Europe |
Germany |
22.40 |
|
North America |
United States |
86.00 |
|
Latin America |
Brazil |
47.50 |
|
Middle East & Africa |
Saudi Arabia |
28.60 |
Asia Pacific Texture Paint Market Insights
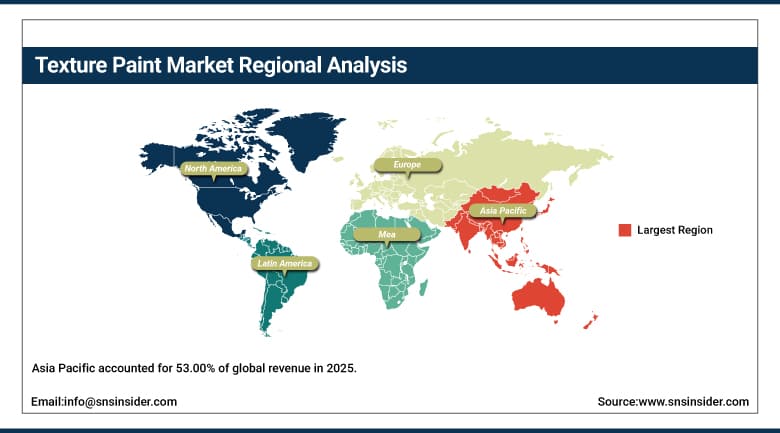
Asia Pacific accounted for 53.00% of global revenue in 2025, making it the largest regional market for texture paints, and it is also projected to be the fastest-growing region, advancing at a CAGR of 5.60% from 2026-2035. China leads regional demand through its huge residential and commercial construction sector, followed by India, Japan, South Korea and Southeast Asia. Rising incomes, urbanization and a strong culture of home decoration support demand for decorative finishes, and major paint companies compete aggressively through dealer networks and experience stores.
India is a major growth market, where established paint groups and new entrants are expanding capacity, launching texture ranges and investing in painter training. Japan and South Korea emphasize high-quality, low-emission products, while Southeast Asian countries adopt textured exteriors suited to humid climates. Price competition is intense, so brands differentiate with design collections, color visualization and bundled services. Real estate cycles, particularly in China, influence short-term volumes.
⮞In May 2026, China's State Council issued its 15th Five-Year Urban Renewal Plan, encouraging renovation of older residential communities, housing improvements and the adoption of new building materials, creating additional opportunities for decorative and protective architectural coatings.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Texture Paint Market Insights
North America accounted for roughly one-sixth of global revenue in 2025 and is led by the United States, with Canada and Mexico contributing. Growth is steady, tied to commercial construction, residential remodeling and the large installed base of textured drywall and stucco. Leading paint companies, home center chains and specialty brands compete with a broad range of products from aerosol repair textures to premium decorative plasters for designers and high-end residences.
Contractors value ready-to-apply products, fast drying and reliable matching of existing textures, while homeowners favor convenient packaging and low odor. Regulations on volatile organic compounds, particularly in California and the Northeast, shape formulations. Labor shortages in the painting trades encourage products that cut application time. Online sales, color visualization apps and social media inspiration are influencing purchases, and manufacturers are launching limited collections to refresh interest.
⮞In September 2026, Sherwin-Williams inaugurated its expanded architectural paint and coatings manufacturing facility in Statesville, North Carolina, adding production space, automation and rail infrastructure to strengthen manufacturing capacity and distribution across North America.
Europe Texture Paint Market Insights
Europe is a mature, renovation-driven market in which Germany, the United Kingdom, France and Italy lead spending. Textured plasters, mineral finishes and decorative interior coatings are well established, supported by a tradition of facade rendering and heritage restoration. Energy efficiency programs that add insulation to existing buildings create demand for external thermal insulation composite systems with textured finish coats, which are a major use of mineral and silicone-based textures.
Regulation is strict, with low-emission requirements and chemical rules shaping product development. Consumers favor eco-labeled products, and manufacturers emphasize recycled content, natural mineral fillers and bio-based binders. Do-it-yourself retail chains and professional trade counters both play important roles. Eastern European countries are growing faster as housing renovation programs expand, while Western markets focus on premium and specialty finishes.
⮞In July 2026, Germany continued its Federal Funding for Efficient Buildings programme following reforms approved by the government, maintaining financial support for residential and non-residential building renovations and strengthening incentives for building modernization.
MEA & Latin America Texture Paint Market Insights
In the Middle East and Africa, demand is concentrated in Saudi Arabia, the United Arab Emirates, Qatar and South Africa, where large-scale residential, hospitality and commercial construction projects use textured exterior finishes suited to heat, dust and sunlight. Regional manufacturers and global brands operate local plants, and high-end decorative effects are popular in villas and hotels. Giga-projects and housing programs add large tenders for facade and interior coatings.
In Latin America, Brazil and Mexico lead consumption, supported by a strong self-build and renovation culture in which textured wall finishes are widely used as an affordable decorative option. Regional paint groups have broad distribution through small retailers, and price sensitivity favors economical acrylic products. Currency volatility and construction cycles affect volumes. As incomes recover and formal housing programs expand, both regions are expected to add steadily to global revenue from a smaller base.
⮞In January 2026, Brazil's federal government reported that the Minha Casa, Minha Vida programme had reached two million contracted housing units by December 2025, supported by approximately BRL 340 billion in financing and government resources.
Market Dynamics
Growth Drivers: Construction Activity, Renovation and Design Preferences
Construction and renovation expenditure drive the demand for texture paints in residential and commercial sectors. Construction of new housing units, offices, hotels and commercial establishments creates the need for decorations, while repainting and renovation continue the demand for texture paints in established markets. Textured paints cover up small blemishes on surfaces, enhance the aesthetic appeal of walls, and cut down on some of the preparation needs making them an appealing option for both exterior and interior use.
Preference for design changes is another factor pushing the use of texture paints as people look for unique finishes like those of stucco, concrete, stones and metals. Social media and home improvement websites have increased the awareness about decorative options. The manufacturers are coming up with ready-to-use paints, more finish options and easy application techniques. Water-based, low emission products are popular with environmentally conscious consumers.
⮞In February 2026, the National Association of Home Builders reported that residential remodeling activity in the United States was expected to increase by 3% during 2026, with home improvement spending already representing 45% of residential construction expenditure in Q3 2025.
Restraints: Raw Material Costs, Skilled Labor and Construction Cycles
Raw materials' price volatility is a restriction for the producers of texture paints due to rising costs and uncertainties about profit margins. Binders, pigments, fillers and special additives are subject to changes in the prices of oil products, energy costs, transportation costs and supply interruptions. High level of competition and price sensitivity will make difficult to pass costs to customers, especially in conventional decorative paint types.
Another constraint in the industry is the availability of skilled personnel due to the need of experienced applicators to provide proper texture, coverage and decorative results. Poor quality work can lead to extra costs and dissatisfaction among customers. Economic recessions and fluctuations in the residential and commercial construction will slow down projects and decrease demand for decorative paints. Additional tests can be required due to environmental regulations. Budgetary customers will tend to purchase regular paints or wallpapers instead.
Opportunities: Premium Decorative Finishes, Insulation Systems and Do-It-Yourself Products
Premium decorative coatings present manufacturers with chances to enhance their product differentiation and margin opportunities. The increasing popularity of stone, concrete, stucco, metallic, and contemporary textured coating effect creates opportunities in interior decoration, hotel industry, restaurants, and commercial spaces. Manufacturers can capitalize on this by providing sample panels, visualization software, installer education and collaboration with architects and interior designers. Energy saving and renovation initiatives present additional opportunities where textured finish coatings can be used in facade systems.
Durable mineral, silicone and elastomeric coatings can be considered for projects where weather-resistance and durability of the surface is needed. Products that are ready to use and simplified application methods, along with relevant instructional materials, can appeal to homeowners who are carrying out renovation projects themselves. Demonstrations and tutorials on application of these coatings will minimize the uncertainties associated with it. Rapid urbanization, increasing income levels and construction of new housing in developing countries present other opportunities for manufacturers.
⮞In October 2025, Brazil launched Reforma Casa Brasil, a BRL 40 billion housing improvement financing programme supporting residential renovations, construction materials and labour costs, creating additional opportunities for decorative paint and wall-finishing product manufacturers.
Recent Developments
-
In January 2026, PPG's SEM Products business, working with 4Plastic, introduced texture coatings for refinishing nonpainted, textured plastic components. The products replicate common original equipment textures and let body shops use smartphone technology to identify and match each texture. They are available in the United States and Canada and are meant to reduce replacement costs and repair cycle times.
-
In March 2024, Jazeera Paints launched Jazeera Cantara, a new textured finish product, expanding its decorative range in the Middle East. The launch reflects regional demand for architectural effects suited to villas, hotels and commercial buildings in the Gulf.
-
In February 2024, Grasim Industries inaugurated the first three plants of its Birla Opus paint business in Panipat, Ludhiana and Cheyyar, India. The company's capacity build-out intensifies competition in decorative paints, including texture and premium finishes, and adds a large new supplier to the Indian market.
Texture Paint Companies:
-
Asian Paints Limited
-
AkzoNobel N.V.
-
Nippon Paint Holdings Co., Ltd.
-
PPG Industries, Inc.
-
The Sherwin-Williams Company
-
Berger Paints India Limited
-
Jotun A/S
-
RPM International Inc.
-
Hempel A/S
-
Behr Process Corporation
-
Benjamin Moore & Co.
-
DAW SE
-
JSW Paints
-
Axalta Coating Systems Ltd.
-
BASF SE
-
Tikkurila Oyj
-
Grasim Industries Limited
-
The Pittsburgh Paints Company
Texture Paint Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 14.20 Billion |
| Market Size by 2035 | USD 22.48 Billion |
| CAGR | CAGR of 4.70% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Resin Type (Acrylic, Epoxy, Others) • By Technology (Water-Based, Solvent-Based) • By Product Type (Interior, Exterior) • By Texture Finish (Sand and Granular, Stucco and Plaster, Stone Effect, Rustic and Fine Texture, Metallic and Specialty Finishes, Others) • By Application (Residential, Non-Residential) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Asian Paints Limited, AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., The Sherwin-Williams Company, Kansai Paint Co., Ltd., Berger Paints India Limited, Jotun A/S, RPM International Inc., Hempel A/S, Behr Process Corporation, Benjamin Moore & Co., DAW SE, Jazeera Paints, JSW Paints, Axalta Coating Systems Ltd., BASF SE, Tikkurila Oyj, Grasim Industries Limited, The Pittsburgh Paints Company |

Frequently Asked Questions
Key players include Asian Paints Limited, AkzoNobel N.V., Nippon Paint Holdings Co., Ltd., PPG Industries, Inc., The Sherwin-Williams Company, Kansai Paint Co., Ltd., Grasim Industries Limited and The Pittsburgh Paints Company.
Key opportunities include premium decorative finishes such as plaster, concrete and metallic effects, textured coatings for insulated facades, ready-to-apply and aerosol products for do-it-yourself users, and growth in emerging markets with rising housing demand.
The major growth factor is construction and renovation activity combined with design preference for tactile finishes, supported by water-based low-emission formulations.
By Technology, the Water-Based segment dominated the market 2025, owing to low-VOC regulation, easy cleanup and improved performance.
Asia Pacific dominated the market with a share of 53.00% in 2025, supported by large residential and commercial construction in China and India and strong decorative paint demand.
