
Organosilicon Polymers (Polysiloxane) Market Report Scope & Overview:
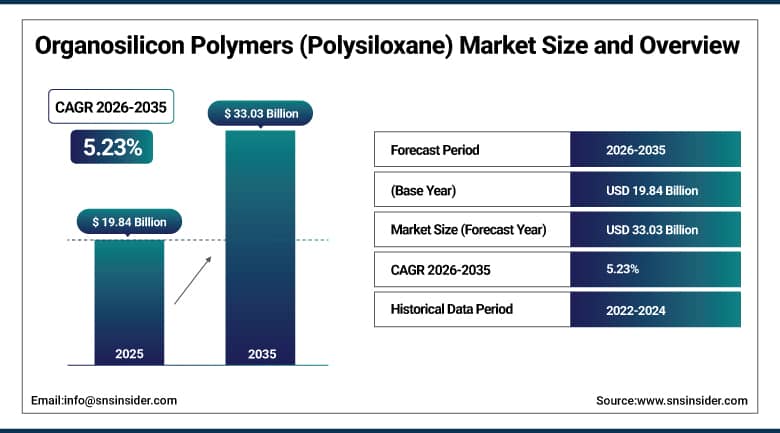
The Organosilicon Polymers (Polysiloxane) Market size was valued at USD 19.84 Billion in 2025 and is expected to reach USD 20.88 Billion in 2026, rising to USD 33.03 Billion by 2035. The market is forecast to expand at a CAGR of 5.23% during 2026–2035. Organosilicon polymers, known as polysiloxanes or silicones, are built on a backbone of alternating silicon and oxygen atoms with organic side groups, which gives them stability across wide temperature ranges, resistance to weather and chemicals, and flexibility. Growth is supported by vehicle electrification, electronics, renewable energy, construction and healthcare demand.
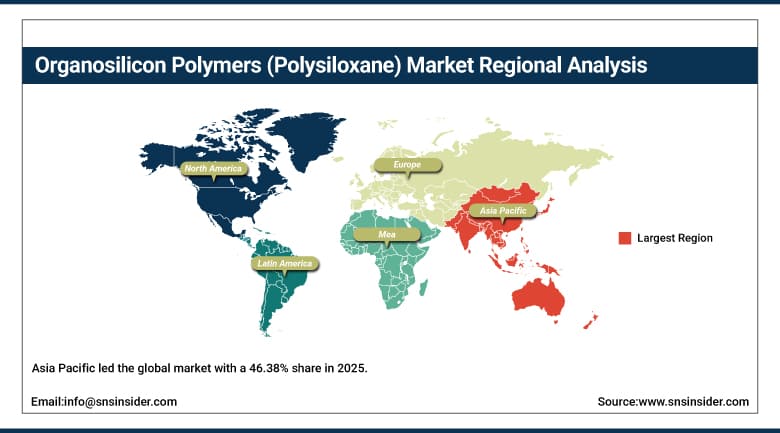
Asia Pacific accounted for the largest share of the market, at 46.38% in 2025, because China hosts the largest silicone production base and the region combines large electronics, construction and vehicle industries. Europe follows on the strength of specialty producers and premium industrial users, and North America is a significant market for high-value grades in aerospace, medical and electronics uses. Asia Pacific is also the fastest growing region as local demand scales up. Latin America and Middle East & Africa remain smaller markets that rely largely on imports. Producers and brand owners are also raising spending on lower-carbon and recycled grades.
To Get More Information On Organosilicon Polymers (Polysiloxane) Market - Request Free Sample Report
Key Report Takeaways:
-
By product type, silicone elastomers held 36.81% in 2025, while silicone gels are the fastest growing.
-
By application, adhesives and sealants held 32.47% in 2025, while electronics encapsulation and thermal management is the fastest growing.
-
By end use, building and construction held 28.76% in 2025, while healthcare and medical is the fastest growing.
-
By chemical structure, linear polysiloxanes held 62.18% in 2025, while crosslinked polysiloxanes are the fastest growing.
-
By region, Asia Pacific held 46.38% in 2025 and is also the fastest growing.
Market Trends and Insights:
Thermal management is becoming a core use as electric vehicle batteries, power electronics, data center hardware and fast chargers generate more heat in smaller spaces. Formulators are launching gap fillers, potting compounds and thermal interface materials with higher conductivity and lower bleed, and customers are qualifying them early in product design cycles.
Producers are working on recycled and bio-attributed silicones, chemical recycling of silicone scrap back to monomer and lower-carbon silicon metal supply. Brand owners in personal care, packaging and construction are asking for lower footprints, and suppliers are publishing carbon data for individual grades to win approvals.
Drivers Impact Analysis:
|
Driver |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Vehicle electrification and electronics growth |
+3.51% |
Global |
Short term (2 years or less) |
|
Construction and building efficiency demand |
+2.46% |
Asia Pacific and Europe |
Medium term (2 to 4 years) |
|
Renewable energy installations |
+1.92% |
Global |
Long term (4 years or more) |
|
Healthcare and personal care demand |
+1.37% |
Global |
Medium term (2 to 4 years) |
|
Performance advantages over organic polymers |
+0.88% |
Global |
Long term (4 years or more) |
Vehicle Electrification and Electronics Growth
Silicone gaskets, cable insulation, potting compounds, thermal pads and adhesives protect batteries, sensors, chargers and power electronics from heat, moisture and vibration. The International Energy Agency reported in its Global Electric Vehicle Outlook 2026 that electric car sales topped 20 million in 2025, up 20.00% from the previous year. Each electric vehicle uses far more silicone than a combustion car, and consumer devices, data centers and robotics add further demand. Chargers, inverters and battery packs also need thermal pads and gap fillers, which lifts silicone value per vehicle.
Construction and Building Efficiency Demand
Silicone sealants and coatings bond glass, seal facades, waterproof joints and withstand sunlight for decades, which makes them the preferred choice for curtain walls, insulating glass units and weatherproofing. Energy efficiency codes require airtight building envelopes, and renovation programs in Europe and Asia add steady volume. Contractors value long service life and low maintenance, and architects specify silicone systems for large projects. Prefabricated facade systems, structural glazing and insulating glass units use large volumes of silicone, and warranty periods of twenty years or more keep specifications tied to proven suppliers.
Renewable Energy Installations
Solar modules use silicone encapsulants, adhesives and junction box potting, wind turbines use silicone coatings and cable insulation, and grid equipment uses silicone rubber insulators that resist pollution and tracking. Expansion of utility-scale solar and wind capacity in China, India, Europe and the United States lifts volumes, and long outdoor lifetimes mean buyers focus on reliability rather than the lowest price. Floating solar, rooftop systems and offshore wind farms are expanding into harsher environments, which raises the need for materials that resist salt, humidity and ultraviolet exposure over decades of service.
Healthcare and Personal Care Demand
Medical grade silicones are used in tubing, catheters, implants, wound care, drug delivery devices and seals because they are biocompatible, soft and sterilizable. Cosmetics and personal care formulators use silicone fluids and emulsions for smooth feel, spreadability and water resistance in skin care, hair care and sun protection. Aging populations and rising incomes in emerging markets support steady growth. Hospitals and device makers prefer suppliers with documented biocompatibility testing and clean manufacturing, and these requirements create long qualification cycles that favor established producers with medical grade lines.
Performance Advantages Over Organic Polymers
Polysiloxanes stay flexible from very low to very high temperatures, resist ultraviolet light, ozone and moisture, and offer excellent electrical insulation, so they outperform most organic rubbers and sealants in demanding settings. Their low surface energy supports release coatings, defoamers and water repellents. Engineers keep finding new uses where reliability matters more than material cost, which supports premium pricing. Hybrid and branched structures extend silicone benefits into coatings, additive manufacturing and wearables, and each new application widens the customer base without displacing existing uses.
Restraints Impact Analysis:
|
Restraint |
(~) Percentage Point Impact on Market CAGR |
Geographic Relevance |
Impact Timeline |
|---|---|---|---|
|
Regulatory pressure on cyclic siloxanes |
-2.19% |
Europe and North America |
Short term (2 years or less) |
|
Overcapacity and price volatility |
-1.73% |
Asia Pacific |
Medium term (2 to 4 years) |
|
Energy and raw material cost exposure |
-1.05% |
Global |
Long term (4 years or more) |
|
Competition from organic polymers |
-0.69% |
Global |
Medium term (2 to 4 years) |
Regulatory Pressure on Cyclic Siloxanes
The European Commission adopted a restriction on the cyclic siloxanes D4, D5 and D6 on 16 May 2024, limiting each substance to 0.10% by weight in mixtures, with the general restriction applying after 6 June 2026. Producers must reformulate products, test residual levels and manage inventories of intermediates. Similar scrutiny in other regions raises compliance costs and pushes personal care and cleaning formulators to look for alternatives. Personal care and cleaning formulators are the most exposed, and some are shifting to bio-based alternatives to protect their brands.
Overcapacity and Price Volatility
China holds more than half of global silicone capacity, and rapid expansion in earlier years created oversupply that pushed monomer and rubber prices down and squeezed margins across the industry. Producers have responded with production discipline and price coordination, yet swings in operating rates still move prices sharply. Western producers face competition from low-cost exports and have closed or consolidated some capacity. Buyers use the oversupply to negotiate lower prices, and weak margins limit funds available for research and new plants, so specialty investments are often delayed.
Energy and Raw Material Cost Exposure
Silicone production starts with silicon metal, made in electric arc furnaces that consume large amounts of power, and methanol or methyl chloride for the direct process. Energy price spikes, power rationing and carbon costs raise the cost of monomer, especially in Europe. Producers have limited ability to pass on sudden increases to customers under long contracts, and margins in commodity grades are particularly exposed. Carbon pricing schemes and grid charges add further cost, and plants located in regions with cheaper renewable power gain a lasting advantage.
Competition from Organic Polymers
Polyurethane, epoxy, acrylic and modified silane polymers compete with silicones in sealants, adhesives and coatings, and offer lower prices or easier paintability in some uses. Thermoplastic elastomers are replacing silicone rubber in selected consumer and automotive parts because they are simple to mold and recycle. Silicone makers respond with application support and new hybrid products, but price comparisons remain a constraint in cost-driven segments. Contractors and appliance makers often test lower-cost hybrids first, and silicone must prove a clear lifetime benefit to justify its higher price.
Organosilicon Polymers (Polysiloxane) Market Segment Analysis:
By Product Type, Silicone Elastomers Dominate Organosilicon Polymers (Polysiloxane) Market; Silicone Gels to Register Fastest Growth.
Silicone elastomers, including high consistency rubber, liquid silicone rubber and room temperature vulcanizing systems, account for 36.81% of the market in 2025. They are used in seals, gaskets, cable insulation, medical tubing, baby products and kitchenware because they keep elasticity across wide temperature ranges and resist aging, and their breadth of grades supports demand in many industries. Liquid silicone rubber is growing fastest within this group because injection molding allows automated production of precise parts for medical and electronics uses.
Silicone gels are projected to grow at a CAGR of 6.84% during 2026–2035. Soft and self-healing gels protect electronics, cushion wearable devices, support wound care and serve as optical bonding materials in displays. Rising electronics content and growth of medical devices lift demand, and formulators offer gels with tailored hardness and tack. Manufacturers of wearables, displays and sensors choose gels because they absorb shock and keep stable electrical properties, and suppliers are launching optically clear and thermally conductive versions.
By Application, Adhesives and Sealants Dominate Organosilicon Polymers (Polysiloxane) Market; Electronics Encapsulation and Thermal Management to Register Fastest Growth.
Adhesives and sealants account for 32.47% of the market in 2025 because silicone products bond and seal glass, metals, plastics and ceramics in buildings, vehicles and appliances. They cure at room temperature, tolerate movement and last for decades outdoors, which makes them the standard in glazing and weatherproofing, and large construction programs keep volumes high. Major projects in healthcare, data centers and transport hubs specify silicone sealants for movement joints, and manufacturers qualify products to international building standards.
Electronics encapsulation and thermal management is expected to expand at a CAGR of 7.28% during 2026–2035. Batteries, chargers, sensors, server hardware and displays need potting, conformal coating and thermal pads that handle heat and vibration. Suppliers are launching grades with higher thermal conductivity and flame retardancy for use in electric vehicles and data centers. Structural glazing and weatherproofing sealants are a related outlet, and solar module assembly adds demand as manufacturers choose silicone for edge sealing and junction boxes.
By End Use, Building and Construction Dominates Organosilicon Polymers (Polysiloxane) Market; Healthcare and Medical to Register Fastest Growth.
Building and construction holds a 28.76% share in 2025 because facades, windows, roofing, joints and waterproofing rely on silicone sealants, coatings and water repellents. Energy codes demand airtight envelopes, and urbanization in Asia and renovation in Europe and North America keep consumption high, while contractors prefer products with proven long-term performance. Hospitals, device makers and diagnostics firms require suppliers with documented testing, clean manufacturing and traceable batches, which favors established producers with dedicated medical grade lines and regulatory support teams.
Healthcare and medical is projected to grow at a CAGR of 6.58% during 2026–2035. Silicones are used in tubing, implants, wound dressings, drug delivery devices, seals and surgical tools because they are biocompatible and withstand sterilization. Aging populations, expanding health systems in emerging markets and new wearable devices lift demand for medical grades. Elastomers, resins and cured adhesives all depend on crosslink density, and formulators adjust it to balance hardness against flexibility for each customer and use case.
By Chemical Structure, Linear Polysiloxanes Dominate Organosilicon Polymers (Polysiloxane) Market; Crosslinked Polysiloxanes to Register Fastest Growth.
Linear polysiloxanes account for 62.18% of the market in 2025 because dimethyl fluids, oils and the base polymers of sealants and rubbers are linear chains of varying length. They serve as lubricants, defoamers, release agents, personal care ingredients and intermediates, and large production volumes make them the foundation of most downstream silicone products. Producers sell these fluids by viscosity, and large buyers in personal care, textiles and industrial processing rely on annual contracts that keep volumes steady across cycles.
Crosslinked polysiloxanes are forecast to register a CAGR of 6.02% during 2026–2035. Networks formed by resins, gels and cured elastomers offer greater hardness, heat resistance and mechanical strength. Demand is rising in electronics, aerospace, coatings and additive manufacturing, where designers want durable parts and protective layers that keep their form under stress. Additive manufacturing resins, optical encapsulants and aerospace coatings add to this growth, and developers are testing hybrid networks that combine silicone flexibility with the strength of organic polymers.
Geography Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
86.37% |
|
Europe |
Germany |
31.26% |
|
Asia Pacific |
China |
62.48% |
|
Middle East & Africa |
Saudi Arabia |
24.18% |
|
Latin America |
Brazil |
44.73% |
Asia Pacific Organosilicon Polymers (Polysiloxane) Market
Asia Pacific led the global market with a 46.38% share in 2025 and is also the fastest growing region, with a projected CAGR of 6.12% over 2026–2035. China is the largest country, supported by the largest silicone production base, a deep electronics supply chain and heavy construction activity. Japan adds specialty producers and advanced users. Electronics clusters in Shenzhen, Suzhou and Dongguan, solar module plants in Jiangsu and construction across inland provinces create broad demand, and local producers supply competitive monomer and rubber.
South Korea, India, Taiwan and Southeast Asia are expanding electronics, vehicle and solar manufacturing, which pulls in sealants, elastomers and thermal materials. Regional producers are investing in downstream capacity and specialty grades to move beyond commodity monomer and compete on technical service. Government programs for solar, electric vehicles and advanced manufacturing encourage investment, and several producers are adding specialty lines for electronics and medical use. Local brand owners are asking for lower-carbon and recycled content, and regional standards bodies are tightening rules on volatile siloxanes.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Europe Organosilicon Polymers (Polysiloxane) Market
Europe accounted for 22.64% of the market in 2025, with Germany as the leading country. The region is home to leading specialty producers, premium automakers and medical device makers, and strict rules on chemicals and energy efficiency shape demand. Close ties between suppliers and customers speed up product approvals. Automotive clusters in Bavaria and Baden-Wurttemberg buy elastomers and sealants in large volumes, and chemical parks in Burghausen, Leverkusen and Ludwigshafen anchor production, research and logistics. Medical technology firms add demand for implant and tubing grades.
France, the United Kingdom, Italy and the Nordic countries host producers, compounders and construction users, while Central Europe attracts new specialty plants. High energy costs and chemicals rules are pushing capacity rationalization, and producers focus on high-value grades and recycling initiatives. Building renovation programs under the European Green Deal drive demand for sealants and coatings that improve airtightness, and wind farms in the North Sea region use silicone coatings and cable insulation. Producers are investing in renewable power and carbon reporting to hold customers.
North America Organosilicon Polymers (Polysiloxane) Market
North America held 21.17% of the market in 2025, led by the United States. The U.S. market was valued at USD 3.63 Billion in 2025 and is expected to register a CAGR of 4.87% during 2026–2035. Aerospace, medical, electronics, construction and personal care demand drive consumption of high-value grades. Gulf Coast chemical sites supply intermediates and specialty polymers, while Michigan, Ohio and the Carolinas host formulators serving vehicle, appliance and construction customers. Hospital systems and device makers buy medical grades in large volumes.
Canada adds demand through construction and energy uses, and Mexico is a major vehicle and appliance assembly base. Semiconductor and battery investment programs support local demand for thermal and encapsulation materials, and producers operate large integrated sites along the Gulf Coast and in the Midwest. Spending on data centers, battery plants and grid upgrades is lifting demand for encapsulants and thermal materials. Home improvement chains, industrial distributors and contractor networks supply sealants and coatings widely, and large producers operate technical centers that support specifiers on major building projects.
Latin America Organosilicon Polymers (Polysiloxane) Market
Latin America held 4.69% of the market in 2025. Brazil leads, supported by construction, vehicle assembly, personal care and a large industrial base, and it imports most of its silicone intermediates and specialty grades from Asia, Europe and North America. Mexico and Argentina follow, with growing appliance and automotive output. Sao Paulo and Minas Gerais host vehicle and appliance plants, and the construction sector buys sealants for housing and commercial projects. Local distributors stock imported grades and offer technical training to installers.
Brazil is also a large consumer of cosmetics and household products that use silicone fluids and emulsions, and distributors supply sealants to the construction trade. Currency swings and import duties affect pricing, and a few global producers have local plants or formulation sites. Investment in solar and wind capacity in Chile, Brazil and Mexico adds demand for encapsulants, coatings and cable insulation. Regional converters in Argentina and Colombia produce molded parts and sealants for local customers, although volumes are limited by the size of the market.
Middle East & Africa Organosilicon Polymers (Polysiloxane) Market
Middle East & Africa held 5.12% of the market in 2025. Saudi Arabia, the United Arab Emirates and Turkey lead regional demand through large construction programs, glazing, power infrastructure and growing industrial diversification. Imported grades supply most demand through distributors. Mega projects in Saudi Arabia, the United Arab Emirates and Qatar use large quantities of structural glazing sealants and waterproofing, and power utilities adopt silicone insulators and coatings for polluted coastal and desert sites. Demand is concentrated in a handful of large cities.
Solar projects in the Gulf use silicone encapsulants and cable insulation, and South Africa and Egypt add construction and automotive demand. Hot climates favor weather-resistant sealants and coatings, and distributors are widening technical support to serve contractors across the region. Distributors based in Dubai serve contractors across the Gulf, East Africa and South Asia. Turkey is a large consumer of construction chemicals and has a growing automotive and appliance sector, while Egypt and Morocco are developing automotive, cable and solar manufacturing.
Competitive Landscape:
The Organosilicon Polymers (Polysiloxane) Market is moderately concentrated. A handful of global producers control much of the monomer and specialty output, while Chinese groups and regional formulators compete in commodity grades and downstream products. Competition centers on monomer integration, cost position, grade breadth, customer approvals and technical service.
Companies pursue portfolio reshaping, specialty capacity close to customers, lower-carbon and recycled products and new formulations for electronics and healthcare. Investments in regional compounding and application laboratories are also strengthening local supply.
Organosilicon Polymers (Polysiloxane) Market Industry Leaders:
1. Dow: U.S. materials group and a leading global silicone producer with a broad range of downstream products.
2. Wacker Chemie: German chemical company with a large silicone business and specialty products.
3. Shin-Etsu Chemical: Japanese chemical group and a major producer of silicone fluids, rubber and resins.
4. Momentive Performance Materials: U.S. specialty silicones and quartz supplier.
5. Bluestar: Chinese chemical group and one of the largest silicone producers in Asia.
Companies Covered in this Report:
-
Dow
-
Wacker Chemie
-
Shin-Etsu Chemical
-
Momentive Performance Materials
-
Bluestar
-
Elkem
-
Evonik
-
KCC Corporation
-
Hubei Xingfa Chemicals Group
-
Gelest
Recent Industry Developments:
-
February 2026: Elkem announced an agreement to sell a majority of its Silicones division to Bluestar Elkem International in a transaction valued at about NOK 9.77 Billion, with Elkem retaining its Roussillon, Yongdeng and Chakan silicones plants.
-
June 2026: Wacker started the first production line at its new specialty silicones plant in Karlovy Vary, Czechia, which will supply custom silicones for automotive, home appliance, medical technology and energy customers.
-
Dow has said it will gradually close its 145,000-tonne per year dimethyl siloxane plant in the United Kingdom, with full withdrawal expected by the end of 2027.
Scope and Research Methodology
This study estimates the Organosilicon Polymers (Polysiloxane) Market for 2025 as the base year and forecasts it through 2035. The scope covers silicone elastomers, fluids and oils, resins, gels and emulsions supplied to formulators, converters and end users. Values are reported in USD at the point of sale by producers. Silicon metal, chlorosilane and silane monomers sold as merchant chemicals, and organic polymers, are outside the scope. Segmentation covers product type, application, end use and chemical structure, and regional analysis covers five regions and major countries. Revenue is recorded in the year of sale, and intermediate transfers between affiliated plants are excluded to avoid double counting.
Secondary research included company annual reports, investor presentations and filings, trade association and customs databases, patent filings, regulatory documents, and peer-reviewed and industry publications. Primary research consisted of structured interviews with executives, technical managers, procurement teams and application engineers across the value chain. These inputs were used to validate prices, capacity utilization and the share of each product type and application. Expert interviews were also used to test assumptions on monomer and rubber prices, operating rates, qualification timelines and the pace of adoption in electronics. Responses were compared across regions to identify gaps between announced and actual capacity.
Market size was built from the bottom up using production volumes, consumption per end use and price by product type, and was cross-checked from the top down against producer revenues and trade flows. Triangulation across these views fixed the base year value. Forecasts consider construction, vehicle and electronics output, energy and raw material costs, regulation and macroeconomic conditions, and segment and regional shares were assigned from usage patterns in each setting. An analyst quality review checked consistency before release. Sensitivity tests on energy prices and construction and vehicle output were run, and announced projects were risk-weighted by funding status and construction stage before being included. Interview findings were checked against shipment data wherever available.
Organosilicon Polymers (Polysiloxane) Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 19.84 Billion |
| Market Size by 2035 | USD 33.03 Billion |
| CAGR | CAGR of 5.23% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Silicone Elastomers, Silicone Fluids and Oils, Silicone Resins, Silicone Gels, and Silicone Emulsions) • By Application (Adhesives and Sealants, Coatings, Foams and Defoamers, Electronics Encapsulation and Thermal Management, Textile and Leather Treatment, and Others) • By End Use (Building and Construction, Transportation, Electronics and Electrical, Healthcare and Medical, Personal Care and Consumer Goods, and Industrial Processes) • By Chemical Structure (Linear Polysiloxanes and Crosslinked Polysiloxanes) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Dow, Wacker Chemie, Shin-Etsu Chemical, Momentive Performance Materials, Bluestar, Elkem, Evonik, KCC Corporation, Hubei Xingfa Chemicals Group, Gelest |

Frequently Asked Questions
The market was valued at USD 19.84 Billion in 2025 and is projected to reach USD 33.03 Billion by 2035, at a CAGR of 5.23%.
Asia Pacific leads, with a 46.38% share in 2025, supported by the largest silicone production base and large electronics, construction and vehicle industries.
Asia Pacific is also expected to grow fastest, at a CAGR of 6.12% during 2026–2035, led by China, India and Southeast Asia.
Silicone elastomers, adhesives and sealants, building and construction and linear polysiloxanes lead, while silicone gels, electronics encapsulation, healthcare and medical and crosslinked polysiloxanes grow fastest.
Dow, Wacker Chemie, Shin-Etsu Chemical, Momentive and Bluestar lead, along with Elkem, Evonik, KCC Corporation, Hubei Xingfa Chemicals Group and Gelest.
Rules on cyclic siloxanes, overcapacity, energy and raw material costs and competition from organic polymers restrain faster growth.
