
Vegan Food Market Report Scope & Overview:
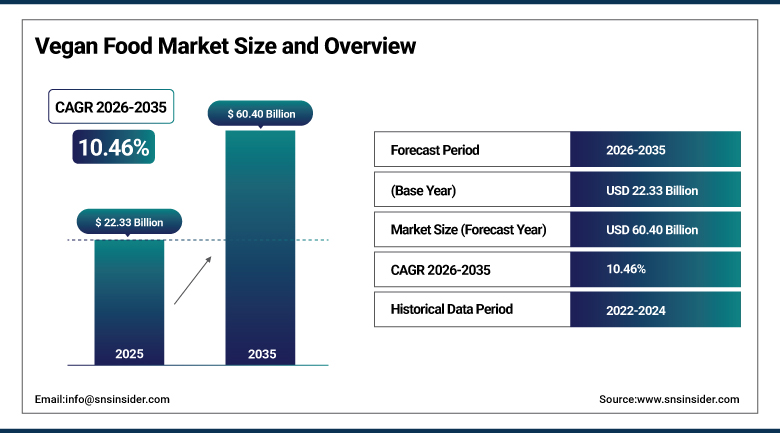
The Vegan Food Market was valued at USD 22.33 Billion in 2025 and is expected to reach USD 60.40 Billion by 2035, growing at a CAGR of 10.46% from 2026 to 2035.
A vegan burger patty sitting next to a beef patty in a grocery freezer case would have seemed like a novelty a decade ago, today it's close to a category expectation. What started as a niche catering mostly to committed vegans has broadened considerably, pulled forward by flexitarians experimenting with plant-based meals a few times a week, lactose-intolerant shoppers reaching for oat or almond milk out of necessity rather than ideology, and health-conscious consumers simply trying to eat less processed animal protein. India illustrates just how far this shift has traveled outside its Western origins, with roughly 22% of the population identifying as vegetarian and 19% as vegan, giving the country a genuinely distinct market dynamic compared to Europe or North America.
In the spring of 2025, Impossible Foods Inc. introduced Steak Bites, which was the first steak replacement product in the US market with pre-seasoned and pre-cooked small pieces that have 21 grams of plant-based protein per serving.
To Get more information Vegan Food Market - Request Free Sample Report
Vegan Food Market Trends
-
Oat-based dairy alternatives continue gaining share over soy and almond as consumer taste preferences shift.
-
Plant-based egg alternatives are expanding rapidly as fermentation and protein science improve texture and cooking performance.
-
Online distribution is growing faster than traditional retail as direct-to-consumer vegan brands scale subscription models.
-
Foodservice and quick-service restaurant partnerships are broadening vegan product trial beyond dedicated plant-based shoppers.
-
Clean-label reformulation is pushing vegan meat and dairy brands toward shorter, more recognizable ingredient lists.
U.S. Vegan Food Market Outlook
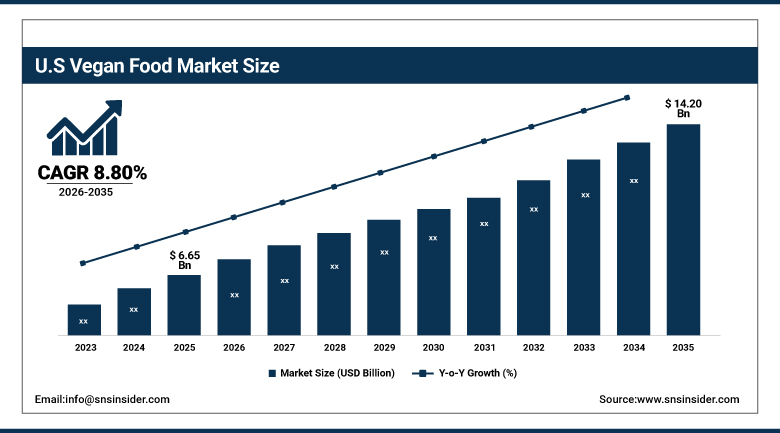
The U.S. Vegan Food Market was valued at USD 6.65 Billion in 2025 and is projected to reach USD 14.20 Billion by 2035, growing at a CAGR of 8.80% during 2026-2035.
Lactose intolerance prevalence and rising adoption of vegan diets continue anchoring domestic demand, supported by a well-established plant-based retail infrastructure that now extends well beyond dedicated natural food stores into mainstream grocery chains. Meat substitute brands have driven much of the category's public visibility, though dairy alternatives, oat and almond milk in particular, generate steadier, higher-volume repeat purchasing than the more experimental meat alternative segment. Foodservice partnerships between plant-based brands and quick-service restaurant chains continue expanding trial among consumers who wouldn't necessarily buy vegan products at retail but are willing to try them in a familiar restaurant format. Consumer skepticism toward heavily processed plant-based meat has pushed several major brands toward cleaner, shorter ingredient lists in response to changing purchasing sentiment.
In 2025, Beyond Meat, Inc. introduced Beyond Ground, a new plant-based ground meat innovation, following months of consumer anticipation after the company first teased the product over the summer.
Vegan Food Market Segment Analysis
-
By Product Type, Meat Substitutes segment dominated the Vegan Food Market in 2025 with 36.90% share; Egg Alternatives segment is the fastest-growing segment, registering a CAGR of 12.60% from 2026 to 2035.
-
By Distribution Channel, Offline segment dominated the market in 2025 with 83.50% share; Online segment is the fastest-growing segment, registering a CAGR of 13.40% from 2026 to 2035.
-
By Source, Soy segment dominated the market in 2025 with 32% share; Oats segment is the fastest-growing segment, registering a CAGR of 13.80% from 2026 to 2035.
-
By Form, Frozen segment dominated the market in 2025 with 38% share; Chilled segment is the fastest-growing segment, registering a CAGR of 12.20% from 2026 to 2035.
By Product Type, Meat Substitutes Lead the Vegan Food Market While Egg Alternatives Gain Ground Fastest
Meat Substitutes hold 36.90% of the Vegan Food Market, the largest single product category, benefiting from the sheer marketing visibility and retail shelf space that brands like Beyond Meat and Impossible Foods have built over the past decade. Continued product innovation, from ground meat formats to steak and poultry alternatives, keeps expanding the category's appeal beyond its original burger-and-sausage foundation into a genuinely broader range of everyday meal occasions.
Egg Alternatives represent the highest growth rate category of 12.60% CAGR, the fastest of all categories, due to advancements in fermentation and protein technologies making plant-based egg alternatives more similar in terms of texture and performance compared to regular eggs. Increasing use by foodservice businesses, especially in breakfast and brunch items, have been responsible for Egg Alternative segment's fast growth, because plant-based egg alternatives work well enough for commercial kitchen environment.
By Distribution Channel, Offline Dominates While Online Emerges as the Fastest-Growing Channel
The share of offline distribution is 83.50%, which shows how many purchases of vegan food products happen through traditional means via physical grocery stores, where people can examine, compare, and buy the products along with their usual purchases. Mainstream grocery chains expanding dedicated plant-based sections, rather than relegating vegan products to a small specialty aisle, have reinforced this channel's continued dominance even as the category has grown considerably.
Online is growing fastest among distribution channels, at a 13.40% CAGR, as direct-to-consumer vegan brands increasingly build subscription and repeat-purchase models that don't depend on securing retail shelf space in the first place. Newer, smaller vegan brands without the negotiating leverage to win prominent grocery placement have used online channels as their primary path to market, accelerating this channel's growth well beyond its historical share of overall vegan food sales.
By Source, Soy Dominates While Oats Register the Fastest Growth
Soy accounts for 32% of the market by source, the largest single category, reflecting its long history as the original plant-based protein base for both meat and dairy alternatives, along with its relatively low production cost and complete amino acid profile. Established soy processing infrastructure across the food industry also keeps this source the most economical choice for manufacturers scaling production.
Oats are growing fastest by source, at a 13.80% CAGR, as oat milk's mild flavor and creamy texture continue winning over consumers who found soy or almond alternatives less appealing in coffee and everyday drinking applications. Growing oat cultivation and processing investment, including sourcing initiatives tied to regional farming partnerships, is reinforcing supply reliability as demand for oat-based products keeps climbing faster than the broader dairy alternative category.
By Form, Frozen Dominates While Chilled Registers the Fastest Growth
Frozen holds 38% of the market by form, remaining the standard choice for meat substitutes and prepared vegan meals in particular, since freezing extends shelf life considerably and simplifies distribution logistics for products that would otherwise spoil quickly. Established frozen food retail infrastructure across grocery chains has also made this format easier for vegan brands to access than newer distribution formats might allow.
Chilled is growing fastest, at a 12.20% CAGR, as consumer perception increasingly associates refrigerated positioning with freshness and premium quality compared to frozen alternatives, particularly for dairy alternatives and ready-to-eat vegan meals. Growing refrigerated retail space allocation for plant-based products has reinforced this shift, as grocery chains respond to consumer preference for chilled positioning over frozen for everyday purchase occasions.
Regional Insights
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.60% |
|
Asia Pacific |
India |
32.40% |
|
Europe |
Germany |
25.80% |
|
Middle East & Africa |
UAE |
17.20% |
|
Latin America |
Brazil |
26.70% |
North America Vegan Food Market Insights
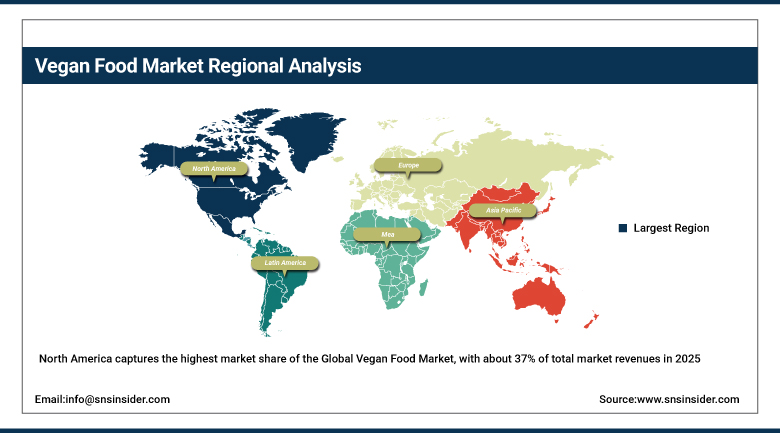
North America captures the highest market share of the Global Vegan Food Market, with about 37% of total market revenues in 2025, attributed to the increasing popularity of veganism, relatively high levels of lactose intolerance, and a well-developed retail and food services network of plant-based foods. Continuous innovation and expansion of food service collaborations in the region are continually driving more trials among flexitarians than the core vegan customers.
About 85.60% of the North American market is captured by the United States due to the presence of numerous plant-based food manufacturers and the developed distribution network of retail and food services outlets. The Canadian market also has a smaller but stable contribution.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Vegan Food Market Insights
Asia Pacific is growing faster than any other region in this market, expanding at an 11.52% CAGR, driven by deep-rooted vegetarian and vegan dietary traditions in markets like India alongside rapidly expanding modern retail infrastructure across the region. Rising disposable incomes and growing health awareness continue expanding demand for packaged plant-based products in markets where vegetarian eating has historically relied on unbranded, home-prepared food rather than commercial products.
India holds roughly 32.40% of the regional market, supported by its uniquely large vegetarian and vegan population base and rapidly expanding organized retail sector. The Chinese and Southeast Asian markets are experiencing rapid growth as the availability of plant-based products increases outside large metropolitan areas, while the Japanese and Korean markets contribute because of their health conscious consumers.
Europe Vegan Food Market Insights
Europe's vegan food market is mature and steady, shaped by strong sustainability-driven consumer awareness and comprehensive food labeling regulation that has made plant-based product claims relatively transparent and trusted across the region. Growing trendiness of veganism, reinforced by high-profile product launches from popular mainstream brands, continues supporting steady category expansion even as growth in absolute terms remains more measured than in Asia Pacific.
Germany leads the European market with a 25.80% share, supported by its large plant-based food manufacturing base and strong consumer sustainability awareness. France and the United Kingdom follow, with demand in both countries tied to established vegan retail infrastructure and growing flexitarian consumer adoption.
Middle East & Africa and Latin America Vegan Food Market Insights
The Middle East & Africa market is growing consistently on account of development in retail infrastructure across the countries in the Gulf region with higher health consciousness and increasing availability of plant-based products from both imports and local manufacturers. The Latin American market is growing on the same lines owing to growth in plant-based food manufacturing in Brazil and increased interest among urban consumers for vegan and vegetarian diets.
UAE is the leading country in the Middle East & Africa market at 17.20% share on account of its position as a distribution center for imported plant-based products in the region. Brazil contributes 26.70% to the Latin American market with its food manufacturing base, while Mexico is contributing in terms of availability of plant-based products.
Growth Drivers: Flexitarian Adoption and Health Consciousness Fueling Market Growth
Rising flexitarian adoption is the clearest driver behind this market's growth, as consumers who have no intention of fully eliminating animal products still incorporate plant-based meals into their regular rotation for health, environmental, or simple variety reasons. Growing health consciousness, reinforced by public health messaging around reducing processed animal protein and saturated fat consumption, continues expanding the addressable market well beyond the category's traditional vegan and vegetarian core.
Environmental concern is reinforcing these health-driven purchasing decisions, as consumers increasingly factor in the comparatively lower environmental footprint of plant-based food production when choosing between animal and plant protein sources.
Restraints: Consumer Skepticism and Price Premiums Limiting Market Expansion
The rising levels of consumer doubt regarding the heavily processed nature of some vegan meat offerings is having an impact on the category, as those who prioritize cleaner labels begin to have second thoughts regarding the lengthy ingredient lists present in what are advertised as healthier meat alternatives. Some vegan items do command a price premium compared to traditional options, and that can make it hard to rationalize the additional cost, especially in economically challenging times.
This awareness is adding to these health-related buying decisions, since consumers take into account the environmentally friendlier nature of producing plant foods than animal foods while making their choices.
Opportunities: Foodservice Expansion and Fermentation Technology Creating New Growth Avenues
Food service collaborations present one major growth opportunity for brands as more quick service and casual dining restaurants incorporate more plant-based menu offerings, introducing vegan products to individuals who might never buy them at retail locations. Food service collaborations can bring great potential in terms of brand awareness and trials that would be hard to achieve through retail alone.
Fermentation technologies present another opportunity, especially when it comes to dairy and eggs as the advancements in fermentation techniques allow for more consistent texture, better taste, and improved culinary performance compared to conventional animal products.
Recent Developments
-
2025: Oatly Group AB announced that eight of its barista oat milk products are now made from 100% British-grown oats, aiming to lower its climate footprint by 7 to 13% by 2026.
-
2025-2026: Danone S.A. agreed to acquire vegan meal replacement brand Huel for approximately EUR 1 billion, marking its second plant-based nutrition acquisition in months following its earlier purchase of Kate Farms.
-
May 2025: Beyond Meat, Inc. pulled its full-year sales forecast after first-quarter revenue fell 9%, while securing USD 100 million in debt financing from the Ahimsa Foundation to strengthen liquidity.
-
2025: Impossible Foods Inc. expanded its foodservice presence through pop-up restaurant activations, including a Chicago location featuring its plant-based meat alternatives alongside Oatly soft serve desserts.
Vegan Food Companies are:
-
Beyond Meat, Inc.
-
Danone S.A.
-
Amy's Kitchen, Inc.
-
Daiya Foods Inc.
-
Earth's Own Food Company Inc.
-
Archer Daniels Midland Company
-
Cargill, Incorporated
-
Kraft Heinz Company
-
NIPPN Corporation
-
Eden Foods, Inc.
-
SunOpta Inc.
-
Impossible Foods Inc.
-
Oatly Group AB
-
Upfield B.V.
-
Bunge Global SA
-
Nestlé S.A.
-
Unilever PLC
-
Maple Leaf Foods Inc.
Vegan Food Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 22.33 Billion |
| Market Size by 2035 | USD 60.40 Billion |
| CAGR | CAGR of 10.46% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Meat Substitutes, Dairy Alternatives, Egg Alternatives, Vegan Bakery & Confectionery, Plant-Based Snacks) • By Distribution Channel (Offline, Online) • By Source (Soy, Wheat, Oats, Almond, Others) • By Form (Frozen, Chilled, Shelf-Stable) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Beyond Meat, Inc., Danone S.A., Amy's Kitchen, Inc., Daiya Foods Inc., Earth's Own Food Company Inc., Archer Daniels Midland Company, Conagra Brands, Inc., Cargill, Incorporated, Kraft Heinz Company, NIPPN Corporation, Eden Foods, Inc., SunOpta Inc., Impossible Foods Inc., Oatly Group AB, Tofutti Brands, Inc., Upfield B.V., Bunge Global SA, Nestlé S.A., Unilever PLC, Maple Leaf Foods Inc. |
Frequently Asked Questions
Key players include Beyond Meat, Inc., Danone S.A., Amy's Kitchen, Inc., Impossible Foods Inc., Oatly Group AB, Archer Daniels Midland Company, Conagra Brands, Inc., and Cargill, Incorporated, alongside other established plant-based food manufacturers.
Key opportunities include foodservice partnerships expanding trial among mainstream consumers, fermentation technology innovation improving dairy and egg alternative performance, and expanding online distribution for direct-to-consumer vegan brands.
The market is driven by rising flexitarian adoption, growing health consciousness, and increasing environmental concern among consumers choosing between animal and plant protein sources.
The Meat Substitutes segment dominated the Vegan Food Market in 2025.
The North America region dominated the Vegan Food Market in 2025, accounting for approximately 37% of global market share.
