
Modified Starch Market Report Scope & Overview:
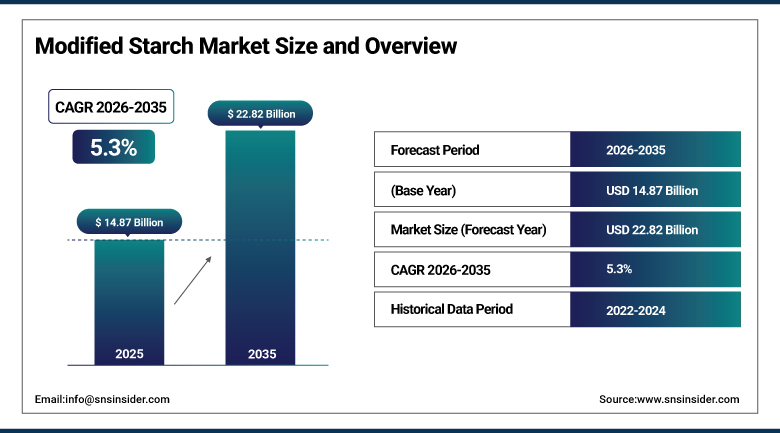
The Modified Starch Market was valued at USD 14.87 Billion in 2025 and is expected to reach USD 22.82 Billion by 2035, growing at a CAGR of 5.3% from 2026 to 2035.
Native starch does a decent job holding sauces together or thickening a soup, but it falls apart, sometimes literally, under the heat, freezing, and acid exposure that modern food processing puts it through. Modification, physical treatment, chemical bonding, or enzymatic conversion, fixes that, producing starches that stay stable through retort sterilization, freeze-thaw cycles, and low-pH formulations that would break down an untreated starch entirely. That functional upgrade has made modified starch close to indispensable across processed food, and increasingly in industrial applications like paper sizing, textile finishing, and biodegradable packaging where its performance-per-dollar is hard for synthetic alternatives to match. Corn remains the dominant feedstock by a wide margin, though cassava-based starches are gaining real traction for their exceptional paste clarity.
In June 2025, Ingredion Incorporated received regulatory clearance to acquire a 49% stake in AGRANA's AGFD Bandarei starch facility in Romania, forming a joint venture with a combined investment of approximately EUR 35 million to expand regional starch production capacity.
To Get more information Modified Starch Market - Request Free Sample Report
Modified Starch Market Trends
-
Cassava-based modified starches are gaining share for their superior paste clarity and stability in confectionery and beverage applications.
-
Enzymatically modified starches are expanding fastest as manufacturers seek clean-label alternatives to chemical modification.
-
Industrial applications, particularly paper sizing and biodegradable packaging, are growing faster than traditional food and beverage uses.
-
Pharmaceutical excipient demand is rising as modified starches find growing use as tablet disintegrants and binders.
-
Regional capacity expansion is accelerating as ingredient suppliers seek to secure feedstock closer to key demand centers.
U.S. Modified Starch Market Outlook
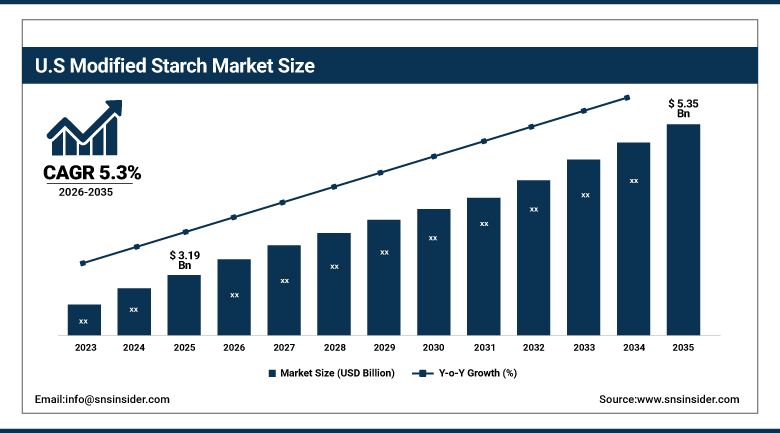
The U.S. Modified Starch Market was valued at USD 3.19 Billion in 2025 and is projected to reach USD 5.35 Billion by 2035, growing at a CAGR of 5.3% during 2026-2035.
Modified starch consumption in the production of processed and convenient foods remains at the core of domestic market dynamics, encompassing sauces, dairy products, snacks, and all kinds of foods in which the texture consistency through processing, transportation, and shelf storage plays an important role in quality assurance. Clean-label reformulation trends continue to influence choice of technologies used to obtain modifications, with physical and enzyme-based modification technologies gradually replacing chemical ones due to consumer attitudes towards ingredients used. A relatively small line of pharmaceutical applications is expected to remain steady, as modified starch is proven to be a good disintegrant and binding agent that pharmaceutical formulators have been using for decades. Increasing interest in biodegradable packaging solutions also generates additional demand among industries, as modified starch is increasingly used as a coating to replace PFAS and other synthetic barrier agents.
In March 2025, Cargill, Incorporated showcased a first-of-its-kind dent-corn modified starch for improving sauce color and texture, alongside a cost-effective pectin replacer for gummies and jellies, at the AAHAR trade show in India.
Modified Starch Market Segment Analysis
-
By Source, Corn segment dominated the Modified Starch Market in 2025 with 47.80% share; Cassava segment is the fastest-growing segment, registering a CAGR of 5.12% from 2026 to 2035.
-
By Application, Food & Beverage segment dominated the market in 2025 with 50.80% share; Industrial segment is the fastest-growing segment, registering a CAGR of 5.62% from 2026 to 2035.
-
By Modification Type, Physically Modified segment dominated the market in 2025 with 52.10% share; Enzymatically Modified segment is the fastest-growing segment, registering a CAGR of 5.62% from 2026 to 2035.
-
By Form, Dry segment dominated the market in 2025 with 65.62% share; Liquid segment is the fastest-growing segment, registering a CAGR of 5.29% from 2026 to 2035.
By Source, Corn Leads the Modified Starch Market While Cassava Gains Ground Fastest
Corn holds 47.80% of the Modified Starch Market, the largest single source category, benefiting from an extensive, well-established global supply chain of maize derivatives that few other starch sources can match in scale or cost efficiency. Decades of corn wet-milling infrastructure investment across major producing regions have made corn-derived starch the default feedstock for manufacturers scaling modified starch production, particularly for oxidized and cationic grades used in packaging and textile applications.
Cassava is growing at a 5.12% CAGR, the fastest pace among sources, propelled by its exceptional paste clarity and stability characteristics that make it particularly well suited to confectionery, beverage, and sauce applications where visual clarity matters to product appeal. Growing cassava cultivation and processing capacity across Southeast Asia and parts of Africa is also improving supply reliability for manufacturers looking to diversify away from corn-dependent supply chains.
By Application, Food & Beverage Dominates While Industrial Emerges as the Fastest-Growing Application
Food & Beverage accounts for 50.80% of application demand, the largest single category, reflecting how deeply modified starch is embedded in everyday processed food manufacturing, from sauces and dairy products to baked goods and instant noodles where texture stability through processing and storage genuinely affects product quality. Rising global consumption of convenience and ready-to-eat foods continues reinforcing this category's lead, since these products depend heavily on modified starch's functional properties to maintain texture and appearance.
Industrial applications are growing fastest, at a 5.62% CAGR, as modified starch increasingly serves as a functional ingredient in paper sizing, textile finishing, adhesives, and increasingly biodegradable packaging coatings that substitute for PFAS and other synthetic barrier chemicals. Growing regulatory pressure against synthetic per- and polyfluoroalkyl substances in food-contact packaging is accelerating adoption of starch-based coating alternatives across the paper and packaging industry.
By Modification Type, Physically Modified Dominates While Enzymatically Modified Registers the Fastest Growth
Physically Modified starches hold 52.10% of the market by modification type, the largest single category, benefiting from consumer and regulatory preference for modification methods that do not require chemical reagents, giving manufacturers a genuine clean-label positioning advantage. Pregelatinization and other heat or pressure-based physical modification techniques deliver meaningful functional improvements over native starch without the chemical additive labeling that some consumers actively avoid.
The Enzymatically Modified Starch category is witnessing rapid growth at a CAGR of 5.62%, due to rising preferences for the enzyme modification process, which not only ensures precise modifications but also keeps the clean-label image intact, an element that cannot be delivered through the use of chemical modification processes. The accuracy of this technique, which modifies particular structures of the starch chain and not chemicals, is paving the way for innovative formulations.
By Form, Dry Dominates While Liquid Registers the Fastest Growth
Dry form holds 65.62% of the market, remaining the standard choice largely because it offers superior shelf stability and simplifies long-distance ingredient trade, a genuine advantage for a global commodity ingredient that often travels significant distances from processing facilities to end manufacturers. Dry starch also integrates more easily into standard food manufacturing equipment and formulation processes than liquid alternatives require.
Liquid form is growing fastest, at a 5.29% CAGR, as certain industrial and pharmaceutical applications increasingly favor liquid starch for precision dosing and easier incorporation into continuous manufacturing processes that do not require a separate reconstitution step. Manufacturers running high-volume, automated production lines have been the primary adopters of liquid modified starch, since it eliminates a processing step that dry powder formats typically require.
Regional Insights
|
Region |
Country |
Share (2025) |
|
North America |
United States |
85.29% |
|
Asia Pacific |
China |
36.00% |
|
Europe |
Germany |
24.60% |
|
Middle East & Africa |
UAE |
17.20% |
|
Latin America |
Brazil |
25.29% |
North America Modified Starch Market Insights
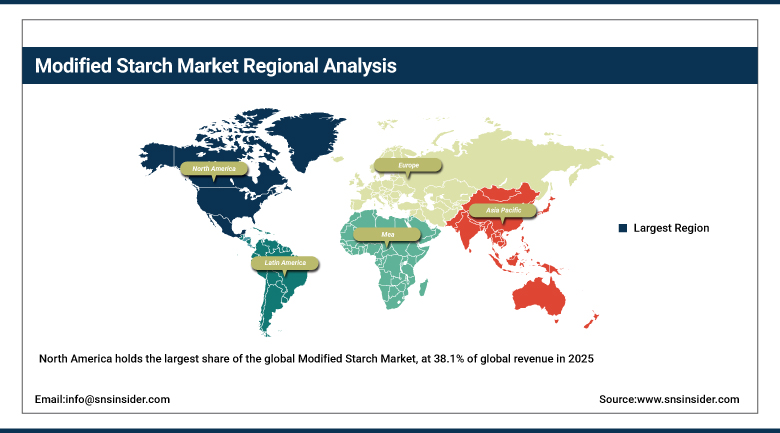
North America holds the largest share of the global Modified Starch Market, at 38.1% of global revenue in 2025, supported by a deeply established processed food manufacturing base and a rising demand for clean-label products that continues reshaping which modification methods manufacturers favor across the region. Growing pharmaceutical excipient demand and industrial applications like biodegradable packaging coatings are adding further momentum to a market that is otherwise mature and steady.
The United States accounts for approximately 85.29% of the North American market, reflecting its massive processed food manufacturing base and substantial corn wet-milling infrastructure. Canada contributes a smaller but steady share, tied to its own food processing industry and comparable regulatory standards around ingredient labeling.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Modified Starch Market Insights
Asia Pacific is showing faster growth than any other region in the market due to the fast pace of urbanization, increasing disposable income, and high consumption of convenience foods in the region. China and India, in particular, have registered strong growth in demand for such products as sauces, soups, and instant noodles, and these benefits from the use of modified starches convert directly into profits of packaged food producers.
China accounts for approximately 36.00% of regional market due to its large food processing industry, as well as corrugated packaging and textile sizing applications for oxidized and cationic starch grades. India is experiencing fast growth due to the development of its dairy, snacks, and instant mix product categories along with the pharmaceutical excipient use of pregelatinized and acetylated starches.
Europe Modified Starch Market Insights
Europe's modified starch market is mature and steady, shaped by strong food safety regulation and well-established processed food manufacturing traditions across the region. Confectionery, snack, and beverage concentrate applications remain key demand drivers, with growing interest in enzyme-modified and resistant starch solutions reflecting the region's clean-label consumer preferences.
Germany leads the European market with a 24.60% share, supported by its large food manufacturing base and advanced ingredient processing industry. France and the United Kingdom follow, with demand in both countries tied to established confectionery and processed food sectors.
Middle East & Africa and Latin America Modified Starch Market Insights
The Middle East & Africa segment continues to grow as consumption of packed food products increases in the Gulf countries due to the development of food import substitution initiatives and modern retail presence. The same trend is witnessed in the Latin America segment as growth in the segment results from the growth in food processing capacity in Brazil and regional demand for convenient foods.
The UAE has a market share of 17.20% within the Middle East & Africa segment since it functions as a regional food production and distribution center. In the case of Latin America, Brazil has a market share of 25.29%, which can be attributed to its food processing capacity.
Growth Drivers: Processed Food Demand and Industrial Application Expansion Fueling Market Growth
The increased global demand for ready-to-eat or convenience foods serves as the most visible reason behind the expansion of this market because an increased pace of life and urbanization in both advanced and developing countries is leading more customers to consume packaged foods where the properties of modified starch are highly valued.
Increased industrial uses of the product in the form of paper sizing, textile finishing, and biodegradable packaging coating serve as a significant second line of demand as companies look for functional and inexpensive substitutes to synthetic chemicals. The demand for pharmaceutical excipients also grows steadily, providing an additional basis for the market development as modified starch continues to be a trusted part of the formulation of drug tablets.
Restraints: Clean-Label Pressure on Chemical Modification and Feedstock Price Volatility Limiting Market Expansion
Clean-label consumer preferences are creating genuine headwinds for chemically modified starch variants specifically, as manufacturers increasingly reformulate toward physical or enzymatic modification methods that avoid the chemical additive labeling some consumers actively scrutinize. Feedstock price volatility, tied to broader agricultural commodity markets for corn, cassava, and other starch sources, can make it difficult for starch producers to hold pricing steady with food and industrial customers on long-term supply contracts.
Competition from alternative texturizing and stabilizing ingredients, including gums and other hydrocolloids, adds further competitive pressure in some food applications where formulators have multiple functional ingredient options to choose from.
Opportunities: Biodegradable Packaging and Pharmaceutical Excipient Expansion Creating New Growth Avenues
Biodegradable packaging coatings represent a significant growth opportunity, as starch-based barrier solutions increasingly serve as credible alternatives to PFAS and other synthetic chemicals facing tightening regulatory restrictions across food-contact packaging applications. Manufacturers who can develop starch-based coatings with genuinely competitive barrier performance stand to capture meaningful share in this expanding application.
Growing pharmaceutical and nutraceutical excipient demand offers a second clear opportunity, particularly as the dietary supplement industry continues expanding and formulators increasingly value modified starch's reliability as a functional tablet component.
Recent Developments
March 2025: Cargill, Incorporated showcased a first-of-its-kind dent-corn modified starch for improving sauce color and texture, alongside a cost-effective pectin replacer for gummies and jellies, at the AAHAR trade show in India.
June 2025: Ingredion Incorporated received regulatory clearance to acquire a 49% stake in AGRANA's AGFD Bandarei starch facility in Romania, forming a joint venture with a combined investment of approximately EUR 35 million to expand regional starch production capacity.
August 2024: Roquette Frères expanded its texturizing solutions portfolio with four new tapioca-based cook-up starches under its CLEARAM TR range, targeting food manufacturers' specific textural requirements.
2025: Cargill, Incorporated introduced a cold-swelling modified starch for dairy-based and plant-based yogurt formulations, improving texture and stability by 28% without requiring additional gums or stabilizers.
Modified Starch Companies are:
-
Ingredion Incorporated
-
Cargill, Incorporated
-
Roquette Frères
-
Tate & Lyle plc
-
Archer Daniels Midland Company
-
Emsland Group
-
Grain Processing Corporation
-
AGRANA Beteiligungs-AG
-
Südstärke GmbH
-
Sanstar Ltd.
-
Global Bio-chem Technology Group Company Limited
-
Universal Starch-Chem Allied Ltd.
-
Gujarat Ambuja Exports Limited
-
KMC (Kartoffelmelcentralen A.m.b.A.)
-
Meihua Holdings Group Co., Ltd.
-
Zhucheng Xingmao Corn Developing Co., Ltd.
-
China Essence Group Limited
-
Japan Corn Starch Co., Ltd.
Modified Starch Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 14.87 Billion |
| Market Size by 2035 | USD 22.82 Billion |
| CAGR | CAGR of 5.3% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Source (Corn, Wheat, Cassava, Potato) • By Application (Food & Beverage, Industrial, Pharmaceutical, Paper & Textile) • By Modification Type (Physically Modified, Chemically Modified, Enzymatically Modified) • By Form (Dry, Liquid) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Ingredion Incorporated, Cargill, Incorporated, Roquette Frères, Tate & Lyle plc, Archer Daniels Midland Company, Royal Avebe U.A., Emsland Group, Grain Processing Corporation, AGRANA Beteiligungs-AG, Südstärke GmbH, Sanstar Ltd., Global Bio-chem Technology Group Company Limited, Universal Starch-Chem Allied Ltd., Gujarat Ambuja Exports Limited, Manildra Group, KMC (Kartoffelmelcentralen A.m.b.A.), Meihua Holdings Group Co., Ltd., Zhucheng Xingmao Corn Developing Co., Ltd., China Essence Group Limited, Japan Corn Starch Co., Ltd. |

Frequently Asked Questions
Key players include Ingredion Incorporated, Cargill, Incorporated, Roquette Frères, Tate & Lyle plc, Archer Daniels Midland Company, Royal Avebe U.A., Emsland Group, and Grain Processing Corporation, alongside other established starch ingredient manufacturers.
Key opportunities include biodegradable packaging coatings as alternatives to PFAS and synthetic chemicals, growing pharmaceutical and nutraceutical excipient demand, and expanding regional production capacity closer to key demand centers.
The market is driven by rising global demand for processed and convenience food, expanding industrial applications in paper and packaging, and growing pharmaceutical excipient demand.
The Corn segment dominated the Modified Starch Market in 2025.
The North America region dominated the Modified Starch Market in 2025, accounting for approximately 38.1% of global market share.
