
Veterinary MRI Market Report Scope & Overview:
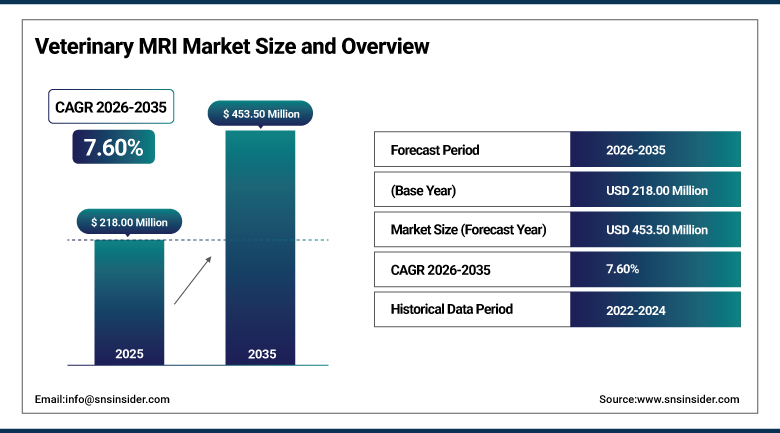
The Veterinary MRI Market was valued at USD 218.00 Million in 2025 and is expected to reach USD 453.50 Million by 2035, growing at a CAGR of 7.60% from 2026-2035.
The Veterinary MRI Market covers magnetic resonance imaging scanners, software, coils, services and consumables used to diagnose disease and injury in dogs, cats, horses and other animals. MRI gives detailed images of the brain, spine, joints and soft tissue, and is used in neurology, orthopedics, oncology and equine lameness work. Growth is supported by rising pet ownership and spending, growth of specialty and referral hospitals, and veterinary school investment, while high equipment cost, anesthesia needs, helium supply and shortages of trained technicians shape adoption.
⮞In February, 2026, OR Technology and Hallmarq Veterinary Imaging formed a new international group backed by a fund advised by NORD Holding, with more than 200 employees across Europe, the Middle East and Africa, and North America. Hallmarq contributes veterinary MRI and CT, while OR Technology adds digital X-ray, ultrasound and CT.
To Get more information Veterinary MRI Market - Request Free Sample Report
Veterinary MRI Market Trends
- Adoption of low-field and zero-helium magnets that lower installation and operating cost
- Use of artificial intelligence reconstruction to shorten scan times and anesthesia exposure
- Growth of imaging-as-a-service and leasing models for smaller hospitals
- Replacement of aging scanners at veterinary school teaching hospitals
- Consolidation of imaging suppliers into multimodality veterinary groups
- Expansion of equine and mobile MRI services for lameness diagnosis
U.S. Veterinary MRI Market Outlook
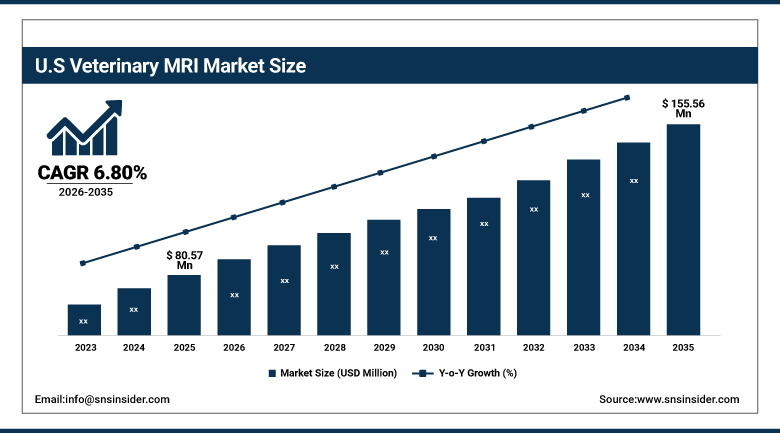
The U.S. Veterinary MRI Market was valued at USD 80.57 Million in 2025 and is expected to reach USD 155.56 Million by 2035, growing at a CAGR of 6.80% from 2026-2035.
The U.S. Veterinary MRI Market is the largest national market, supported by a large pet population, high spending on companion animal care, a network of specialty and emergency hospitals, and veterinary schools with teaching hospitals. Neurology, orthopedics and oncology drive scans in dogs and cats, while equine practices use MRI for lameness. Growth is moderated by scanner cost, anesthesia risk and the number of board-certified radiologists and technologists available.
⮞In May, 2026, the Louisiana State University School of Veterinary Medicine installed a new Canon Orian 1.5 Tesla MRI system for small and large animal patients, replacing its original scanner in service since 2009. The system's high-performance gradients are intended to shorten scan times and improve image resolution, which matters because anesthesia time is a concern.
Veterinary MRI Market Segment Analysis
- By Solution, MRI scanners segment dominated the Veterinary MRI Market in 2025 with an estimated 43.00% share; software and services segment is the fastest-growing segment, with an estimated CAGR of 9.50% during 2026–2035.
- By Animal Type, small animals segment dominated the Veterinary MRI Market in 2025 with an estimated 69.00% share; large animals segment is the fastest-growing segment, with an estimated CAGR of 8.60% during 2026–2035.
- By Field Strength, low-field MRI segment dominated the Veterinary MRI Market in 2025 with an estimated 52.00% share; high-field MRI segment is the fastest-growing segment, with an estimated CAGR of 9.30% during 2026–2035.
- By End Use, veterinary hospitals segment dominated the Veterinary MRI Market in 2025 with an estimated 54.00% share; veterinary clinics segment is the fastest-growing segment, with an estimated CAGR of 8.90% during 2026–2035.
By Solution, MRI Scanners Dominates Veterinary MRI Market; Software and Services to Register Fastest Growth.
MRI scanners dominate the Veterinary MRI Market because the magnet and console are the largest purchase, with prices from several hundred thousand to more than a million dollars depending on field strength. Hospitals buy or lease a system, install it in a shielded room and then rely on it for years. Veterinary-specific scanners from Esaote, Hallmarq and others, as well as refurbished human systems, form the installed base, and every new hospital or replacement project adds scanner revenue. Service plans add further long-term revenue. Reliable uptime is key.
Software and services are projected to register the fastest growth because hospitals need maintenance contracts, remote operation, image analysis, reconstruction upgrades and cloud storage after installation. Artificial intelligence reconstruction shortens exams, and teleradiology lets general practices send images to specialists. Imaging-as-a-service models bundle equipment, installation, maintenance and software into a monthly payment, which converts capital cost to operating cost. Accessories and consumables, including coils and positioning aids, add recurring revenue. Cloud archives and viewers also make it easier for referring practices to receive reports quickly.
By Animal Type, Small Animals Dominates Veterinary MRI Market; Large Animals to Register Fastest Growth.
Small animals dominate the Veterinary MRI Market because dogs and cats account for most veterinary visits and owners are willing to pay for advanced diagnostics. Neurological conditions such as disc disease, seizures and brain tumors, together with orthopedic injuries and cancer, are routinely investigated by MRI. Specialty and emergency hospitals in cities have installed scanners to serve referral demand, and growth in pet insurance in several countries reduces cost barriers for owners. Referring general practices also send growing numbers of neurological and spinal cases to these centers.
Large animals, led by horses, are projected to register the fastest growth because MRI is highly valuable in diagnosing lameness in the foot, fetlock and other joints, and sport and breeding horses carry high value. Standing MRI systems avoid general anesthesia, and mobile services bring scanners to stables and racing centers. Equine hospitals in Europe, the Middle East and North America are adding or upgrading systems, while livestock and zoo animals add a small number of specialized scans. Insurance and specialist training for equine work further support spending. Insurance coverage also helps.
By Field Strength, Low-Field MRI Dominates Veterinary MRI Market; High-Field MRI to Register Fastest Growth.
Low-field MRI dominates the Veterinary MRI Market because systems below about 0.5 Tesla cost far less to buy, install and maintain than high-field scanners, and many are designed for animals with open geometry and simple shielding. Small and mid-sized practices can add an in-house scanner without large construction costs. Some low-field machines are suited to standing equine use, and newer designs reduce or remove helium, easing supply and quench risk. Lower purchase prices also widen the pool of buyers, including mid-sized practices and mobile providers.
High-field MRI of 1.0 Tesla and above is projected to register the fastest growth as referral hospitals and veterinary schools seek higher resolution for neurology, oncology and research. Stronger magnets give faster scans and finer detail of small structures such as the brain and spinal cord in cats and small dogs, which shortens anesthesia time. Many new installations use 1.5 Tesla systems, and 3 Tesla scanners are appearing at university hospitals that share expertise with human medicine. Specialists also prefer higher fields for research studies and for difficult brain and spinal cord diagnoses.
By End Use, Veterinary Hospitals Dominates Veterinary MRI Market; Veterinary Clinics to Register Fastest Growth.
Veterinary hospitals dominate the Veterinary MRI Market because they have the case volume, specialist staff and capital budgets needed to own and operate scanners. Referral hospitals, emergency centers and university teaching hospitals employ neurologists, orthopedic surgeons, oncologists and radiologists who order MRI daily. Group ownership of hospitals by large veterinary chains supports central purchasing and shared imaging services, and new hospitals are often designed with an MRI suite from the start. Large hospitals also support residency and internship programs, which attract specialists and improve case volumes for imaging.
Veterinary clinics are projected to register the fastest growth as smaller practices adopt compact, lower-cost systems or contract with mobile and shared imaging providers. Leasing, remote operation and imaging-as-a-service reduce the capital and staffing burden, while teleradiology gives clinics access to expert reports. Clinics in suburban and regional areas that previously referred patients to distant centers are installing scanners to retain revenue and offer faster diagnosis, which supports demand for entry-level systems. Shared or mobile MRI services also extend access for clinics that cannot justify buying equipment. Fast scans help.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
North America |
United States |
88.00 |
|
Europe |
Germany |
23.00 |
|
Asia Pacific |
China |
41.00 |
|
Latin America |
Brazil |
54.00 |
|
Middle East & Africa |
Saudi Arabia |
29.00 |
North America Veterinary MRI Market Insights
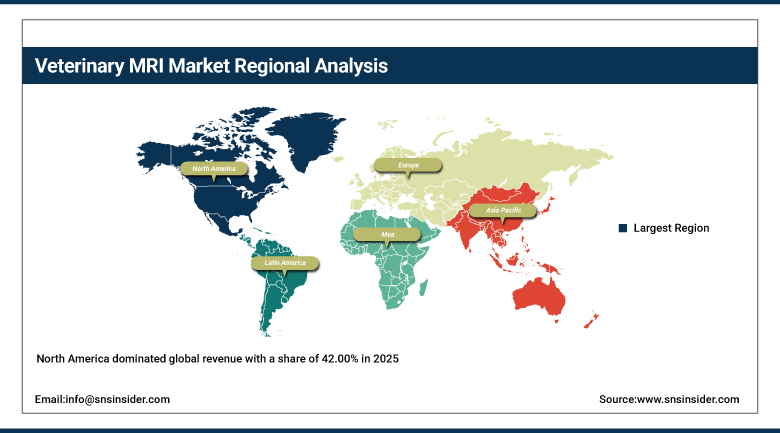
North America dominated global revenue with a share of 42.00% in 2025. The United States accounts for about 88.00% of regional demand, with Canada adding volume through veterinary colleges and specialty hospitals. Hallmarq, Esaote, Siemens Healthineers, GE HealthCare, Canon Medical Systems, FUJIFILM and IDEXX Laboratories serve hospitals and schools in the region. Canada adds demand through veterinary colleges in Ontario, Quebec, Saskatchewan and Atlantic Canada, and Mexico adds smaller volumes through private specialty hospitals in large cities. Pet insurance is widespread.
High companion animal spending, wide use of pet insurance and a large network of specialty and emergency hospitals support demand. Veterinary schools are modernizing teaching hospitals, and corporate hospital groups invest in imaging to keep referrals in their networks. Equipment cost, helium supply and a shortage of trained staff restrain growth, although leasing and remote operation models are helping smaller practices to adopt MRI. Equine MRI is also important in racing and sport horse centers in Kentucky, Florida and California, where owners accept high diagnostic spending to protect valuable animals.
⮞On March 25, 2025, the University of Missouri's Veterinary Health Center introduced an upgrade to a three-tesla MRI, described as the state's first and only three-tesla scanner for animals. The system produces sharper images and shortens anesthesia time for neurological, cardiovascular, oncologic and musculoskeletal cases.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Veterinary MRI Market Insights
In Europe Germany leads regional demand, followed by the United Kingdom, France, Italy, Spain and the Netherlands, supported by dense specialty hospital networks, equine sport and strong veterinary universities. Esaote and OR Technology are headquartered in the region, with Hallmarq in the United Kingdom, and Siemens Healthineers and Mediso are also active. Scandinavian countries add demand through university animal hospitals, and Poland and other Eastern European countries are growing as new private specialty hospitals appear and import scanners from regional suppliers. Germany hosts large hospitals.
European suppliers have developed veterinary-specific magnets, including low-field and standing equine systems, and export them widely. Horse racing, show jumping and breeding drive equine MRI use, while small animal referral centers are expanding in large cities. Cost control by owners in some countries and differing practice standards slow adoption, but consolidation of hospital groups and supplier groups supports investment. Cooperation between universities, suppliers and hospital groups on training and imaging protocols helps new users adopt MRI with confidence, and cross-border teleradiology also spreads expertise.
⮞On July 3, 2025, Esaote presented the Vet-MR Grande ELITE at the ECVS 2025 annual meeting in Antwerp, Belgium. The system for small animals and horses uses the e-SPADES AI reconstruction platform developed with AIRS Medical and a diffusion weighted imaging sequence to help detect cerebral infarction and brain tumors.
Asia Pacific Veterinary MRI Market Insights
Asia Pacific is projected to be the fastest-growing region, at a CAGR of 9.80% during 2026-2035. China leads regional demand, followed by Japan, South Korea, Australia and India, supported by rapid growth in pet ownership, rising pet spending and expansion of specialty animal hospitals in major cities. Shenzhen Anke High-tech, Shenzhen Basda Medical Apparatus, Time Medical and Canon Medical Systems are among the suppliers. Singapore, Thailand and Malaysia add smaller volumes through private animal hospitals, and Australia and New Zealand add steady demand through equine and small animal referral centers. Rising incomes support spending.
Chinese manufacturers offer lower-cost permanent magnet systems that suit new hospitals, while Japanese and Korean hospitals buy premium imported scanners. Pet humanization and growing incomes in urban areas support demand for advanced diagnostics, and large hospital chains are adding imaging centers. Limited numbers of veterinary radiologists, price sensitivity and uneven standards in smaller cities restrain growth, though demand is rising quickly. Local suppliers are also expanding service networks to support installed scanners, and veterinary schools in the region are building imaging facilities to train students and researchers.
MEA & Latin America Veterinary MRI Market Insights
In Latin America, Brazil leads on the strength of its large pet population and growing network of private specialty hospitals, followed by Mexico, Argentina and Colombia. Regional demand is supported by rising pet spending in large cities. Most scanners are imported or refurbished, and high equipment cost and exchange rate swings affect purchasing. Chile and Colombia add smaller volumes through private specialty hospitals, and veterinary universities in Argentina and Brazil provide referral imaging and training that supports spread of MRI use in the region. Peru adds steady demand.
In the Middle East and Africa, Saudi Arabia, the United Arab Emirates, Qatar and South Africa lead demand. Equine hospitals serving racing and endurance sport in the Gulf are important buyers, and private small animal hospitals in major cities are adding imaging. Limited numbers of specialists and high import cost restrain adoption in much of Africa. Egypt, Turkey and Israel add demand through private hospitals, and equine and camel racing centers in the Gulf provide high-value cases that need advanced imaging for lameness and injury.
Market Dynamics
Growth Drivers: Pet Spending, Specialty Care and Teaching Hospital Upgrades
Rising pet ownership and spending on companion animal care are central drivers of the Veterinary MRI Market. Owners increasingly seek the same standard of diagnosis for pets as for family members, and specialty hospitals offering neurology, orthopedics and oncology need MRI to support their services. Pet insurance in several countries further helps owners to approve advanced imaging. Veterinary specialization is also growing, with more neurologists and surgeons in practice who rely on MRI. Growth of pet insurance continues to support spending. Teleradiology access also helps smaller clinics.
Veterinary schools and teaching hospitals are replacing aging scanners and building new imaging suites to train students and support research. Better image quality and faster scans reduce anesthesia time, which makes MRI safer and more acceptable to owners. Corporate hospital groups also invest in imaging to build referral centers. Better public understanding of conditions such as spinal disc disease and brain tumors in pets further supports requests for scans. Equine sport spending adds high-value cases.
Restraints: Capital Cost, Staffing and Helium Dependence
MRI systems are expensive to buy, install and maintain, and many practices cannot justify the cost without high case volume. Shielded rooms, power and cooling requirements add expense. Anesthesia is needed for most scans, which carries risk and raises the cost to owners. Maintenance contracts and quench repairs add ongoing costs for owners of superconducting systems. Room design needs and radio frequency shielding add project time. Seasonal demand can also vary.
Trained technicians and board-certified radiologists are in short supply, and liquid helium used in many superconducting magnets is costly and subject to supply disruptions. These factors slow adoption among smaller practices and in emerging markets, even where demand for advanced diagnostics is growing. Limited reimbursement outside insured pets means owners often fund scans directly, which can lead to declined imaging. Anesthesia protocols require trained staff.
Opportunities: Low-Cost Magnets, AI Reconstruction and Service Models
Low-field and zero-helium magnets lower installation and running cost, bringing MRI within reach of mid-sized practices. Artificial intelligence reconstruction can cut scan time and improve image quality on lower-field systems, widening the range of cases that can be imaged. Suppliers can add value by offering training for technicians and remote support for new users. Upgrades of older scanners offer a cost-effective path to better images. Mobile units reach rural areas.
Imaging-as-a-service, leasing and remote operation convert capital spending into predictable payments and reduce the need for in-house technicians. Mobile equine MRI and teleradiology also create new revenue and extend access in regional and emerging markets. Partnerships between hospitals and universities can add research use that supports system utilization. Hospital groups can share systems across sites.
Recent Developments:
- In May 2026, the Louisiana State University School of Veterinary Medicine installed a Canon Orian 1.5 Tesla MRI system. The new scanner replaces the school's original system in service since 2009.
- In February 2026, OR Technology and Hallmarq Veterinary Imaging formed a global veterinary multimodality imaging group. The group has more than 200 employees across Europe, the Middle East and Africa, and North America.
- In July 2025, Esaote presented its Vet-MR Grande ELITE at the ECVS 2025 annual meeting. The system adds AI reconstruction and diffusion weighted imaging for small animals and horses.
- In March 2025, the University of Missouri Veterinary Health Center upgraded to a three-tesla MRI. The system shortens anesthesia time and sharpens soft tissue images.
Veterinary MRI Market Key Players are:
- Esaote S.p.A.
- Hallmarq Veterinary Imaging Ltd.
- OR Technology
- Bruker Corporation
- Mediso Medical Imaging Systems
- MR Solutions
- Imotek International Ltd.
- Siemens Healthineers AG
- GE HealthCare
- Canon Medical Systems Corporation
- FUJIFILM Holdings Corporation
- Mindray Medical International Ltd.
- IMV Imaging
- Koninklijke Philips N.V.
- Time Medical Holding
- IDEXX Laboratories, Inc.
- Shenzhen Anke High-tech Co., Ltd.
- Shenzhen Basda Medical Apparatus Co., Ltd.
- FONAR Corporation
- Shimadzu Corporation
Veterinary MRI Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 218.00 Million |
| Market Size by 2035 | USD 453.50 Million |
| CAGR | CAGR of 7.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Solution (MRI Scanners, Software and Services, and Accessories and Consumables) • By Animal Type (Small Animals and Large Animals) • By Field Strength (Low-Field MRI, Mid-Field MRI, and High-Field MRI) • By End Use (Veterinary Hospitals, Veterinary Clinics, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Esaote S.p.A.; Hallmarq Veterinary Imaging Ltd.; OR Technology; Bruker Corporation; Mediso Medical Imaging Systems; MR Solutions; Imotek International Ltd.; Siemens Healthineers AG; GE HealthCare; Canon Medical Systems Corporation; FUJIFILM Holdings Corporation; Mindray Medical International Ltd.; IMV Imaging; Koninklijke Philips N.V.; Time Medical Holding; IDEXX Laboratories, Inc.; Shenzhen Anke High-tech Co., Ltd.; Shenzhen Basda Medical Apparatus Co., Ltd.; FONAR Corporation; Shimadzu Corporation |

Frequently Asked Questions
Key players include Esaote S.p.A., Hallmarq Veterinary Imaging Ltd., OR Technology, Bruker Corporation, Siemens Healthineers AG, GE HealthCare, Canon Medical Systems Corporation and FUJIFILM Holdings Corporation.
Key opportunities include low-field and zero-helium magnets, AI reconstruction to shorten scan times, and imaging-as-a-service and mobile equine models.
The major growth factor is rising pet ownership and spending on companion animal care, together with growth of specialty hospitals and teaching hospital upgrades.
By Solution, the MRI Scanners segment dominated the market in 2025 with an estimated 43.00% share, supported by the high value of magnets and consoles.
North America dominated the market with a share of 42.00% in 2025, driven by high pet spending, specialty hospitals and teaching hospital investment.
