
Video Encoder Market Report Scope and Overview
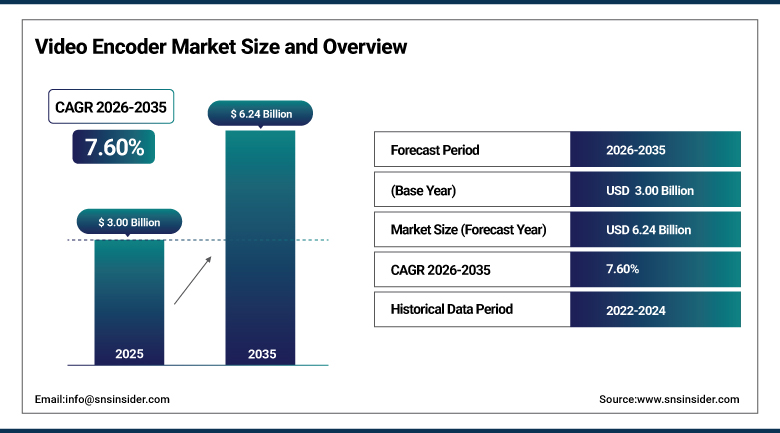
The Video Encoder Market was valued at USD 3.00 Billion in 2025 and is estimated at USD 3.23 Billion in 2026. The market is forecast to reach USD 6.24 Billion by 2035, registering a CAGR of 7.60% from 2026 to 2035. Growth reflects the surge in live streaming and over-the-top video, the move of broadcast contribution and distribution to internet protocol networks, the adoption of efficient codecs such as HEVC and AV1, and the migration of surveillance systems to high-resolution internet protocol cameras and analytics. North America accounted for the largest regional share at 36.40% in 2025, while Asia Pacific is expected to expand fastest.
To Get more information Video Encoder Market - Request Free Sample Report
Key Market Trends & Insights
-
By number of channels: Multi-channel encoders held the largest market share of 64.50% in 2025.
-
By type: Rack-mounted encoders held the largest market share of 71.80% in 2025.
-
By application: Broadcasting held the largest market share of 56.30% in 2025.
-
North America accounted for the largest regional share of 36.40% in 2025.
-
Asia Pacific is projected to register the fastest regional CAGR of 9.30% from 2026 to 2035.
-
Standalone encoders are the fastest growing type, multi-channel encoders are the fastest growing channel class, and broadcasting is the fastest growing application.
Growth Outlook
Streaming demand is the first pillar of growth. Broadcasters, sports leagues, news organizations, houses of worship, schools, and corporations now stream live events to many screens, and each stream begins with an encoder that compresses camera or studio feeds into formats that networks can carry. Live sports, news, and esports events push buyers toward low-latency, high-quality contribution encoders, and the spread of 4K and high dynamic range content raises the processing power each channel requires. Carriers also invest ahead of major events.
Network transition is the second pillar. Broadcasters are moving from serial digital interfaces to internet protocol workflows based on standards such as SMPTE ST 2110 and reliable transport protocols such as SRT, and these workflows rely on encoders to move video over managed and public networks. Surveillance operators also upgrade to higher-resolution cameras and analytics, which require encoders that bring legacy analog cameras onto internet protocol networks and compress streams efficiently, and this supports the forecast growth through 2035. Telecom carriers also deploy 5G contribution links for events, which adds endpoints that need compact, resilient encoders.
Market Dynamics
Driver: Live Streaming Growth, Efficient Codecs, and Internet Protocol Production Workflows Expand Encoder Deployments
Live video has become a regular part of broadcasting, sport, education, worship, and corporate communication, and organizations increasingly stream events to social platforms, websites, and television networks at the same time. This multiplies the number of encoders needed at venues, studios, and remote production sites, and many operators now deploy compact encoders for remote and cloud-based production because they reduce the need for outside broadcast trucks and large crews. Rising audience expectations for sharp, stable video add to demand. Sports leagues and rights holders also create more feeds per event, including alternate camera angles, language versions, and personalized streams, and each feed needs its own encoding chain, which lifts channel counts at stadiums and production centers every season.
Codec progress adds a second push. HEVC, AV1, and JPEG XS deliver the same picture quality at far lower bitrates or with very low latency, and buyers replace older H.264 equipment to cut bandwidth and delivery costs. Artificial intelligence features such as scene-aware rate control, automated captioning, and content analysis are also being built into encoders, and the move to cloud and hybrid workflows keeps operators buying flexible platforms that run both on premises and in the cloud. Higher resolutions such as 4K and high dynamic range also raise the processing needed per channel, so even stable channel counts translate into larger hardware purchases, and suppliers that support several codecs in one unit reduce upgrade costs for customers with mixed distribution targets.
Restraint: Shift to Software and Cloud Encoding, Price Pressure, and Security Restrictions on Some Suppliers Limit Hardware Revenue
Software and cloud encoding services run on general-purpose servers and graphics processors and cost less per channel than dedicated appliances, so some broadcasters and streaming platforms shift workloads away from hardware. Cameras and production switchers that include built-in encoders also reduce the need for separate devices, and price competition among suppliers from Asia compresses margins in entry-level and mid-range classes. Cloud providers also bundle encoding into media services with usage-based pricing, which appeals to customers that want to avoid capital spending and scale capacity up and down for individual events. Open source encoding tools further lower the barrier for streaming start-ups that once needed purpose-built appliances, and this slows hardware growth.
Procurement restrictions add a further limit. Several governments restrict public agencies from buying surveillance and video equipment from certain Chinese suppliers, which reduces addressable demand in those channels and forces buyers to change vendors in the middle of projects. Cybersecurity requirements raise the cost of certifying devices, and long qualification cycles at large broadcasters slow the adoption of new platforms. Consolidation of broadcasters and tight advertising budgets also lead some customers to extend equipment lifetimes, and many delay major upgrades until codec and standard choices are clear. Uncertainty about tariffs on electronic components and long lead times for chips used in encoder cards can further delay deliveries and push buyers toward software alternatives.
Opportunity: Remote Production, Cloud-Managed Fleets, and Artificial Intelligence Enabled Encoding Open New Revenue Pools
Remote and distributed production offers the strongest opportunity. Broadcasters send camera feeds from venues to central studios or the cloud over the internet, and they need encoders that deliver low latency, resilient transport, and bonded cellular links. Suppliers that provide compact field units together with cloud management, monitoring, and licensing can win both equipment and recurring software revenue from the same customers. Sports leagues, news agencies, and houses of worship also seek simple units that non-technical staff can operate, and managed contribution services that combine encoders, transport, and monitoring give suppliers a path to subscription income from customers that lack engineering teams.
Artificial intelligence and efficient codecs give a second opening. Encoders with content-aware optimization lower bandwidth costs for streaming platforms and carriers, and surveillance buyers want devices that run analytics at the edge before video is sent to storage. Growth in education, healthcare, government, and enterprise video, along with 5G contribution links and cloud gaming, adds further demand beyond classic broadcast and security applications. Public safety agencies, hospitals, and universities also expand video networks for training, telemedicine, and campus security, and each of these buyers needs encoders with strong security features, which favors suppliers with certified products and long product support lives.
Market Characteristics & Concentration
The Video Encoder Market is Moderately Consolidated. A group of broadcast technology specialists, network and cloud providers, and security camera makers share most revenue, while many smaller firms compete in specific channel classes or regions, and no single company controls the market. Competition centers on picture quality at a given bitrate, latency, density, codec support, interoperability, and software features. Regional specialists in Asia and Europe win business on price and local support, and standards compliance is a baseline requirement for large awards.
The level of merger and acquisition activity is moderate. Larger suppliers acquire software, cloud, and artificial intelligence capabilities to broaden their portfolios, and video businesses of large network equipment makers have moved to specialist owners. Entry barriers include codec expertise, hardware design, interoperability with broadcast standards, and trusted relationships with broadcasters and public agencies. Partnerships between encoder makers, cloud providers, and chip suppliers are common, and licensing of codec technology lets smaller firms bring new formats to market quickly through shared development.
Customers include broadcasters, cable and satellite operators, streaming platforms, sports and live event producers, telecom carriers, and security integrators, and purchases range from single field units to large headend and venue systems. Buyers weigh picture quality, latency, reliability, density per rack unit, standards support, and the quality of long-term software and hardware support. Large broadcasters often run extended trials against several suppliers before awarding multi-year contracts, and system integrators and distributors reach smaller customers in security, education, and enterprise markets across regions.
Analyst Perspective
The video encoder market has moved from a hardware box story to a workflow and software story. Buyers no longer ask only how many channels fit in a rack. They ask how well an encoder supports internet protocol standards, low-latency transport, new codecs, remote production, and cloud management, and how easily it can be updated as formats change. Suppliers that pair dense, reliable hardware with software licensing, cloud services, and artificial intelligence features will capture the largest share of new spending through 2035. Remote production and edge analytics add upside beyond classic broadcast and security applications. An SNS Insider Analyst, Santosh Bhul, commented, "Video encoder suppliers will win by making encoding flexible, software defined, and easy to run across venues, data centers, and the cloud."
Segment Analysis
Number of Channels Insights
Multi-channel encoders accounted for the largest share of 64.50% in 2025. Headends, data centers, venues, and security command centers need to process many streams in a small space, and units that handle two, four, eight, sixteen, or more channels lower the cost and power per stream. Large broadcasters and carriers favor high-density platforms that can be shared across channels and moved between tasks as demand changes. Vendors also offer software licensing that lets customers add channels or codecs without changing hardware, and this protects the investment of buyers that expect formats and channel counts to change over time.
Multi-channel encoders are also anticipated to grow at the fastest CAGR of 8.00% from 2026 to 2035, as operators consolidate workloads and move to blade and chassis designs. Single-channel encoders remain popular for field reporting, small venues, houses of worship, and individual camera feeds, where portability and low cost matter more than density, and they serve as entry points for buyers moving into live streaming. Modular designs with hot-swappable blades keep service interruptions short in busy facilities, and operators value redundancy features that keep streams running during hardware failure. Cloud-managed single-channel units also suit schools and small studios.
Type Insights
Rack-mounted encoders held the largest share of 71.80% in 2025. These units fit standard equipment racks in broadcast facilities, data centers, and security rooms, and they provide redundant power, many inputs, and remote management for round-the-clock operation. Their strength reflects the dependence of broadcasters, operators, and large venues on carrier-grade reliability and centralized monitoring. Standard rack designs also simplify upgrades, because operators can replace blades or modules without redesigning racks, cabling, or monitoring systems, and long support life protects the investment of large facilities. Redundant fans and hot-swap parts also reduce downtime.
Standalone encoders are projected to expand at the fastest CAGR of 8.70% from 2026 to 2035, driven by remote production, mobile newsgathering, education, and enterprise streaming, where compact units are placed at cameras or in small studios. Suppliers add bonded cellular, SRT, and cloud management to these portable devices, which makes them easy to deploy without engineers on site. Many portable units now support power over Ethernet and battery operation, which suits camera-mounted use, mobile newsgathering vehicles, and temporary venues, and cloud dashboards let a small team monitor large fleets of field units.
Application Insights
Broadcasting accounted for the largest share of 56.30% in 2025, including television networks, cable, satellite, internet protocol television, sports production, and streaming. Encoders compress feeds for contribution, distribution, and delivery to many devices, and the need for high picture quality at low bitrates keeps spending steady. Broadcasters upgrade to new codecs and internet protocol workflows to lower delivery cost. Sports production, news, and entertainment networks account for the largest spending, because they stream many hours of live content and require high quality and very low latency to stay competitive with rival platforms.
Broadcasting is also expected to grow at the fastest CAGR of 8.60% from 2026 to 2035, helped by live sports, news, and over-the-top services. Surveillance held the remaining share, led by encoders that connect analog cameras to internet protocol systems in transport, retail, city, and industrial sites, and it grows steadily as cities and operators add high-resolution cameras and analytics. Surveillance buyers value encoders that support multiple streams, secure transmission, and compatibility with video management software, while cybersecurity rules and procurement limits on some suppliers influence purchasing decisions in government and critical infrastructure sites.
Regional Insights
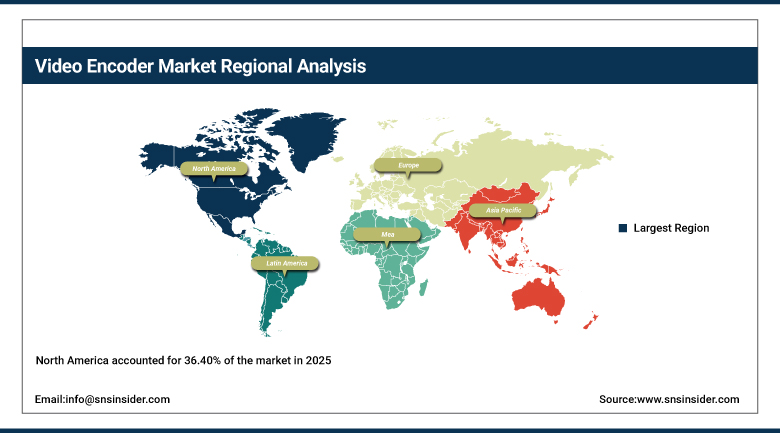
North America accounted for 36.40% of the market in 2025. Demand in the region follows a mature broadcast and streaming industry, large sports and news operations, extensive public safety and enterprise video networks, and the home base of several leading encoder and cloud suppliers, which keeps technology adoption fast. Mexico is reported within Latin America. Large sports leagues, news networks, and streaming platforms in the United States and Canada lead adoption of new codecs and remote production, and public safety and enterprise video networks add steady replacement demand.
Get Customized Report as per Your Business Requirement - Enquiry Now
U.S. Video Encoder Market
The U.S. Video Encoder Market was valued at USD 939.12 Million in 2025 and is projected to expand at a CAGR of 7.20% from 2026 to 2035. The country has the largest sports, news, and streaming industries in the region, and the next generation broadcast standard ATSC 3.0 and growth in local live production support demand. Section 889 of the National Defense Authorization Act for Fiscal Year 2019 bars federal contractors from using equipment from specified Chinese suppliers from 13 August 2020, which shapes procurement of security video encoders.
Europe Video Encoder Market
Europe accounted for 22.10% of the market in 2025, led by Germany, the United Kingdom, France, Italy, and Spain. Public broadcasters, pay television operators, and sports rights holders invest in internet protocol production and efficient codecs, and several leading encoder suppliers are based in France and other countries of the region. The NIS2 Directive, whose national transposition deadline was 17 October 2024, raises cybersecurity requirements for operators of critical services and encourages upgrades of video networks.
Asia Pacific Video Encoder Market
Asia Pacific is projected to register the fastest regional CAGR of 9.30% from 2026 to 2035, and the region held 29.30% of the market in 2025. China, Japan, India, and South Korea lead through large surveillance camera installations, expanding streaming platforms, and heavy investment in 4K and 8K broadcasting, and the region is also home to major security camera and encoder makers. Large public broadcasters and sports events also push investment in live contribution equipment.
India, Australia, Southeast Asia, and Vietnam add growing demand through new cable and satellite services, smart city programs, and live commerce streaming. Local suppliers in China offer low-cost encoders for surveillance and enterprise use, while Japanese broadcasters invest in high-end contribution systems, and growing mobile video use supports volume growth across the region. Rising demand for cloud gaming, live commerce, and mobile video also encourages carriers and platform operators to expand encoding capacity, and vendors report strong interest in compact encoders for remote production across the large and varied geography of the region.
Latin America Video Encoder Market
Latin America held 5.60% of the market in 2025. Brazil and Mexico lead through large television networks, growing streaming services, and expanding public safety and transport surveillance, while Argentina, Colombia, and Chile add demand through sports broadcasting and city camera projects. Growth follows the shift of broadcasters to internet protocol delivery and the expansion of broadband and mobile video access. Telecom operators and cable companies also upgrade to efficient codecs to carry more channels over limited bandwidth.
Middle East & Africa Video Encoder Market
The Middle East and Africa accounted for 6.60% of the market in 2025. Saudi Arabia, the United Arab Emirates, and Qatar invest in sports events, broadcast centers, and smart city security networks, and large state-backed programs support imported equipment. South Africa, Nigeria, and Egypt add demand through pay television, public safety, and streaming, though budgets and infrastructure vary widely across the region. Large events such as global sports tournaments also create short-term spikes in broadcast equipment purchases.
Key Video Encoder Market Company Insights
Participants in the video encoder market include broadcast technology specialists, security camera and video makers, and cloud providers with media services. Leading firms compete on picture quality, latency, density, and software features, while smaller firms compete on price, portability, and regional support.
Key Video Encoder Companies:
-
Harmonic Inc.
-
Haivision Systems Inc.
-
ATEME SA
-
VITEC
-
Axis Communications AB
-
Hangzhou Hikvision Digital Technology Co., Ltd.
-
Matrox Electronic Systems Ltd.
-
Telestream, LLC
-
Amazon Web Services, Inc.
-
Blackmagic Design Pty Ltd
Recent Developments
-
In April 2026, Haivision Systems Inc. unveiled Makito ONE at the NAB Show, a live video contribution platform that supports H.264, HEVC, and JPEG XS on a single compact blade configurable as an encoder, a decoder, or both, and scales to as many as 36 high definition or 4K channels in a four rack unit chassis.
-
In April 2026, ATEME SA presented encoding with AV1, high dynamic range, and intelligent rate control at the NAB Show, claiming bitrate savings of up to 20% without loss of quality, and introduced cloud-based statistical multiplexing for ATSC offered as software as a service for disaster recovery.
-
In April 2026, Matrox Electronic Systems Ltd. showed the Vion multichannel 4K internet protocol gateway for encoding, decoding, transcoding, and cross-conversion, deployable on premises or in the cloud, along with the Monarch EDGE encoder for low-latency remote production and distribution at the NAB Show.
Scope and Research Methodology
The study defines the Video Encoder Market as the revenue generated by standalone and rack-mounted video encoders that compress live or recorded video for broadcasting, streaming, and surveillance, including hardware appliances, embedded encoding modules, and the encoding software and licenses sold with them. Video decoders sold separately, cameras, network video recorders, and subscription video platforms and cloud streaming services are outside the scope. The base year is 2025, the forecast period runs from 2026 to 2035, and all values are expressed in USD. The segmentation covers number of channels, type, application, and region, along with leading countries in each region. Mexico is reported within Latin America. Revenue is counted at the point of sale to the end user or integrator.
The research program combines secondary and primary research. Secondary research draws on company annual reports and filings, broadcast and telecom regulator publications, standards body documents, customs and trade data, patent filings, and peer-reviewed and industry publications. Primary research consists of structured interviews and surveys with encoder makers, broadcasters, streaming platforms, security integrators, distributors, and carriers. These discussions validate assumptions on channel shipments, selling prices, codec adoption, and the split between hardware and software, and responses are weighted by the seniority and relevance of each respondent.
Market engineering follows a bottom-up build from shipments by channel class and type, installed base, and selling prices, cross-checked top-down against spending in broadcast, streaming, and security infrastructure. Triangulation across both approaches narrows differences before values are finalized. Forecasts reflect drivers such as live streaming growth, codec change, and the shift to internet protocol workflows, and every estimate passes through an analyst quality review that tests consistency across segments, regions, and years. Sensitivity checks test the effect of changes in the pace of cloud migration, component supply, and procurement restrictions, and regional estimates are aligned so that country values add to regional totals and regional totals add to the global value.
Video Encoder Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.00 Billion |
| Market Size by 2035 | USD 6.24 Billion |
| CAGR | CAGR of 7.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Number of Channels (Single Channel and Multi-Channel) • By Type (Standalone Encoders and Rack-Mounted Encoders) • By Application (Broadcasting and Surveillance) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Harmonic Inc., Haivision Systems Inc., ATEME SA, VITEC, Axis Communications AB, Hangzhou Hikvision Digital Technology Co., Ltd., Matrox Electronic Systems Ltd., Telestream, LLC, Amazon Web Services, Inc., Blackmagic Design Pty Ltd |

Frequently Asked Questions
The market was valued at USD 3.00 Billion in 2025 and is projected to reach USD 6.24 Billion by 2035.
The market is expected to register a CAGR of 7.60% from 2026 to 2035.
North America led the market with a 36.40% share in 2025.
Asia Pacific is expected to grow the fastest, at a CAGR of 9.30% from 2026 to 2035.
Rack-mounted encoders led the type segment with a 71.80% share in 2025, and broadcasting led the application segment.
