
Wealth Management Platform Market Report Scope & Overview:
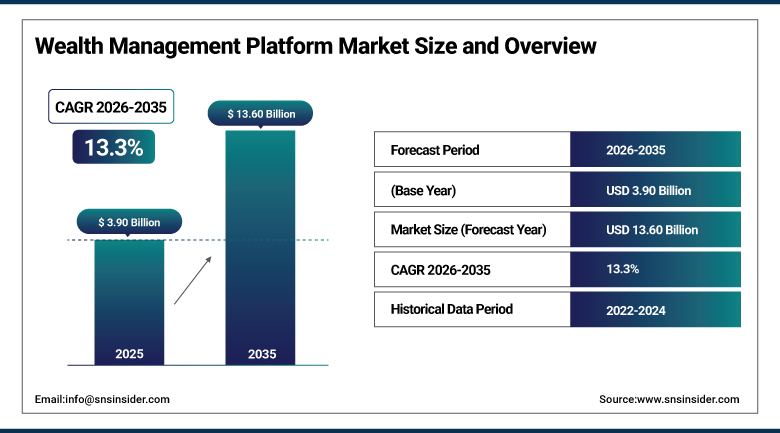
The Wealth Management Platform Market was valued at USD 3.90 billion in 2025 and is projected to reach USD 13.60 billion by 2035, expanding at a CAGR of 13.3% during the forecast period.
Wealth management platform solutions offer the enterprise software platform that is required by banks, asset managers, and advisory firms to manage their client portfolio management, automated financial advice, compliance and risk management, and reporting needs on the back of client relationships that are increasingly digital first. Financial firms are moving increasingly away from legacy solutions to platforms that can integrate planning, tax, and compliance systems via APIs and are especially prevalent amongst independent registered investment advisors that emphasize open architecture solutions over the proprietary banks' platforms. An increasing number of high net worth individuals, along with a growing mass affluent segment, has led to the continued adoption trend, as technologically savvy millennials expect more personalized digital wealth management.
Financial firms are adopting more AI-based analytical tools to improve efficiency in advice delivery. There has been an increasing number of wealth management firms who are adopting multi-asset digital portfolio management tools combining both traditional and alternative assets. Bank affiliated platforms are focused on scalability and custody capabilities, whereas independent advisory firms are increasingly looking at modular and API-enabled platforms that would allow them to integrate best-of-class planning, tax, and compliance tools instead of going for a fully-integrated suite from a single vendor. Vendor differentiation has become about the number of pre-built integrations offered within the partner ecosystem since implementation speed and total cost of ownership are as important as functionality in platform choice. Such an ecosystem-based approach to vendor differentiation is especially influential for mid-sized firms who want to avoid costly custom integration projects that big companies could easily accommodate with greater technology capabilities.
According to industry statistics, by 2024 more than 78% of financial firms were utilizing wealth management platforms to optimize advisory and portfolio management processes, and there were more than 2,100 wealth management firms globally that were utilizing AI-based analytics tools.
To Get more information Wealth Management Platform Market - Request Free Sample Report
Wealth Management Platform Market Market Trends
-
Rising adoption of AI-based analytics and automated advisory tools enhancing portfolio management efficiency
-
Growing shift from on-premises legacy systems toward cloud-based, API-connected wealth management platforms
-
Increasing demand for modular, open-architecture platforms among independent registered investment advisors
-
Rising integration of multi-asset class digital portfolio management supporting alternative investment exposure
-
Growing use of embedded wealth management platforms within broader digital banking customer experiences
-
Expanding hybrid advisory models combining automated robo-advisory tools with human relationship management
U.S. Wealth Management Platform Market Outlook
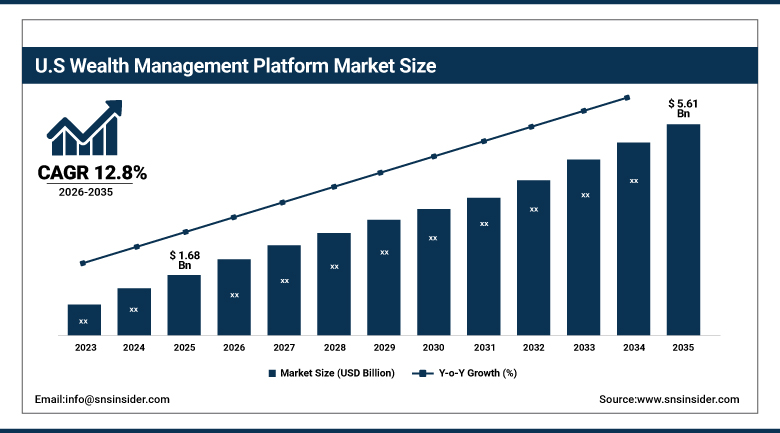
The U.S. wealth management platform market was valued at USD 1.68 billion in 2025 and is projected to reach USD 5.61 billion by 2035, growing at a CAGR of 12.8% during 2026-2035.
The U.S. remains the largest single-country market globally, supported by the world's highest concentration of high-net-worth individuals and a well-established registered investment advisor industry increasingly competing with large bank-affiliated wealth management divisions for the same affluent client base. Major U.S. banks continue to invest heavily in platform modernization to defend market share against both boutique advisory firms and direct-to-consumer robo-advisory entrants targeting the mass affluent segment.
Continued demand for modular and best-in-class platform architectures from U.S. independent RIAs sees these RIAs choosing vendors with open APIs who integrate specialized planning, tax, and compliance tools rather than those with full-stack solutions that keep advisors tied to one vendor's complete technology solution. Increased competition from consumer-facing robo-advisors keeps wealth management firms under pressure to roll out their digital advisory capabilities faster, especially in cases where client segments have been deemed too small to fall within the HNW client definition. At the same time, the custodial platform space for independent advisors is improving their self-service onboarding solutions.
As of 2025, high-net-worth individuals continued to represent a disproportionate share of U.S. retail bank net income, reinforcing sustained institutional investment in wealth management platform capability aimed at winning and retaining this client segment.
Wealth Management Platform Market Segment Analysis
-
By Deployment, the On-Premises segment dominated the Wealth Management Platform Market with approximately 44.3% share in 2025, while the Cloud segment is the fastest growing with a CAGR of approximately 15.8%.
-
By Advisory Model, the Human Advisory segment dominated the Wealth Management Platform Market with approximately 48.6% share in 2025, while the Robo-Advisory segment is the fastest growing with a CAGR of approximately 16.4%.
-
By End-User Industry, the Banks segment dominated the Wealth Management Platform Market with approximately 48.9% share in 2025, while the Investment Management Firms segment is the fastest growing with a CAGR of approximately 14.2%.
By Deployment, On-Premises Dominates the Wealth Management Platform Market While Cloud Registers the Fastest Growth
On-Premises occupied the major share in the Wealth Management Platform Market in 2025 as a result of the reason that larger banks and existing wealth management teams still prefer the on-premises infrastructure as it offers them the benefit of managing their data, compliance security structures, and customizations that come along with on-premises infrastructure, especially when dealing with sensitive financial data of clients.
Cloud is the fastest growing segment in the Wealth Management Platform Market as a result of the fact that the financial institutions are increasingly adopting the cloud based platforms to improve operational efficiency and also for remote management of their portfolios. Investment advisory firms are demanding cloud based digital portals to promote collaboration between the advisers and their clients by providing real time portfolio information and automatic financial reporting.
By Advisory Model, Human Advisory Dominates the Wealth Management Platform Market While Robo-Advisory Registers the Fastest Growth
Human Advisory dominated the Wealth Management Platform Market in 2025 due to the fact that high-net-worth and ultra-high-net-worth clients continue to place strong value on personalized relationship management and bespoke financial planning that fully automated tools cannot yet replicate, particularly for complex estate planning, tax optimization, and philanthropic giving strategies.
Robo-Advisory is the fastest-growing segment in the Wealth Management Platform Market due to the fact that rising demand for automated, low-cost investment management among the mass affluent and younger investor segments continues to expand adoption of algorithm-driven portfolio management tools. Growing integration of robo-advisory capability within hybrid platforms, rather than as standalone competitors to traditional advisory, continues to accelerate this segment's growth rate.
By End-User Industry, Banks Dominates the Wealth Management Platform Market While Investment Management Firms Register the Fastest Growth
Banks dominated the Wealth Management Platform Market in 2025 due to the fact that this end-user category generates immense client transaction and portfolio data as millions of customers access banking applications and websites across manifold devices, giving banks both the client base scale and the technology budget to invest heavily in comprehensive wealth management platform capability.
Investment Management Firms is the fastest-growing segment in the Wealth Management Platform Market due to the fact that asset managers are increasingly deploying multi-asset class digital portfolio tools to compete more effectively for institutional and high-net-worth mandates, a capability that was historically differentiated primarily through personal relationships rather than technology platform sophistication.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
81.0% |
|
Europe |
United Kingdom |
27.0% |
|
Asia Pacific |
China |
35.0% |
|
Middle East & Africa |
UAE |
34.0% |
|
Latin America |
Brazil |
37.0% |
North America Wealth Management Platform Market Insights
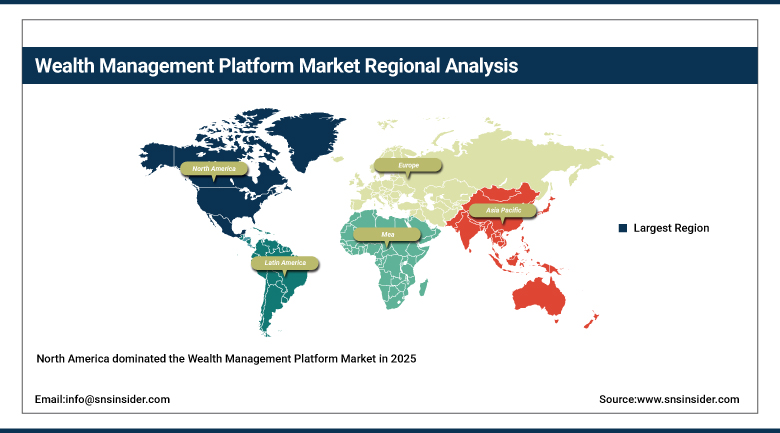
North America dominated the Wealth Management Platform Market in 2025, supported by the region's high concentration of wealth and advanced financial infrastructure that enables large-scale platform implementation across both bank-affiliated and independent advisory channels.
Canadian wealth management firms continue to expand platform investment as major domestic banks compete with U.S. cross-border wealth management divisions for high-net-worth client relationships, while Mexican financial institutions are gradually increasing platform adoption to serve a growing regional affluent client base.
U.S. regional and community banks continue to expand wealth management platform investment as a client retention strategy, recognizing that affluent depositors increasingly expect integrated banking and investment advisory experiences from a single institution.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Wealth Management Platform Market Insights
Europe's market is supported by strong wealth management activity in the UK, Switzerland, and Germany, where established private banking traditions continue to drive demand for platforms combining bespoke reporting capability with the trustee and philanthropic tracking functionality favored by European family offices.
Swiss private banks continue to invest heavily in platform modernization to defend their traditional wealth management leadership position against growing competition from digitally native entrants targeting the same international high-net-worth client base.
Asia Pacific Wealth Management Platform Market Insights
The Asia Pacific region is witnessing the fastest growth among all regions in terms of the Wealth Management Platform market, driven by the rapid growth in the high net worth and mass affluent population in China, India, and Singapore, who are driving up the demand for digital wealth management platforms operated either by banks or independently.
Singapore remains a regional wealth management center for cross-border high net worth investments, whereas wealth management organizations from India and China are rapidly embracing digital platform technology to cater to the rising affluent investment community of their countries.
Japanese wealth management organizations are slowly upgrading their old platform infrastructure to meet the changing needs of their rapidly aging and highly concentrated wealthy population.
Middle East & Africa and Latin America Wealth Management Platform Market Insights
The Middle East & Africa region is growing steadily as Gulf state wealth management activity expands, with the UAE and Saudi Arabia emerging as regional wealth management hubs attracting both domestic high-net-worth clients and international capital seeking sophisticated digital advisory platforms. South African wealth management firms continue to serve as a regional financial technology reference point for sub-Saharan Africa, gradually expanding digital platform adoption among domestic private banks catering to the continent's growing affluent population.
Latin America is growing steadily as Brazilian and Mexican wealth management firms expand platform adoption to serve growing regional high-net-worth and mass affluent client bases, supported by rising financial market sophistication across the region's largest economies. Chilean and Colombian wealth management firms continue to expand platform investment as regional pension fund reform and growing capital market sophistication increase demand for institutional-grade portfolio management technology.
Growth Drivers: Rising HNWI populations and digital transformation pressure fueling platform adoption
Continued global growth in the number of high-net-worth individuals and the broader mass affluent segment is the primary structural driver of wealth management platform demand, as this demographic shift compels financial institutions to adopt sophisticated, integrated platforms capable of serving increasingly demanding client expectations at scale. Rising pressure on wealth management firms to operate more efficiently, driven by fee compression across the industry, continues to push institutions toward platform consolidation that reduces the operational cost of managing fragmented legacy systems across advisory, compliance, and reporting functions. Growing client expectations for personalized, digitally delivered wealth management experiences, particularly among younger, tech-savvy investors, are compelling both bank-affiliated and independent advisory firms to invest in modern platform capability to remain competitive for next-generation client relationships.
Expanding institutional adoption of AI-based analytics and multi-asset class portfolio management tools is broadening the functional scope of wealth management platforms beyond basic portfolio tracking into genuinely differentiated advisory decision support. Growing generational wealth transfer, as aging baby boomer wealth passes to younger, more digitally native heirs, is compelling wealth management firms to modernize client-facing technology to retain assets that might otherwise migrate to competing digital-first advisory platforms. Rising institutional adoption of alternative investment classes, including private equity, real estate, and digital assets, is expanding platform functional requirements beyond traditional public securities management, creating additional demand for specialized portfolio analytics capability.
Restraints: Legacy system integration costs and data security concerns limiting migration pace
Expensive and complicated processes involved with switching to the new cloud platforms from the old-fashioned on-premises systems hinder the adoption by large-scale companies that have high levels of risks aversion in terms of handling of regulated customer data. Data security and privacy issues surrounding the use of cloud-based services for storage of client financial data persist as barriers that discourage adoption by financial organizations that deal with ultra-high net worth clients.
Different regulation laws governing financial institutions in various jurisdictions make the process of implementation of wealth management platform complicated for the vendors. Scarcity of skilled professionals that can work in financial technology implementation hinders the pace at which mid-size wealth management firms can implement their platforms, resulting in longer implementation time than expected by the vendor.
Opportunities: Hybrid advisory models and emerging-market wealth expansion widening addressable demand
Growing adoption of hybrid advisory models combining automated robo-advisory tools with human relationship management presents a significant opportunity for platform vendors to serve the full spectrum of client segments from mass affluent to ultra-high-net-worth within a single integrated technology stack. Rapid wealth creation across Asia Pacific and Middle Eastern emerging markets presents a substantial growth opportunity for platform vendors able to localize compliance and reporting functionality for these regions' distinct regulatory environments. Expanding demand for modular, API-connected platform architecture among independent advisory firms offers vendors an opportunity to capture share from legacy full-stack providers by offering best-of-breed integration capability rather than requiring complete platform replacement.
Growing demand for integrated environmental, social, and governance investment reporting presents an opportunity for platform vendors to develop specialized sustainability-linked portfolio analytics capability, differentiating from competitors still offering only traditional performance and risk reporting. Growing interest in embedded finance, where wealth management functionality is offered as a component within broader digital banking or fintech ecosystems, presents an opportunity for platform vendors to reach client institutions through partnership channels beyond direct enterprise software sales.
Recent Developments
-
In 2024, BlackRock expanded its Aladdin Wealth platform capability, adding enhanced multi-asset class portfolio analytics targeting independent registered investment advisors and mid-size wealth management firms.
-
In 2023, Charles Schwab announced platform integration upgrades connecting its advisory technology with expanded third-party financial planning and tax software through open API architecture.
-
In 2024, Morgan Stanley expanded its digital wealth management platform capability, incorporating AI-based portfolio insights for its financial advisor network serving high-net-worth and mass affluent clients.
-
In 2023, Backbase B.V. launched an updated wealth management platform module targeting banks seeking to embed digital advisory capability within broader retail banking customer experiences.
-
In 2024, UBS Group AG expanded its digital wealth management platform investment across its global private banking network, incorporating hybrid advisory capability combining robo-advisory tools with relationship manager oversight.
-
In 2023, Addepar Inc. expanded its data aggregation and portfolio reporting platform capability, targeting family offices and registered investment advisors managing increasingly complex multi-asset-class portfolios.
Wealth Management Platform Market Key Players are:
-
BlackRock Inc.
-
SS&C Technologies Holdings
-
Temenos AG
-
Backbase B.V.
-
Broadridge Financial Solutions
-
FIS (Fidelity National Information Services)
-
InvestCloud Inc.
-
Charles River Development (State Street)
-
Avaloq Group AG
-
Objectway S.p.A.
-
Prometeia S.p.A.
-
SEI Investments Company
-
Dynasty Financial Partners
-
Addepar Inc.
-
Orion Advisor Solutions
-
Salesforce (Financial Services Cloud)
-
Microsoft Corporation
-
Fiserv Inc
Wealth Management Platform Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.90 Billion |
| Market Size by 2035 | USD 13.60 Billion |
| CAGR | CAGR of 13.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Deployment (On-Premises, Cloud) • By Advisory Model (Human Advisory, Hybrid, Robo-Advisory) • By End-User Industry (Banks, Investment Management Firms, Brokerage Firms, Trading & Exchange Firms) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BlackRock Inc., SS&C Technologies Holdings, Temenos AG, Backbase B.V., Broadridge Financial Solutions, FIS (Fidelity National Information Services), InvestCloud Inc., Envestnet Inc., Charles River Development (State Street), Avaloq Group AG, Objectway S.p.A., Prometeia S.p.A., SEI Investments Company, Dynasty Financial Partners, Addepar Inc., Orion Advisor Solutions, Salesforce (Financial Services Cloud), Oracle Corporation, Microsoft Corporation, Fiserv Inc. |
Frequently Asked Questions
Leading companies include BlackRock Inc., SS&C Technologies Holdings, Temenos AG, Backbase B.V., and Broadridge Financial Solutions, among other major financial technology and platform vendors.
Opportunities include growing adoption of hybrid advisory models combining robo-advisory with human relationship management, rapid wealth creation across Asia Pacific and Middle Eastern emerging markets, and expanding demand for modular, API-connected platform architecture.
Growth is driven by continued global growth in high-net-worth individual and mass affluent populations, rising pressure on wealth management firms to operate more efficiently, and growing client expectations for personalized, digitally delivered advisory experiences.
On-Premises dominates by deployment with approximately 44.3% share, Human Advisory dominates by advisory model with roughly 48.6% share, and Banks dominates by end-user industry with about 48.9% share; Cloud, Robo-Advisory, and Investment Management Firms are the fastest-growing segments within their respective categories.
North America is the largest regional market, led by the United States, while Asia Pacific, led by China, is the fastest-growing region through 2035.
