
Welding Gas/Shielding Gas Market Report Scope & Overview:
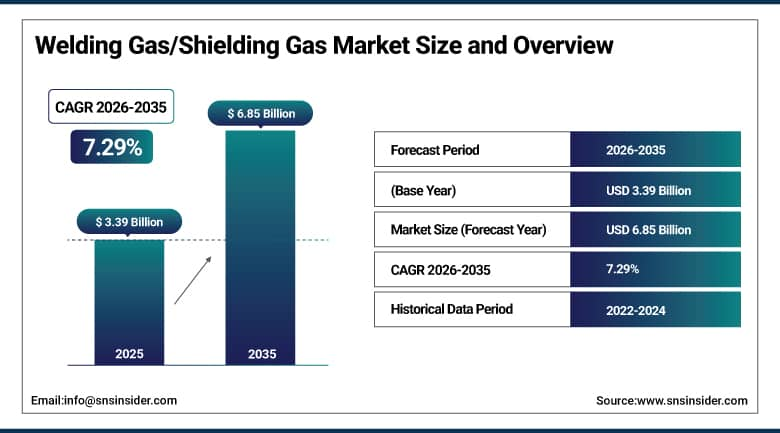
The Welding Gas/Shielding Gas Market was valued at USD 3.39 Billion in 2025 and is expected to reach USD 6.85 Billion by 2035, growing at a CAGR of 7.29% from 2026-2035.
The gases used in welding act at a very basic level when it comes to modern metal fabrication as they protect the molten weld pool from any environmental pollution during the process of arc welding and actually decide the strength, appearance, and effectiveness of the final weld. The increase during the historic period has been due to industrialization, construction activities, globalization of manufacturing activities, and continuous demands in the automobile industry since fabrication facilities, shipyards, and construction sites in all parts of the world have kept on using specifically formulated blends of gases for creating good and defect-free welds among different base metals and joints. The forecasted period's growth is further being influenced by increasing construction activities, economic growth in emerging markets, stringent weld quality regulations, and increased projects involving renewable energy infrastructure requiring large-scale steel fabrication. The growing use of welding automation technology in construction, automotive, and aerospace industries has been continuously changing the consumption pattern of these gases.
Linde announced it will build, own, and operate a new air separation unit in Oshkosh, Wisconsin, producing liquid oxygen, nitrogen, and argon to serve customers across Green Bay, Madison, Milwaukee, and Michigan's Upper Peninsula, with the plant expected to start up in the second half of 2028. The company noted that Wisconsin is experiencing incredible growth across multiple end markets, and this investment will allow it to produce product closer to its customer base while adding to its robust production and supply network, reflecting sustained industrial gas producer investment in expanding regional argon supply capacity to support the welding and metal fabrication sector's continued growth.
To Get More Information On Welding Gas/Shielding Gas Market - Request Free Sample Report
Welding Gas/Shielding Gas Market Trends
-
Rising adoption of hydrogen-argon blends supporting wire-arc additive manufacturing and reactive alloy welding applications.
-
Growing demand for ultra-high-purity argon supply chains supporting precision aerospace titanium and nickel welding programs.
-
Expanding automated welding cell deployment requiring increasingly precise, consistent gas-mix control across manufacturing lines.
-
Increasing regional air separation unit investment reducing supply chain dependence on long-distance gas imports.
-
Rising infrastructure investment in bridges, pipelines, and renewable energy towers driving sustained gas consumption.
-
Growing industry consolidation as leading gas producers expand geographic footprint through acquisitions and capacity investment.
U.S. Welding Gas/Shielding Gas Market Outlook
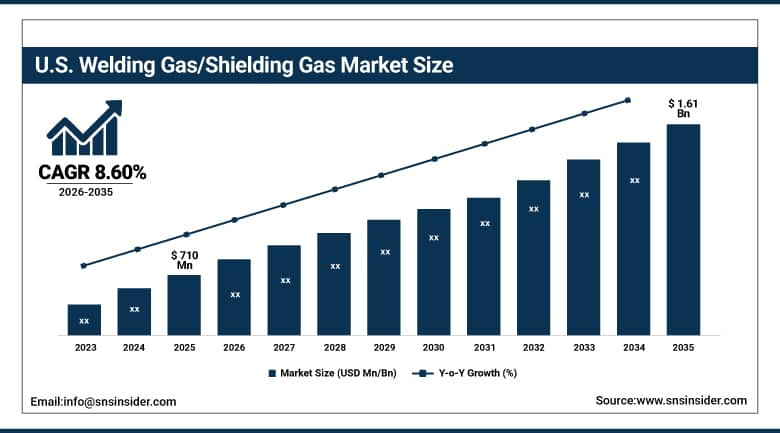
The U.S. Welding Gas/Shielding Gas Market was valued at USD 710 Million in 2025 and is expected to reach USD 1.61 Billion by 2035, growing at a CAGR of 8.60% from 2026-2035.
The United States Welding Gas/ Shielding Gas Market has been receiving a boost from the adoption of advanced welding technologies that have led to increased demand for shielding gases, increase in industrial automation leading to higher levels of gas consumption, and the increasing preference for environment-friendly shielding gases in the market. The region is expected to reap immense benefits from investments in infrastructure projects like bridges, pipelines, and renewable energy towers, where there will be considerable amounts of steel fabrication taking place, leading to an ongoing demand for both conventional argon-carbon dioxide gases and advanced gas formulations. The domestic demand for these products has been driven by the upgrading of infrastructure, increased automobile manufacturing, and growing investments in the construction and shipbuilding industries.
Linde announced it is doubling the capacity of its Freeport, Texas, carbon dioxide production facility by adding a second CO2 liquefaction plant, with the expanded facility starting up in 2027 to liquefy crude CO2 captured from industrial operations along the U.S. Gulf Coast. This capacity expansion directly supports the substantial carbon dioxide demand that welding gas blends require, given carbon dioxide's widespread use both as a standalone shielding gas for cost-sensitive applications and as a component within argon-carbon dioxide mixtures favored across automotive and general fabrication welding, reflecting sustained domestic industrial gas producer investment in expanding Gulf Coast production capacity to serve the region's substantial manufacturing base.
Welding Gas/Shielding Gas Market Segment Analysis
-
By Type, the Argon segment dominated the Welding Gas/Shielding Gas Market with approximately 44.60% share in 2025, while the Hydrogen segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Welding Process, the Gas Metal Arc Welding segment dominated the Welding Gas/Shielding Gas Market with approximately 46.60% share in 2025, while the Flux-Cored Arc Welding segment is the fastest growing with a CAGR of approximately 7.80%.
-
By End-Use Industry, the Automotive & Transportation segment dominated the Welding Gas/Shielding Gas Market with approximately 26.60% share in 2025, while the Aerospace & Defense segment is the fastest growing with a CAGR of approximately 8.60%.
-
By Storage Mode, the Cylinder & Packaged Gas segment dominated the Welding Gas/Shielding Gas Market with approximately 58.60% share in 2025, while the Merchant Liquid/Bulk segment is the fastest growing with a CAGR of approximately 7.60%.
By Type, Argon Dominates the Welding Gas/Shielding Gas Market and Hydrogen Grows Fastest
Argon commands the largest share of the market because it is inert, widely compatible with both metal inert gas and tungsten inert gas processes, and readily available across virtually every industrial gas supplier's product portfolio worldwide. This broad process compatibility means fabrication shops can standardize on argon-based gas mixtures across a wide range of welding applications and base metals without needing to maintain separate gas supply chains for different process types, a practical advantage that continues to reinforce argon's position as the foundational gas within the vast majority of commercially available shielding gas blends. Argon's inert chemical properties also make it particularly well-suited to welding reactive and non-ferrous metals, including aluminum, stainless steel, and titanium, applications where more chemically active shielding gases could introduce unwanted oxidation or porosity into the finished weld. As global manufacturing activity continues expanding across automotive, construction, and general metal fabrication, sustained demand for argon-based shielding gas blends continues to anchor this gas type's position as the largest category within the broader welding gas market by a substantial margin.
Hydrogen-based blends represent the fastest-growing gas type, driven by rising use in specialized stainless-steel welding and advanced industrial fabrication processes where improved penetration and faster welding speeds deliver genuine productivity advantages over conventional argon-only shielding gas formulations. The growing adoption of wire-arc additive manufacturing, an increasingly important advanced manufacturing technique that builds up metal components layer by layer using a welding arc as the heat source, continues to spark particular interest in hydrogen-argon blends, which have demonstrated genuine ability to enhance penetration and minimize porosity when welding reactive alloys commonly used in aerospace and other high-value manufacturing applications. As manufacturers across shipbuilding, stainless-steel fabrication, and advanced additive manufacturing continue seeking process improvements that reduce cycle time while maintaining or improving weld quality, hydrogen-based shielding gas blends continue to capture an increasing share of specialized welding gas demand, positioning this category for sustained above-market growth even from its currently smaller overall base relative to conventional argon and carbon dioxide blends.
By Welding Process, Gas Metal Arc Welding Dominates the Welding Gas/Shielding Gas Market and Flux-Cored Arc Welding Grows Fastest
Gas metal arc welding, commonly known as MIG welding, accounts for the largest revenue share among welding processes, reflecting its status as the most widely used arc welding process across automotive manufacturing, general fabrication, and construction applications worldwide. The process's relative simplicity, high deposition rates, and suitability for both manual and fully automated welding cell integration continue to make it the default choice for high-volume production environments where welding speed and consistency directly impact overall manufacturing throughput and cost. Gas metal arc welding's compatibility with a wide range of shielding gas formulations, spanning pure argon through various argon-carbon dioxide and argon-oxygen blends tailored to specific base metals and joint configurations, continues to reinforce this process's position as the largest single source of shielding gas consumption across the broader welding gas market, as manufacturers continue optimizing their specific gas mixture selection to balance weld quality, deposition rate, and overall gas consumption cost.
The flux cored arc welding technique, along with its advanced counterparts, such as laser welding, submerged arc welding, and electron beam welding, is experiencing the fastest growth among all welding process categories due to ongoing expansion of heavy fabrication, shipbuilding, and thick section welding applications involving structural steel, where these techniques offer significant productivity and penetration benefits over traditional gas metal arc welding. The flux cored arc welding method is specifically becoming increasingly popular in outdoor construction and structural steel applications because of its improved wind and environmental tolerance compared to the more sensitive gas metal arc welding processes. With ongoing growth in the size of infrastructure and industrial construction projects worldwide, the demand for these more specialized welding techniques that offer higher productivity results in above-average growth in demand for their required shielding gases.
By End-Use Industry, Automotive & Transportation Dominates the Welding Gas/Shielding Gas Market and Aerospace & Defense Grows Fastest
Automotive and transportation captured the largest share of welding gas consumption, reflecting the sheer scale of global vehicle production and the extensive welding operations required throughout automotive body-in-white assembly, chassis fabrication, and exhaust system manufacturing across virtually every major vehicle manufacturer worldwide. Modern automotive manufacturing facilities continue to rely heavily on highly automated welding cells capable of executing thousands of precise welds per vehicle at production line speeds that would be impossible to achieve through manual welding alone, and these automated systems continue to demand precisely formulated, consistent shielding gas mixtures to maintain the weld quality and repeatability that automotive safety and durability standards require. The continued global scale of vehicle production, spanning both established manufacturing hubs and rapidly expanding production capacity across emerging automotive markets, continues to sustain automotive and transportation's position as the largest end-use industry for welding gas consumption worldwide.
Aerospace and defense represents the fastest-growing end-use industry, driven by precision aerospace programs increasingly turning to ultra-high-purity supply chains demanding exceptionally pure argon for critical titanium and nickel alloy joints used throughout airframe and engine component manufacturing. Aerospace welding applications typically demand substantially more stringent gas purity specifications than general industrial fabrication, given the safety-critical nature of aerospace structural and propulsion components and the metallurgical sensitivity of the titanium and nickel superalloys commonly used throughout modern aircraft and engine manufacturing. As global aerospace production continues expanding to meet sustained commercial aircraft demand alongside accelerating defense procurement activity worldwide, sustained investment in ultra-high-purity gas supply chains specifically tailored to aerospace welding requirements continues to drive above-market growth for this increasingly demanding and value-dense end-use industry segment.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
42.60% |
|
North America |
United States |
84.60% |
|
Europe |
Germany |
29.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Asia Pacific Welding Gas/Shielding Gas Market Insights
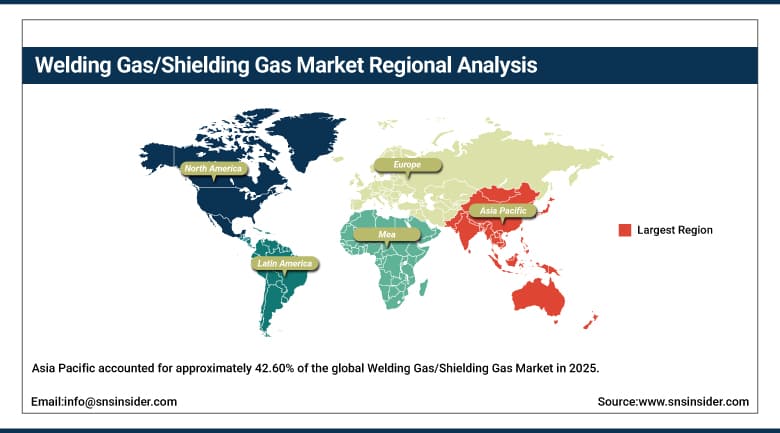
Asia Pacific accounted for approximately 42.60% of the global Welding Gas/Shielding Gas Market in 2025, making it the largest regional market, driven by rapid industrialization, strong expansion in automotive manufacturing, large-scale infrastructure development, and growing metal fabrication activities across China, India, Japan, South Korea, and Southeast Asia. China operates an extensive and continuously expanding network of high-speed rail infrastructure, while India continues making significant investments in transportation and industrial infrastructure, both of which continue driving sustained welding gas orders across the region's steel fabrication and construction sectors. In South Korea, liquefied natural gas shipyards continue utilizing high-purity argon-hydrogen blends for nickel storage tank fabrication, while the automotive and electronics manufacturing sectors across the broader Association of Southeast Asian Nations region continue boosting demand for welding gas cylinders and bulk supply arrangements.
Regional producers of gases are continuously working towards increasing production capacity within the region in order to decrease delivery time and dependence on uncertain international imports, with many major Asian manufacturers of industrial gases acquiring regional air separation unit operators in order to increase their domestic production capacity. The intense welding activities related to the development of massive domestic pipelines and steel fabrications in China, along with major projects in terms of both domestic and international pipelines, have contributed to increasing welding intensity in the region, ensuring that Asia Pacific maintains its leadership in the worldwide welding gas industry. With all these factors, coupled with North America's faster percentage growth rate, Asia Pacific is expected to continue dominating the regional market throughout the forecast period.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Welding Gas/Shielding Gas Market Insights
North America is projected to register the fastest growth rate among all global regions, driven by rising adoption of automated welding systems, expansion in aerospace and defense manufacturing, modernization of energy infrastructure, and strong growth in construction and industrial fabrication activity across the United States specifically. The region's substantial pipeline of infrastructure investment targeting aging bridges, expanding pipeline networks, and rapidly growing renewable energy tower construction continues to generate sustained demand for welding gas across a diverse range of structural steel and specialized fabrication applications. Domestic industrial gas producers continue investing substantially in new air separation unit capacity strategically positioned near major manufacturing hubs, a trend exemplified by recently announced facility investments designed to position production capacity closer to key regional customer bases across the automotive, metals, and general manufacturing sectors.
Canada and Mexico contribute additional regional demand as their own automotive manufacturing and broader industrial fabrication sectors continue to expand, with Mexico in particular benefiting from continued nearshoring-driven manufacturing investment that continues to draw automotive and general industrial production capacity into the region. Continued domestic investment in eco-friendly shielding gas solutions and smart welding technology integrating artificial intelligence with gas shielding systems is expected to sustain North America's fastest-growing regional status through the forecast period, as the region's mature but continuously modernizing industrial base pursues both productivity improvements and environmental sustainability objectives simultaneously.
Europe Welding Gas/Shielding Gas Market Insights
Europe is a significant market for welding gases and shielding gases, where the laws are very strict, and there is a lot of emphasis on quality in all aspects of welding in the automotive, aerospace, and general manufacturing industries in Europe. The use of automated technology for welding has continued to contribute to the increased demand for shielding gases in Europe as European companies have continued to automate their manufacturing lines so that they can compete with cheaper manufacturing regions.
Germany's substantial automotive and industrial manufacturing base continues to anchor regional demand, while France, Italy, and other major European manufacturing markets contribute steady demand growth as regional fabrication and construction sectors continue extending advanced welding gas adoption across their production operations. Regional gas producers, including several of the world's largest industrial gas companies headquartered within Europe, continue investing in expanded production capacity and specialized gas formulation development to serve the region's demanding aerospace, automotive, and precision manufacturing customer base.
MEA & Latin America Welding Gas/Shielding Gas Market Insights
The Middle East & Africa market is supported by sustained construction and energy sector investment across the United Arab Emirates and Saudi Arabia, where large-scale infrastructure and industrial development projects continue to drive demand for welding gas across pipeline construction, structural steel fabrication, and general industrial manufacturing applications. Regional governments continue investing heavily in economic diversification initiatives that include substantial industrial and manufacturing capacity development, sustaining gradual welding gas market growth across the broader Gulf region.
Latin America's market is led by Brazil, where a substantial domestic automotive and general manufacturing sector sustains steady demand for welding gas across a range of industrial applications. Mexico is contributing significant incremental growth as regional automotive and broader manufacturing capacity continues to expand alongside sustained nearshoring-driven industrial investment, with adoption across the broader region remaining concentrated among larger manufacturers and fabrication operations serving both domestic and export-oriented production.
Market Dynamics
Growth Drivers: Industrial Growth and Infrastructure Development
Industrial growth represents the primary driver of Welding Gas/Shielding Gas Market growth, as The growth in industrialization is seen to be the main growth driver in the Welding Gas/Shielding Gas Market since there will always be a need for the provision of quality and reliable welding gas in light of constant infrastructure developments, globalization of manufacturing industries, and increasing need from the automotive industry. The magnitude of global steel fabrication and metal manufacturing operations such as automotive assembly, structural construction, shipbuilding, and general industrial fabrication results in constant demand for shielding gas which increases in line with industrial manufacturing trends across the existing and emerging manufacturing economies.
Construction activities are the second growth drivers since economic growth in emerging economies leads to large construction activities that require considerable amount of structural steel welding. The stringent regulations on quality of welds and their integrity contribute to demand for quality welding gas. The growth in renewable energy projects around the world such as wind turbine towers and solar structures continues to provide considerable and rapidly rising demand for welding gas compared to ten years back.
Restraints: Raw Material Price Volatility and Transportation Cost Sensitivity
Raw material price volatility represents a meaningful restraint on market growth, as the production of industrial gases including argon, which is extracted as a byproduct of large-scale air separation processes, remains genuinely sensitive to broader energy price fluctuations and air separation unit capacity utilization rates across the global industrial gas production base. These cost pressures can complicate long-term pricing agreements between gas producers and their welding and fabrication customers, particularly during periods of elevated energy costs that directly increase the electricity-intensive air separation production process.
Transportation cost sensitivity represents a further restraint, as welding gas, whether delivered in compressed cylinders or as bulk liquid, continues to carry meaningful logistics costs that can represent a substantial portion of total delivered gas cost, particularly for customers located at greater distances from regional air separation production facilities. This transportation cost sensitivity continues to reinforce the strategic value of regionally distributed production capacity, as gas producers that can position new air separation units closer to major customer concentrations are able to meaningfully reduce delivered gas costs relative to competitors relying on longer-distance transportation networks.
Opportunities: Eco-Friendly Gas Formulations and Smart Welding Integration
Continued development of eco-friendly shielding gas solutions represents a substantial opportunity, as manufacturers that can deliver genuinely lower-emission gas formulations and production processes are positioned to capture demand from customers increasingly scrutinizing the environmental footprint of their broader manufacturing supply chain. Growing customer attention to eco-friendly shielding solutions continues to create meaningful differentiation opportunities for gas producers willing to invest in more sustainable production methods and gas formulation innovation.
The continued integration of smart welding solutions, combining artificial intelligence with gas shielding technologies, offers a further substantial avenue for growth, as manufacturers increasingly seek intelligent systems capable of automatically optimizing gas mixture and flow rate in real time based on specific welding parameters and detected joint conditions. Gas producers and equipment manufacturers that can successfully develop and commercialize these intelligent, adaptive gas delivery systems are well positioned to capture demand from increasingly automated manufacturing environments seeking to simultaneously improve weld quality, reduce gas consumption waste, and lower overall production costs across their welding operations.
Recent Developments:
-
In July 2026, Ador Welding signed a strategic MoU with Liburdi Dimetrics to accelerate automation-led welding solutions in India, combining advanced welding technologies with automated inspection and process capabilities for industrial applications.
-
In June 2026, INOX India (INOXCVA) partnered with ITM SLS Baroda University to establish a Centre of Excellence focused on orbital welding and process-piping skills. The initiative supports semiconductor manufacturing infrastructure, including ultra-high-purity gas distribution systems and advanced welding applications.
-
In April 2026, Airgas expanded its U.S. packaged-gas and welding distribution network by acquiring a welding store and related operations serving industrial and agricultural customers in Northern California. The move strengthens Airgas' localized supply capabilities for industrial and welding gases.
Welding Gas/Shielding Gas Market Key Players
-
Air Liquide S.A.
-
Linde plc
-
Air Products and Chemicals, Inc.
-
Taiyo Nippon Sanso Corporation
-
Messer Group GmbH
-
Iwatani Corporation
-
Gulf Cryo
-
Iceblick Ltd.
-
SOL Group
-
Universal Industrial Gases, Inc.
-
BOC Limited (Linde)
-
Coregas Pty Ltd.
-
Matheson Tri-Gas, Inc.
-
Airgas, Inc. (Air Liquide)
-
Southern Industrial Gas Sdn. Bhd.
-
Advanced Specialty Gases
-
Nippon Sanso Holdings Corporation
-
Gulf Coast Welding Supply
-
Weldstar
-
Praxair Technology, Inc.
Welding Gas/Shielding Gas Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.39 Billion |
| Market Size by 2035 | USD 6.85 Billion |
| CAGR | CAGR of 7.29% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Type (Argon, Carbon Dioxide, Oxygen, and Hydrogen) • by Welding Process (Gas Metal Arc Welding, Gas Tungsten Arc Welding, and Flux-Cored Arc Welding) • by End-Use Industry (Automotive & Transportation, Construction, Metal Manufacturing & Fabrication, and Aerospace & Defense) • by Storage Mode (Cylinder & Packaged Gas and Merchant Liquid/Bulk) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Air Liquide S.A., Linde plc, Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, Iwatani Corporation, Gulf Cryo, Iceblick Ltd., SOL Group, Universal Industrial Gases, Inc., BOC Limited (Linde), Coregas Pty Ltd., Matheson Tri-Gas, Inc., Airgas, Inc. (Air Liquide), Southern Industrial Gas Sdn. Bhd., Advanced Specialty Gases, Nippon Sanso Holdings Corporation, Gulf Coast Welding Supply, Weldstar, Praxair Technology, Inc. |
Frequently Asked Questions
Key players include Air Liquide S.A., Linde plc, Air Products and Chemicals, Inc., Taiyo Nippon Sanso Corporation, Messer Group GmbH, and Iwatani Corporation, among other industrial gas producers.
Continued development of eco-friendly shielding gas solutions and continued integration of smart welding solutions combining AI with gas shielding technology represent the primary opportunities.
Growth is primarily driven by industrial growth combined with increased construction activity and sustained automotive industry demand for reliable, high-quality shielding gas supply.
By Type, Argon dominated the market with approximately 44.60% share in 2025, reflecting its inert properties and broad compatibility across both MIG and TIG welding processes.
Asia Pacific dominated the market with approximately 42.60% share in 2025, driven by rapid industrialization and strong expansion in automotive manufacturing across the region.
