
Wind Turbine Operation and Maintenance Market Report Scope & Overview:
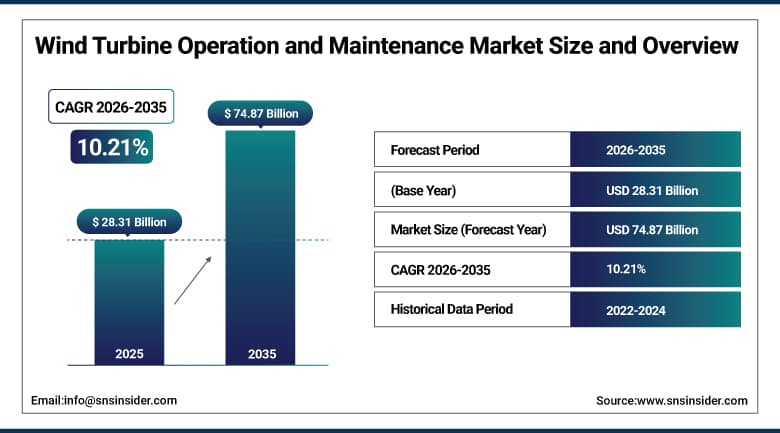
The Wind Turbine Operation and Maintenance Market was valued at USD 28.31 Billion in 2025 and is expected to reach USD 74.87 Billion by 2035, growing at a CAGR of 10.21% from 2026-2035.
Wind Turbine Operation and Maintenance Market growth will be mainly attributed to the enormous development of offshore wind farms, the adoption of predictive maintenance solutions, and increasing installed wind capacity together with aging turbine fleets that require more frequent maintenance activities. The services offered in the field of wind turbine operation and maintenance aim at reducing downtime and failure rate of turbines since generators, electrical systems, sensors, gearboxes, and control systems in wind turbines can still fail due to their complex mechanisms, and unexpected machine failure leads to downtime and loss of electricity generation. Environmental targets and regulations adopted by regions will continue to drive the market toward long-term asset management strategies, especially because operators are now using the most sophisticated diagnostics and performance information to manage the entire life cycle of turbines and to prevent expensive breakdowns. With aging wind energy assets and new wind energy assets appearing in off-site locations, demand for efficient planning, asset management, and prediction solutions will only increase.
In February 2026, Vestas Wind Systems secured an order in the United Kingdom covering the supply, delivery, and commissioning of 92 V236-15.0 MW turbines, along with a five-year service agreement and long-term operational support. The order reflects the continued bundling of turbine supply with extended service commitments as wind farm developers increasingly seek comprehensive, long-duration maintenance partnerships that provide predictable operational performance and cost certainty throughout a project's operational life, reinforcing the competitive importance of integrated turbine-and-service offerings as original equipment manufacturers compete for both new installation and long-term service revenue.
To Get More Information On Wind Turbine Operation and Maintenance Market - Request Free Sample Report
Wind Turbine Operation and Maintenance Market Trends
-
Rising adoption of predictive maintenance software solutions leveraging AI and advanced diagnostics to reduce unplanned downtime.
-
Growing expansion of remote monitoring services supporting increasingly remote and difficult-to-access offshore turbine installations.
-
Expanding repowering activity as aging onshore turbine fleets are upgraded with larger, more efficient replacement technology.
-
Increasing competition from independent service providers challenging traditional OEM-dominated service agreement relationships.
-
Rising implementation of advanced training programs for maintenance personnel addressing industry-wide technical skill shortages.
-
Growing bundling of long-term service agreements with new turbine supply orders to secure predictable, multi-year revenue.
U.S. Wind Turbine Operation and Maintenance Market Outlook
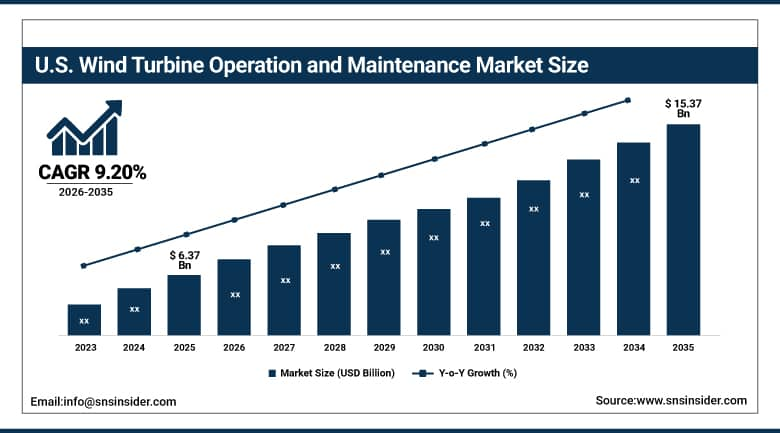
The U.S. Wind Turbine Operation and Maintenance Market was valued at USD 6.37 Billion in 2025 and is expected to reach USD 15.37 Billion by 2035, growing at a CAGR of 9.20% from 2026-2035.
The U.S. Wind Turbine Operation and Maintenance Market growth continues to be reinforced by the country's substantial installed onshore wind fleet and growing emphasis on repowering and large-scale onshore project life extension as early-generation turbines approach the end of their original design life. The country's wind turbine installed base continues to require increasingly sophisticated maintenance capability, as major original equipment manufacturers maintain long-term flexible service agreements with over eight years of average remaining contract term, including continuous wind asset monitoring and diagnostics services delivered from customer support and remote operations centers. Rising domestic focus on OEM service agreements and digital maintenance technology continues to reinforce demand for predictive, data-driven maintenance approaches across the country's aging turbine fleet. Growth is further supported by continued investment in performance improvement programs across existing installed capacity.
GE Vernova invested more than USD 100 million to improve performance across its approximately 57,000 wind turbine installed base, while continuing to lead U.S. onshore wind turbine installations for the fifth consecutive year according to the American Clean Power Association, with a global installed base exceeding 55,000 wind turbines. The company's long-term flexible service agreements include continuous wind asset monitoring and diagnostics services, alongside upgrades and refurbishment offerings for turbine life extension and improved performance, illustrating how established domestic original equipment manufacturers continue to invest in both installed base performance improvement and comprehensive service agreement portfolios supporting the country's substantial and aging onshore wind fleet.
Wind Turbine Operation and Maintenance Market Segment Analysis
-
By Installation Type, the Onshore segment dominated the Wind Turbine Operation and Maintenance Market with approximately 85.60% share in 2025, while the Offshore segment is the fastest growing with a CAGR of approximately 13.20%.
-
By Service Type, the Unscheduled/Corrective segment dominated the Wind Turbine Operation and Maintenance Market with approximately 44.60% share in 2025, while the Predictive segment is the fastest growing with a CAGR of approximately 13.60%.
-
By Component, the Maintenance segment dominated the Wind Turbine Operation and Maintenance Market with approximately 46.60% share in 2025, while the Monitoring & Inspection segment is the fastest growing with a CAGR of approximately 12.40%.
-
By Provider Type, the OEM segment dominated the Wind Turbine Operation and Maintenance Market with approximately 58.60% share in 2025, while the Independent Service Provider segment is the fastest growing with a CAGR of approximately 12.80%.
By Installation Type, Onshore Dominates the Wind Turbine Operation and Maintenance Market and Offshore Grows Fastest
Onshore installations make up the largest share of the market due to the majority of installed capacity of wind power all around the world, owing to onshore wind farms having lower cost of installation, easier access to the installation site and longer history of installation in comparison to offshore farms. Onshore wind farms have been striving towards digitalization in order to lower the cost of maintenance and increase the reliability, as the advanced diagnostics and performance data are being utilized for optimization of turbine life cycle in ever aging installed park. The large size of global onshore wind farm fleet and ongoing onshore installations in both mature and emerging wind markets keep onshore as the largest type of installation segment.
Offshore installations are the fastest-growing installation type as the vast expansion of offshore wind farms continues to drive demand for specialized maintenance capability suited to challenging marine operating environments. The offshore sector faces numerous challenges due to remote locations in the sea, with lower accessibility for repair and maintenance and high installation costs, impacting segmental growth while simultaneously creating premium pricing opportunities for service providers capable of reliably servicing these challenging installations. This growth is reinforced by continued offshore wind capacity additions across Europe and increasingly Asia Pacific, requiring specialized vessels, remote monitoring technology, and trained personnel capable of safely conducting maintenance operations in demanding offshore conditions.
By Service Type, Unscheduled/Corrective Dominates the Wind Turbine Operation and Maintenance Market and Predictive Grows Fastest
Unscheduled and corrective maintenance dominates the market, influenced by the urgent need to respond to unexpected component failures, as the unscheduled maintenance segment continues to require emergency repairs and equipment failure management across the global installed turbine fleet. The aging nature of much of the world's operational wind turbine fleet continues to generate substantial unplanned failure incidents requiring immediate corrective response, sustaining unscheduled and corrective maintenance's position as the largest service type category even as the industry increasingly invests in preventive alternatives intended to reduce future unplanned failure rates.
Predictive maintenance is the fastest-growing service type, reflecting widespread adoption of proactive service models supported by digital platforms that continue to reshape how operators manage their wind turbine fleets. Operators are increasingly using advanced diagnostics and performance data to optimize turbine life cycles and avoid costly breakdowns, with the development of predictive maintenance software solutions continuing to expand across both onshore and offshore installations. This growth is reinforced by the technology's demonstrated ability to reduce unplanned downtime and extend component life, positioning predictive maintenance as an increasingly essential capability as wind farm operators pursue improved reliability and reduced total cost of ownership.
By Component, Maintenance Dominates the Wind Turbine Operation and Maintenance Market and Monitoring & Inspection Grows Fastest
Maintenance holds the largest market revenue share, driven by the growing need for component repairs, inspections, and life-extension services as global turbine installations continue to expand and the existing fleet continues to age. The breadth of maintenance activity required across gearboxes, generators, blades, and control systems continues to sustain maintenance's position as the largest component category, as operation and maintenance service providers continue to expand capacity to address both routine servicing and increasingly frequent life-extension work across an aging global turbine fleet.
Monitoring and inspection services are the fastest-growing component category as expansion of remote monitoring services for offshore turbines continues to extend digital oversight capability into increasingly remote and difficult-to-access installations. This growth is reinforced by rising adoption of continuous wind asset monitoring and diagnostics services delivered from centralized customer support and remote operations centers, which continue to enable operators to identify potential issues before they escalate into costly unplanned failures, extending monitoring and inspection's role well beyond periodic physical inspection into continuous, data-driven asset oversight.
By Provider Type, OEM Dominates the Wind Turbine Operation and Maintenance Market and Independent Service Provider Grows Fastest
Original equipment manufacturers dominate a large portion of the operation and maintenance market through long-term service agreements tied to their own machines, with many OEMs covering 30 to 40 percent of a turbine's operational life under warranty or service contract while offering integrated spare-parts and data-monitoring capability built directly into their service offerings. OEM-provided servicing continues to be attractive because of component familiarity and manufacturer-specific technical expertise, sustaining original equipment manufacturers' position as the largest provider type category across the global installed turbine fleet.
Independent service providers are the fastest-growing provider type as competition from third-party providers continues to increase, offering wind farm operators an alternative to OEM-provided servicing, particularly for turbines that have moved beyond their original warranty or service contract period. This growth is reinforced by independent providers' typically more competitive pricing and flexibility across multi-vendor turbine fleets, positioning independent service providers to capture growing share as the global installed turbine fleet continues to age beyond original OEM service agreement terms and operators increasingly seek cost-competitive alternative servicing options.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Europe |
Germany |
29.60% |
|
North America |
United States |
84.60% |
|
Asia Pacific |
China |
39.60% |
|
Latin America |
Brazil |
27.60% |
|
Middle East & Africa |
United Arab Emirates |
24.60% |
Europe Wind Turbine Operation and Maintenance Market Insights
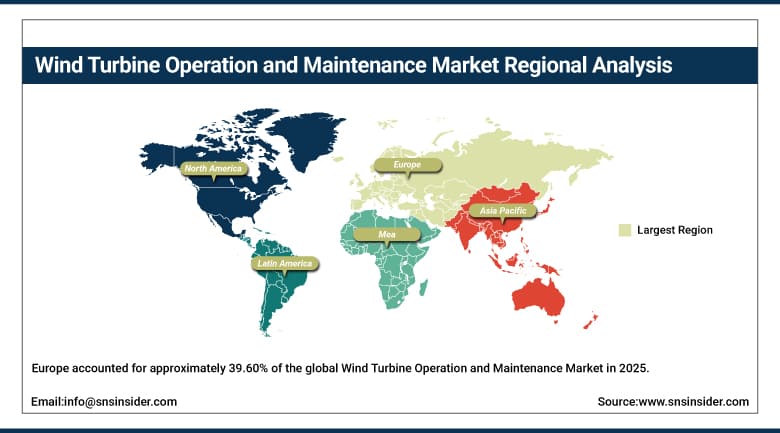
Europe accounted for approximately 39.60% of the global Wind Turbine Operation and Maintenance Market in 2025, making it the largest regional market, owing to increasing offshore and onshore installation activity across the region. Europe's leading position continues to be driven by federal and state policies, incentives, and regulatory support encouraging renewable energy adoption, with the region hosting the world's most mature offshore wind installation base requiring specialized maintenance capability suited to challenging North Sea and Baltic Sea operating conditions.
Germany continues to anchor regional demand given its substantial onshore and offshore installed capacity and strong domestic original equipment manufacturer presence, while Spain, the United Kingdom, and Nordic countries contribute additional scale through expanding offshore project pipelines and repowering activity. Continued offshore repowering activity and operational expansion, supported by established service providers' strong regional service base, is expected to sustain Europe's leading position through the forecast period as the region continues to expand both new installation and life-extension activity across its mature wind fleet.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Wind Turbine Operation and Maintenance Market Insights
The Maintenance Market is primarily defined by the installed wind power capacity in the U.S. along with increasing efforts to repower and extend life cycles of large onshore projects. The high level of installed capacity within the region, coupled with increased domestic attention toward OEM maintenance contracts and digitized maintenance solutions, will keep reinforcing the need for data-based maintenance solutions.
Canada is contributing incremental regional demand as its onshore wind installed base continues to require ongoing servicing and life-extension investment. Continued domestic investment in repowering and predictive maintenance adoption, combined with established original equipment manufacturers' substantial service agreement backlogs, is expected to sustain steady regional growth through the forecast period even as growth in percentage terms moderates relative to faster-expanding emerging markets.
Asia Pacific Wind Turbine Operation and Maintenance Market Insights
Asia-Pacific region is one of the fastest-growing regional markets with a compound annual growth rate of about 13.40% for the period between 2026 and 2035 due to the fast growth of wind power capacity, development of offshore wind projects, and investments in advanced maintenance technology in this region. India is forecasted to have the highest compound annual growth rate in the wind turbine operations and maintenance market.
China's large domestic onshore wind installed base, continuing to hold dominance in inland wind operations, continues to anchor regional demand alongside rapidly expanding domestic offshore wind capacity. Japan and South Korea contribute additional scale through growing offshore wind project pipelines, while Southeast Asian markets are contributing incremental growth as regional wind capacity additions continue to accelerate, reinforcing Asia Pacific's position as the fastest-growing market through the forecast period.
MEA & Latin America Wind Turbine Operation and Maintenance Market Insights
The Middle East & Africa market remains comparatively small but is expanding as growing renewable energy diversification investment across the United Arab Emirates and Saudi Arabia sustains gradual interest in wind capacity development and associated maintenance services. Regional wind capacity remains limited relative to other renewable energy sources, though government-backed diversification initiatives continue to support gradual project development across parts of the broader region.
Latin America's market is led by Brazil, where a substantial domestic onshore wind installed base sustains steady operation and maintenance demand across the country's wind-rich northeastern regions. Mexico and other regional markets are contributing growth as domestic wind capacity additions continue to expand. Across the region, adoption remains concentrated among larger wind farm developers and utilities with established onshore wind project portfolios.
Market Dynamics
Growth Drivers: Offshore Wind Expansion and Predictive Maintenance Technology Adoption
The vast expansion of offshore wind farms represents the primary driver of Wind Turbine Operation and Maintenance Market growth, as offshore installations continue to require specialized, higher-value maintenance capability suited to challenging marine operating environments relative to established onshore servicing approaches. Rising global offshore wind capacity additions, particularly across Europe and increasingly Asia Pacific, continue to expand the addressable market for offshore-specialized maintenance vessels, remote monitoring technology, and trained personnel capable of safely servicing these increasingly numerous and geographically dispersed installations.
The introduction of predictive maintenance technologies represents a second major growth driver, as increasing installed wind capacity and an aging turbine fleet continue to elevate demand for smart scheduling, asset tracking, and predictive insights capable of reducing unplanned downtime and extending component life. The implementation of environmental targets and policy mandates across regions continues to compel operators toward longer-term asset management solutions, reinforcing sustained investment in advanced diagnostics and digital maintenance platforms across both established and emerging wind markets worldwide.
Restraints: High Maintenance Costs and Technical Skill Shortages
The high cost of maintenance is a significant restraint in the growth of the industry due to the fact that offshore maintenance requires a specialized vessel and equipment that will always attract higher prices than onshore servicing; therefore, it takes time to achieve full coverage of all the installations, especially the increasingly difficult-to-access ones. High cost remains an important factor in the choice of maintenance intervals and providers of service regardless of the type of installation.
Lack of skilled workers is another restraint because the wind energy industry continues to experience problems recruiting and retaining qualified technicians who are able to service increasingly advanced turbines in both onshore and offshore installations. It is especially problematic to hire technicians for offshore maintenance as it requires specialized marine safety training; therefore, additional efforts need to be made to train maintenance staff.
Opportunities: Repowering Activity Expansion and Third-Party Service Provider Growth
Continued expansion of repowering activity represents a substantial opportunity, as aging wind farm fleets and the quick increase in installed wind energy capacity continue to drive demand for turbine upgrades and life-extension services across markets with substantial early-generation installed capacity approaching the end of original design life. Service providers that can offer comprehensive repowering capability, combining component replacement with performance optimization, are positioned to capture demand from operators seeking to extend asset life and improve output from existing wind farm sites.
The continued growth of independent, third-party service providers offers a further avenue for growth, as competition from non-OEM providers continues to increase, offering wind farm operators cost-competitive alternatives particularly for turbines that have moved beyond original warranty or service contract terms. Independent providers that can develop multi-vendor technical expertise and competitive pricing are well positioned to capture demand from operators seeking alternatives to OEM-provided servicing as the global installed turbine fleet continues to age beyond original service agreement terms.
Recent Developments:
-
Vestas Wind Systems secured a repowering order from Naturgy in Spain, extending the operational life and output of existing wind farm sites through turbine upgrade and replacement services.
-
Nordex was awarded a repowering order in Lower Saxony, Germany, replacing aging turbines with modern, higher-capacity technology at an existing wind farm site.
-
GE Vernova continued to lead U.S. onshore wind turbine installations for the fifth consecutive year according to the American Clean Power Association, maintaining a global installed base exceeding 55,000 wind turbines.
-
Vestas installed the first V236-15MW turbine offshore at EnBW's He Dreiht project off the coast of Germany, part of a 64-turbine order for the offshore wind farm.
Wind Turbine Operation and Maintenance Market Key Players
-
Vestas Wind Systems A/S
-
Siemens Gamesa Renewable Energy S.A.
-
General Electric Company (GE Vernova)
-
Nordex SE
-
Xinjiang Goldwind Science & Technology Co., Ltd.
-
Envision Energy USA Ltd.
-
Enercon GmbH
-
Ørsted A/S
-
EDF Renewables
-
RWE Renewables GmbH
-
ENGIE SA
-
NextEra Energy Resources, LLC
-
Suzlon Energy Limited
-
Mingyang Smart Energy Group Co., Ltd.
-
Deutsche Windtechnik AG
-
Bachmann electronic GmbH
-
Rope Partner, Inc.
-
PowerPlan, Inc.
-
Natural Power Consultants Limited
-
Iberdrola, S.A.
Wind Turbine Operation and Maintenance Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 31.20 Billion |
| Market Size by 2035 | USD 74.87 Billion |
| CAGR | CAGR of 10.21% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Installation Type (Onshore, Offshore) • By Service Type (Scheduled/Preventive, Unscheduled/Corrective, Predictive) • By Component (Maintenance, Monitoring & Inspection, Repowering/Life Extension) • By Provider Type (OEM, Independent Service Provider) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy S.A., General Electric Company (GE Vernova), Nordex SE, Xinjiang Goldwind Science & Technology Co., Ltd., Envision Energy USA Ltd., Enercon GmbH, Ørsted A/S, EDF Renewables, RWE Renewables GmbH, ENGIE SA, NextEra Energy Resources, LLC, Suzlon Energy Limited, Mingyang Smart Energy Group Co., Ltd., Deutsche Windtechnik AG, Bachmann electronic GmbH, Rope Partner, Inc., PowerPlan, Inc., Natural Power Consultants Limited, Iberdrola, S.A. |

Frequently Asked Questions
Key players include Vestas Wind Systems A/S, Siemens Gamesa Renewable Energy S.A., GE Vernova, Nordex SE, Xinjiang Goldwind Science & Technology Co., Ltd., Ørsted A/S, and EDF Renewables, among other wind turbine manufacturers and service providers.
Continued expansion of repowering activity across aging wind farm fleets and continued growth of independent, third-party service providers represent the primary opportunities.
Growth is primarily driven by the vast expansion of offshore wind farms combined with the introduction of predictive maintenance technologies addressing an aging global turbine fleet.
By Installation Type, Onshore dominated the market with approximately 85.60% share in 2025, reflecting the vast majority of global installed wind capacity and lower relative servicing costs.
Europe dominated the market with approximately 39.60% share in 2025, driven by increasing offshore and onshore installation activity and strong regulatory support for renewable energy.
