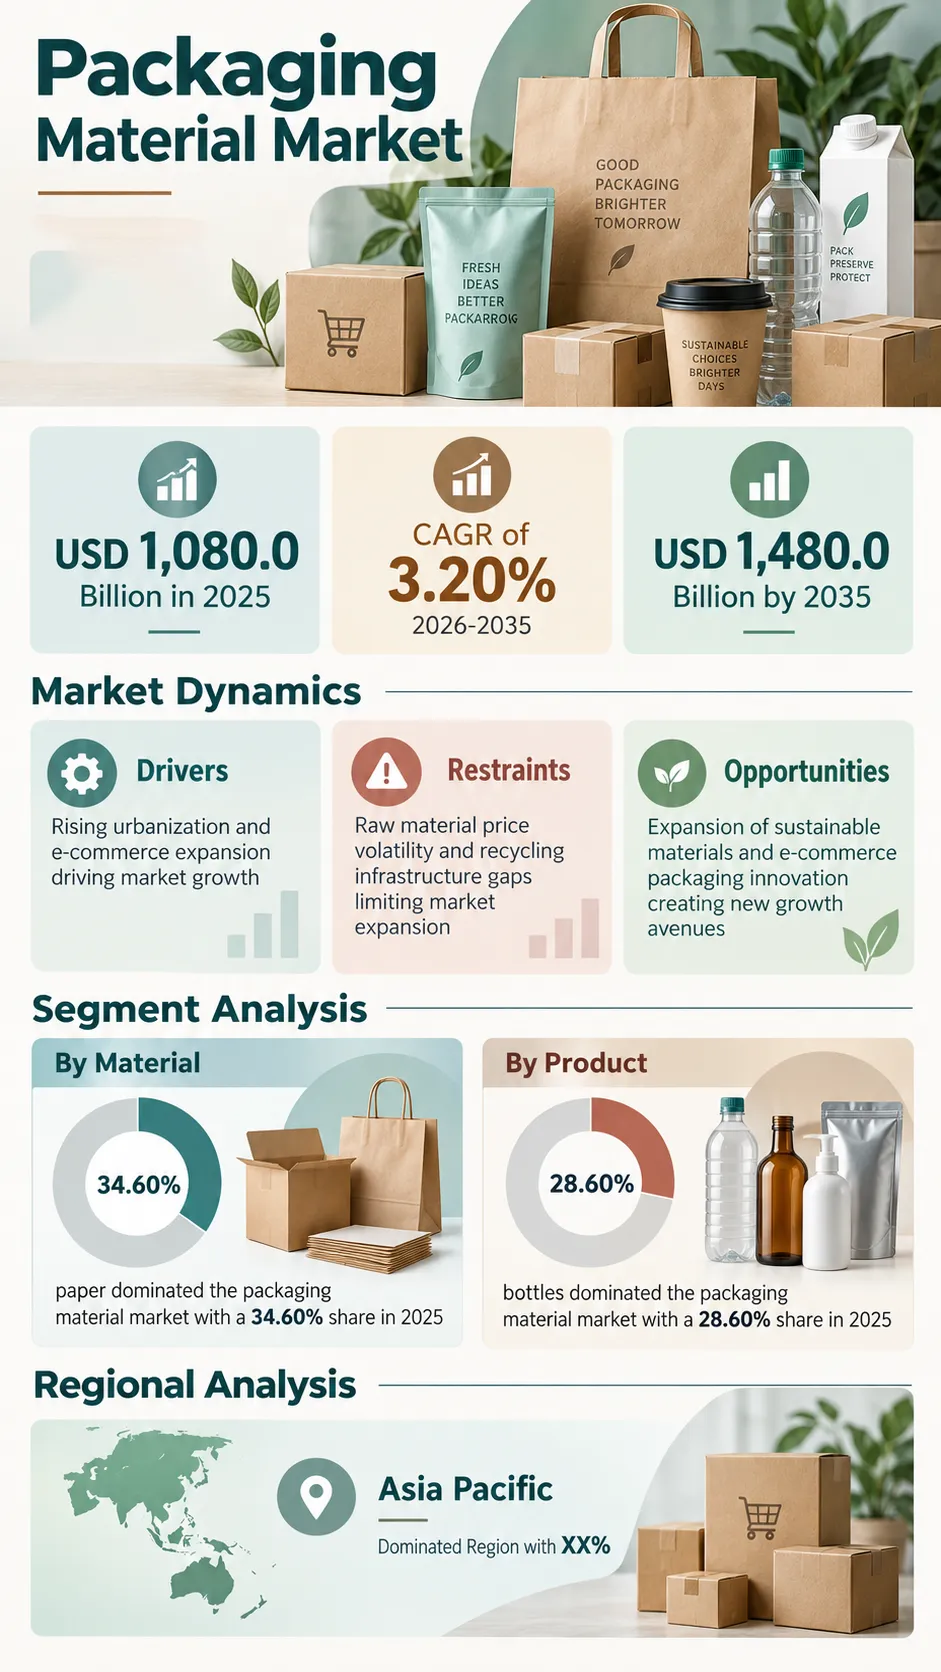
The global Packaging Material Market is set for significant expansion as urbanization and e-commerce expansion continue to reshape consumer goods packaging worldwide. “According to a recent study by SNS Insider, the global Packaging Material Market size valued at USD 1,080.0 billion in 2025, is anticipated to grow to USD 1,480.0 billion by 2035, registering a CAGR of 3.20% over the 2026–2035 forecast period.”
There have been notable changes within packaging material technology over time, due to which many manufacturers who aim at improving sustainability and functional performance can take advantage of this trend. This includes the need for more advanced recyclable and biodegradable material techniques that will provide consumer goods brands with the ability to access protective, environmentally responsible packaging. This applies in situations where packaging materials support food and beverage, household products, and e-commerce applications. Manufacturers are constantly working hard to ensure that their packaging materials perform better than before in order to meet various protective performance and sustainability requirements.
To Get Detailed Insights on the Packaging Material Market – Request a Sample Report
Sustainable Materials and E-Commerce Packaging Innovation Create New Demand
The packaging material market has evolved from conventional single-use plastic and paper structures to increasingly sophisticated, sustainable and technology-enhanced packaging solutions. The growing investment in recyclable material development, e-commerce-optimized packaging design, and circular economy integration across manufacturers of all sizes has required the development of more versatile and sustainable packaging products.
New material and design innovations can increase protective performance, improve recyclability, and allow for expansion into increasingly diverse food, beverage, household product, and e-commerce applications. This gives consumer goods brands the possibility to deliver functional, sustainable packaging while meeting growing consumer and regulatory environmental expectations.
Packaging material manufacturers, brand owners, and logistics providers are increasingly cooperating thanks to the growing interest in developing future solutions for sustainable, e-commerce-optimized packaging materials.
Key Market Findings Highlight High-Growth Segments
The paper material segment dominated all categories in the packaging material market share in 2025 due to established sustainability credentials and broad applicability across boxes and cartons. The fastest growing category is expected to be rigid plastic which will expand at a CAGR of 4.80% in the coming years, owing to growing demand for durable, protective e-commerce packaging.
By product, bottles registered dominance over the global market in 2025 due to broad applicability across beverage and personal care packaging. Boxes will see the fastest growth in the market at a 5.20% CAGR, driven by growing e-commerce and last-mile logistics demand for protective, stackable formats.
Based on end-user, food and beverages dominated the global market in 2025 thanks to packaging materials' essential role preserving product freshness and food safety. On the other hand, household products will be the segment recording the highest market share growth at a 5.60% CAGR, supported by growing demand for durable consumer goods packaging.
Distributive regional trends are changing as well. Asia Pacific held a majority revenue share, valued at USD 281 billion in 2025, owing to low-cost supplies and rising industrialization. But North America will turn out to be the fastest-growing region through 2035, on the back of innovations in material recycling and reuse.
Protective Performance, Sustainability, and E-Commerce Compatibility Gain Importance
In this regard, consumer goods brands have been looking at packaging materials that would deliver more consistent protective performance while requiring greater sustainability credentials and e-commerce logistics compatibility.
Innovation in recyclable material development, e-commerce-optimized packaging design, and circular economy integration has been making it possible for companies to come up with products that appeal to increasingly sustainability-focused and logistics-conscious brand owners. In addition to that, increasing emphasis on household product-specific packaging is also making it possible for manufacturers to find solutions that address diverse consumer goods protective and functional requirements. Such trends are likely to become even more prominent in the future.
Asia Pacific Emerges as the Largest Market Valued at $281 Billion Amid Rising Industrialization
The Asia Pacific region represented the largest share of regional market revenue in 2025, valued at USD 281 billion, owing to the availability of low-cost supplies and rising urbanization and industrialization in developing countries. On the other hand, North America is expected to grow at the fastest CAGR during the forecast period through 2035, propelled by innovations in material recycling and reuse.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on recyclable materials and e-commerce packaging design as well as forming partnerships in order to enhance their position in the industry. Some of the major companies that operate in the global packaging material market are Amcor, Mondi Group, Berry Global, Smurfit Kappa Group, Ball Corporation, Sealed Air Corporation, International Paper Company, WestRock Company, Sonoco Products Company, and Crown Holdings.
An SNS Insider analyst Himanshu Sharma commented, "The growing convergence of e-commerce expansion and sustainability regulation is creating sustained demand for recyclable, protective packaging materials. Manufacturers that successfully combine recyclable material innovation, e-commerce-optimized design, and circular economy integration will be best positioned to capitalize on emerging opportunities across food, household product, and e-commerce packaging segments."
About the Author
Get in touch