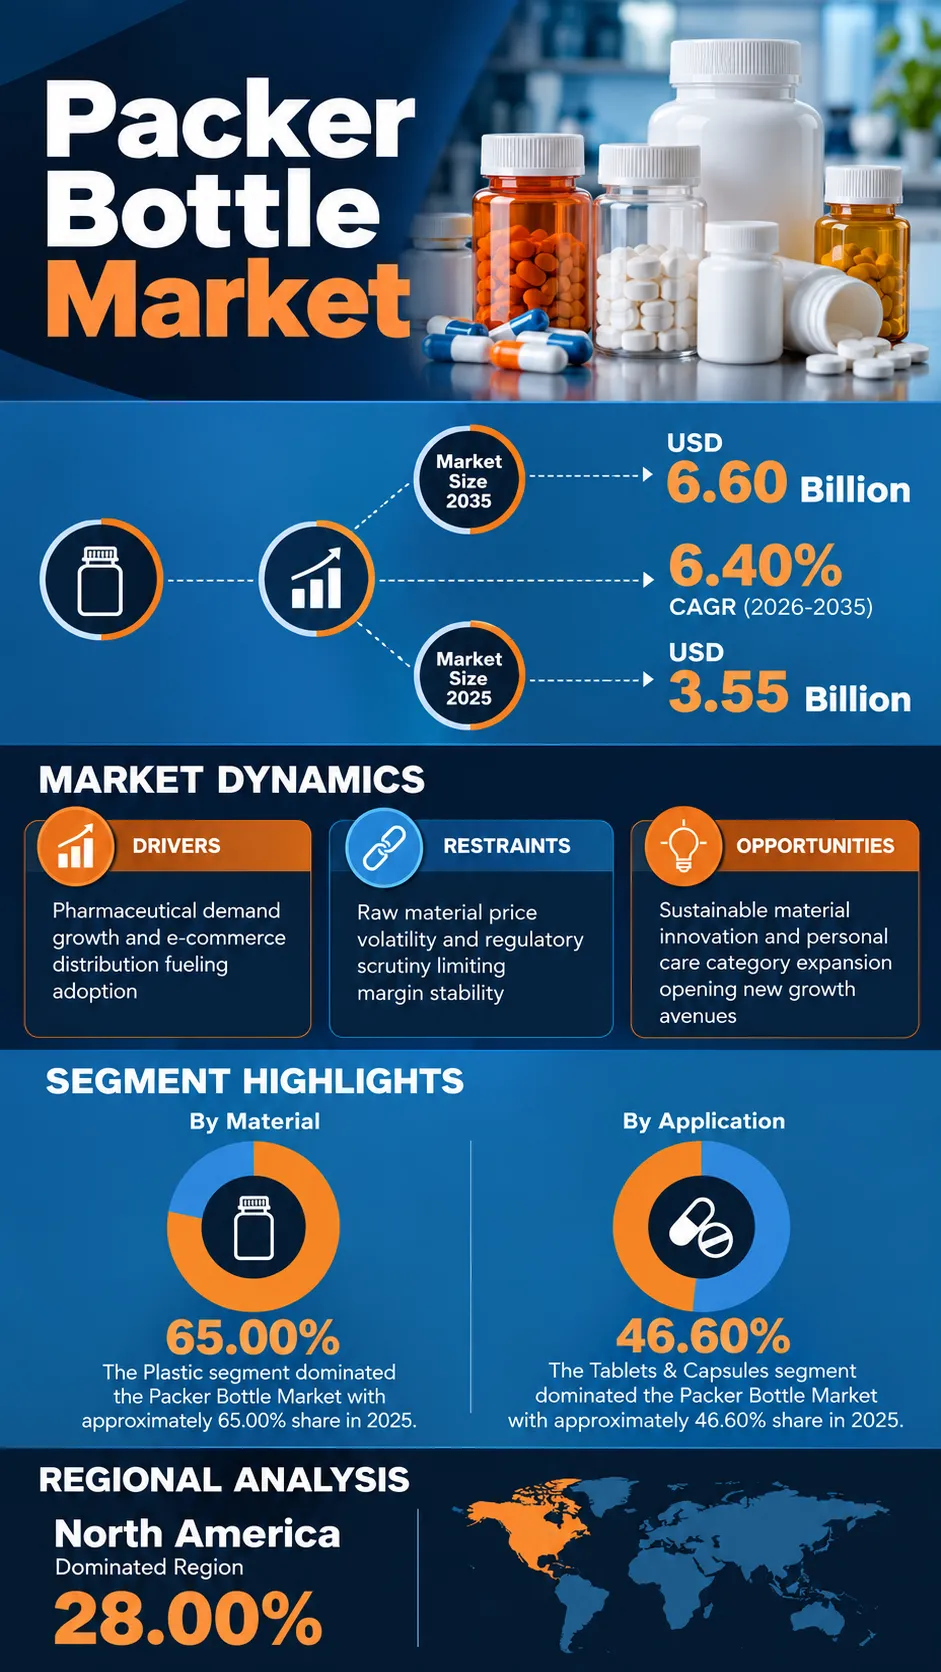
The global Packer Bottle Market continues its steady climb as pharmaceutical, nutraceutical, and personal care brands lean further into recycled, documented-compliance packaging. “According to a recent study by SNS Insider, the global Packer Bottle Market size valued at USD 3.55 billion in 2025, is anticipated to grow to USD 6.60 billion by 2035, registering a CAGR of 6.40% over the 2026-2035 forecast period.”
There have been steady changes within material and closure technology over time, due to which many manufacturers aiming at improved sustainability and regulatory compliance can take advantage of this trend. This includes the need for more recycled-content, certified formulations that give pharmaceutical and nutraceutical buyers confidence in both product protection and environmental compliance, across a wide range of applications from tablet packaging to powdered supplements. This applies in situations where packer bottles are used across pharmaceutical, nutraceutical, and personal care applications.
Manufacturers are constantly working to improve material sustainability and regulatory compliance in order to meet various needs of pharmaceutical and nutraceutical brands worldwide.
To Get Detailed Insights on the Packer Bottle Market – Request a Sample Report
Pharmaceutical Demand and Regulatory Compliance Ecosystems Create New Demand
The packer bottle market has evolved from basic functional plastic container offerings into a broader mix of recycled-content, glass, and branded product lines. The growing investment in post-consumer recycled formulation, certified regulatory compliance, and multi-application development has required the development of more efficient and reliable production systems.
New material and design approaches can improve regulatory compliance, reduce environmental impact, and expand the range of applications packer bottles can serve. This gives manufacturers the possibility to be more effective when reaching pharmaceutical and nutraceutical buyers and strengthening claims around product protection and sustainability.
Bottle manufacturers, pharmaceutical brands, and nutraceutical companies are increasingly cooperating due to the growing interest in developing future solutions for compliant, sustainable solid-dosage packaging.
Key Market Findings Highlight High-Growth Segments
The plastic segment dominated all categories in the packer bottle market share with a market revenue share of approximately 65.00% in 2025 due to its cost-effectiveness, light weight, and manufacturing versatility.
The fastest growing category is expected to be the glass segment, which will grow at a CAGR of approximately 7.40% through 2035. This will be possible owing to growing demand for chemically inert, light-sensitive-product packaging.
By end-user industry, pharmaceuticals & nutraceuticals held the largest share of total market revenue at approximately 54.20% in 2025 due to the critical role packer bottles play in drug delivery and safety. The personal care segment will see the fastest growth in revenue generation at a CAGR of approximately 7.90%.
Regional trends show North America leading in 2025, with the United States alone accounting for approximately 28.00% of global consumption volume, while Asia Pacific is expected to register the fastest growth trajectory through the forecast period.
Regulatory Compliance, Material Sustainability, and Application Diversification Gain Importance
In this regard, manufacturers have been looking at packer bottle products that would comply more fully with regulatory requirements, incorporate more sustainable materials, and serve more diverse applications.
Innovation in post-consumer recycled formulation, certified compliance documentation, and multi-application development has been making it possible for companies to come up with products that can meet increasingly demanding pharmaceutical and regulatory expectations. In addition to that, increasing emphasis on branded, customized design is also making it possible for companies to find solutions that differentiate beyond pure functionality.
Such trends are likely to become even more prominent in the future.
North America Leads Amid Deep Pharmaceutical and Nutraceutical Manufacturing Base
North America led global market revenue in 2025, with the United States alone accounting for approximately 28.00% of global consumption volume, owing to a deep pharmaceutical and nutraceutical manufacturing base spanning prescription drugs, over-the-counter medicines, and dietary supplements. In addition, Asia Pacific is expected to register a fast growth trajectory during the forecast period, propelled by rapidly expanding pharmaceutical and nutraceutical manufacturing capacity across the region's fast-growing economies.
On the other hand, Europe represented a meaningful share of global market revenue in 2025, aided by strong pharmaceutical manufacturing infrastructure and stringent regulatory requirements promoting sustainable packaging.
Leading Companies Drive Innovation and Competition
The environment continues to stay very dynamic since players continue innovating on material and closure technology as well as forming partnerships in order to enhance their position in the industry.
Some of the major companies that operate in the global packer bottle market are Amcor plc, Berry Global Group, Inc., Berlin Packaging, Gerresheimer AG, Alpha Packaging, Inc., Comar, LLC, O.Berk Company, LLC, CL Smith Company, Plastipak Holdings Inc., and Aaron Packaging, Inc.
An SNS Insider Analyst Himanshu Sharma commented, “The steady shift toward recycled-content, certified-compliance packer bottle packaging is creating consistent demand across pharmaceutical, nutraceutical, and personal care applications. Manufacturers that successfully combine sustainable material innovation, regulatory compliance documentation, branded design capability, and reliable pharmaceutical partnerships will be best positioned to capitalize on emerging opportunities across tablets, powders, and liquid applications.”
About the Author
Get in touch