
Agriculture Drone Market Report Scope & Overview:
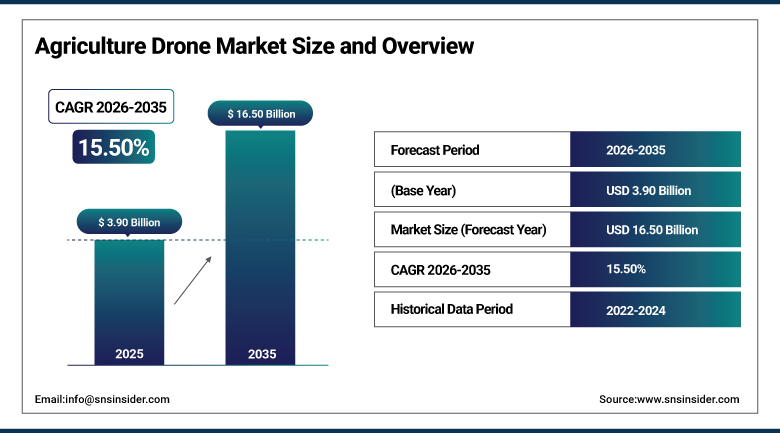
The Agriculture Drone Market was valued at USD 3.90 Billion in 2025 and is expected to reach USD 16.50 Billion by 2035, growing at a CAGR of 15.50% from 2026–2035.
The Agriculture Drone Market is expected to grow at a rapid pace due to increasing usage of precision farming techniques and the need for better agricultural production. Increasing labor cost and shortage of labor are leading farmers to deploy drones in crop surveillance, spraying, mapping, and precision spraying. The rising awareness about the efficient utilization of resources is further driving the usage of drones because of their ability to utilize water, fertilizers, and crop protection chemicals in an efficient manner. Advancements in artificial intelligence, imagery sensors, GPS, and automated flight technology are leading to improvements in efficiency of the drones. Favorable conditions for the agriculture drone market are also created due to government policies related to the growth of smart agriculture and mechanization.
DJI's own industry report found that nearly 400,000 of its agricultural drones were in active use worldwide by the end of 2024, a 90% jump from when the company first published the same study in 2020. That kind of adoption curve, from a niche precision-farming tool to a machine nearly 400,000 farms and operators now rely on, is exactly the scale that's pulling major agrochemical and technology investors into a market that barely existed as a commercial category a decade ago.
To Get more information Agriculture Drone Market - Request Free Sample Report
Agriculture Drone Market Trends:
-
Drone-as-a-Service subscription models continue lowering the barrier to entry for smaller farms, letting operators pay USD 5-15 per acre per season rather than committing USD 10,000-30,000 to hardware ownership.
-
Regulatory approvals for beyond-visual-line-of-sight and swarm drone operations continue expanding, letting operators cover more acreage per flight crew and unlock genuinely large-scale commercial spraying operations.
-
Geopolitical scrutiny of Chinese-manufactured drone hardware is reshaping supply chains, pushing domestic manufacturers in multiple countries to accelerate localized production of agricultural drone components.
-
AI-driven autonomy and multispectral imaging continue advancing rapidly, letting drones make real-time spraying and monitoring decisions rather than simply executing a pre-programmed flight path.
-
Fleet-sharing cooperatives are emerging among small and medium farms, letting several operations split the cost of drone hardware and operator services that would be uneconomical for any single small farm alone.
U.S. Agriculture Drone Market Outlook:
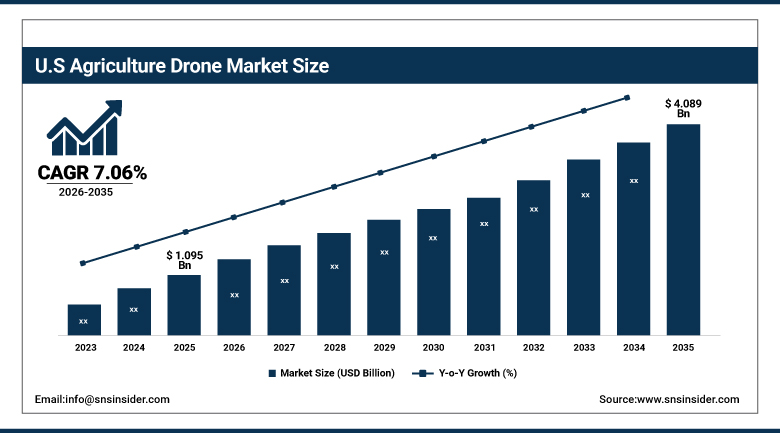
The U.S. Agriculture Drone Market was valued at approximately USD 1.095 Billion in 2025 and is expected to reach approximately USD 4.089 Billion by 2035, growing at a CAGR of approximately 14.65%.
Demand in the United States is driven by a large base of commercial farms adopting precision agriculture technology, alongside a growing network of drone service providers offering pay-per-acre spraying and mapping services to operations too small to justify direct hardware ownership. The domestic market has run almost entirely on imported hardware from Chinese manufacturers, a dependency that's now facing genuine regulatory pressure and prompting American companies to accelerate localized production. Federal Aviation Administration approvals for advanced operations, including beyond-visual-line-of-sight flight and multi-drone swarming, continue expanding what domestic drone service providers can legally offer farmer customers.
The U.S. Federal Communications Commission ruled against foreign drones and critical drone components on December 22, 2025, throwing the American agricultural drone market, which has run almost entirely on Chinese-made DJI and XAG hardware, into genuine uncertainty. Existing DJI and XAG fleets can keep receiving firmware and software updates through at least January 1, 2027, but domestic drone makers are racing to localize production before that window closes, a scramble one American manufacturer described as customers and investors spending most of 2025 in a 'wait and see' holding pattern.
Agriculture Drone Market Segment Analysis:
-
By Product Type, the Rotary-Wing Drones segment dominated the Agriculture Drone Market with approximately 61.70% share in 2025, while the Hybrid VTOL Drones segment is the fastest growing with a CAGR of approximately 20.50%.
-
By Component, the Hardware segment dominated the Agriculture Drone Market with approximately 57.40% share in 2025, while the Services segment is the fastest growing with a CAGR of approximately 19.20%.
-
By Application, the Crop Monitoring & Field Mapping segment dominated the Agriculture Drone Market with approximately 44.00% share in 2025, while the Crop Spraying segment is the fastest growing with a CAGR of approximately 20.00%.
-
By Farm Size, the Large-Scale Commercial Farms segment dominated the Agriculture Drone Market with approximately 59.00% share in 2025, while the Small & Medium Farms segment is the fastest growing with a CAGR of approximately 19.00%.
-
By End User, the Drone Service Providers/Custom Applicators segment dominated the Agriculture Drone Market with approximately 42.60% share in 2025, while the Agribusinesses/Research Institutes/Government Agencies segment is the fastest growing with a CAGR of approximately 16.60%.
By Product Type, rotary-wing dominates, hybrid VTOL grows fastest
Rotary-wing drones held the largest share of the product-type segment in 2025, valued for their maneuverability, precise hovering capability, and ability to operate in tighter field-level spaces than fixed-wing designs allow. Their compatibility with smart farming ecosystems, connecting to soil sensors, weather stations, and irrigation systems as part of a fully integrated automated farming environment, continues reinforcing this dominant position across nearly every commercial agricultural drone application.
Hybrid VTOL drones are growing fastest as operators seek the combined benefits of vertical takeoff and landing flexibility with the extended range and coverage efficiency that fixed-wing flight patterns offer over large field areas. That combination is proving particularly valuable for large-scale commercial farms needing both the precision of rotary-wing operation and the endurance to cover thousands of acres in a single flight session.
By Component, hardware dominates, services grows fastest
Hardware accounted for the largest component share in 2025, covering the airframes, sensors, batteries, cameras, sprayers, and GPS modules that make up the physical drone system farmers and operators actually deploy in the field. The escalating need for advanced hardware components to build and fly increasingly capable UAVs for precision agriculture keeps hardware the largest single component category by revenue.
Services are growing fastest as Drone-as-a-Service subscription models continue reducing upfront capital requirements and transferring operational risk from individual farmers to specialized service providers. Companies offering subscription-based analytics platforms that bundle flight operations, data processing, and agronomic insights for a per-acre fee are making precision agriculture accessible to farms that couldn't otherwise justify direct hardware investment.
By Application, crop monitoring & field mapping dominates, crop spraying grows fastest
Crop monitoring and field mapping held the largest application share in 2025, helping farmers enhance productivity through real-time crop health analysis and precision farming practices that identify problems before they become visible to the naked eye. That foundational role in modern precision agriculture workflows keeps monitoring and mapping the largest and most established application across the broader agriculture drone market.
Crop spraying is the fastest-growing application as regulatory approvals for advanced spraying operations, including multi-drone swarming and beyond-visual-line-of-sight flight, continue expanding what drone-based spraying can legally accomplish. Rising labor costs and shortages across commercial farming operations are reinforcing this above-average growth trajectory as spraying by drone increasingly displaces traditional ground-based and manned aerial application methods.
By Farm Size, large-scale commercial farms dominates, small & medium farms grows fastest
Large-scale commercial farms accounted for the largest farm-size share in 2025, benefiting most from the efficiency and scalability that agriculture drones offer across thousands of acres of continuous cultivation. Their capital resources and operational scale make direct drone hardware ownership economically justified in ways that smaller operations often can't match.
Small and medium farms are the fastest-growing farm-size segment as fleet-sharing cooperatives and Drone-as-a-Service subscription models continue lowering the entry barriers that once kept this technology out of reach for smaller operations. That combination of shared infrastructure and pay-per-acre service pricing is opening precision agriculture to a much broader population of farming operations than direct ownership alone could ever reach.
By End User, drone service providers/custom applicators dominates, agribusinesses/research institutes/government agencies grows fastest
Drone service providers and custom applicators accounted for the largest end-user share in 2025, as farmers, especially smallholders, increasingly prefer outsourced aerial services over capital-intensive hardware ownership. Offering flexible aerial spraying, crop monitoring, and mapping solutions on a pay-per-acre basis, these providers lower adoption barriers and enable cost-effective access to precision agriculture technologies without requiring farmers to develop in-house drone piloting expertise.
Agribusinesses, research institutes, and government agencies are the fastest-growing end-user category as institutional buyers increasingly deploy drone fleets for large-scale agricultural research, extension services, and policy-driven precision agriculture initiatives. Growing government investment in sustainable farming technology and agricultural research infrastructure continues reinforcing this above-average growth trajectory relative to the broader, service-provider-dominated end-user mix.
Regional Analysis:
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
41.20% |
|
North America |
United States |
82.60% |
|
Europe |
Germany |
24.75% |
|
Latin America |
Brazil |
36.40% |
|
Middle East & Africa |
UAE |
28.90% |
North America Agriculture Drone Market Insights
North America is a significant agriculture drone market where the major demand comes from the United States through its vast number of commercial farms and an increasing number of drone service providers. Pressure on the Chinese-made drone hardware through regulation has created uncertainty in the local supply chain, leading to an increased effort in developing local manufacturing capacity by American drone companies.
The demand in Canada is from its own large commercial agriculture market, while that in Mexico is growing in line with its agricultural exports. Technology and service provider linkages have tied a significant part of North American demand together, especially as U.S.-based drone service networks reach into neighboring markets.
Europe Agriculture Drone Market Insights
Europe represents a mature, regulation-conscious agriculture drone market, shaped by evolving aviation authority frameworks that have only recently begun legalizing drone-based spraying and spreading operations across major farming countries. Germany anchors regional demand, home to a large commercial agriculture sector and growing precision farming technology adoption.
The United Kingdom, following its Civil Aviation Authority's landmark authorization of agricultural drone spraying, and France contribute meaningful volume as well, each with substantial commercial farming sectors adapting to newly available drone-based application technology. Growing regional emphasis on sustainable farming practices continues reinforcing demand for precision agriculture drone technology across the region.
Asia Pacific Agriculture Drone Market Insights
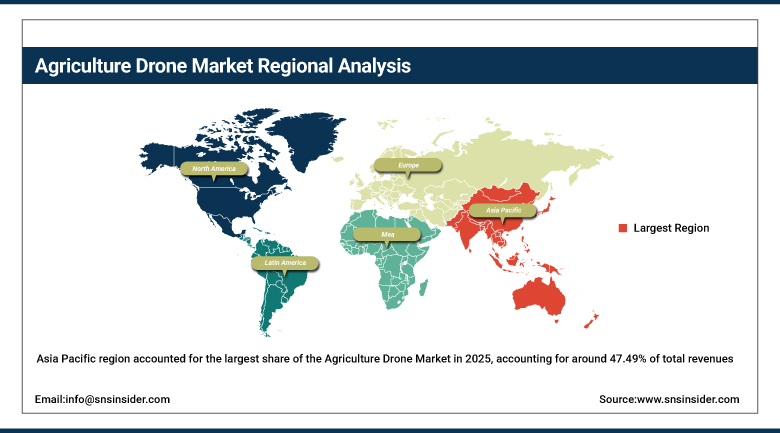
The Asia Pacific region accounted for the largest share of the Agriculture Drone Market in 2025, accounting for around 47.49% of total revenues globally in the market, and is expected to register the highest regional CAGR of about 17.00% between 2025 and 2035. The large domestic manufacturing base of agricultural drones in China, which accounts for some of the biggest drone manufacturers in the world, and its rapidly growing adoption in the country is further strengthening and accelerating this trend.
While the manufacturing capacity in China provides the region with an extensive capacity in terms of production and consumption, the increasing investments in precision rice farming and smart agriculture in India is providing additional impetus to this growth. Japan and South Korea are more matured and technology-oriented markets that already have significant adoption of agricultural drones, whereas the Southeast Asian markets continue to follow a similar pattern driven by smallholder adoption.
Get Customized Report as per Your Business Requirement - Enquiry Now
MEA & Latin America Agriculture Drone Market Insights
The Middle East and Africa represent a smaller but developing agriculture drone market, with the UAE driving demand through government-backed agricultural technology investment tied to broader food security and sustainability initiatives. Growth elsewhere in the region remains tied closely to the pace of broader agricultural mechanization and technology infrastructure development.
Latin America is a growing market led by Brazil, one of the world's largest commercial agriculture exporters, where expanding large-scale farming operations continue driving demand for precision spraying and monitoring drone technology. Argentina and Mexico contribute meaningful secondary demand, tied to their own substantial commercial agriculture sectors.
Market Dynamics:
Growth Drivers: Labor shortages and precision farming demand fueling adoption
Labor shortages and increased costs in commercial farming activities constitute the most evident factor behind the growing number of agriculture drone users since drones provide a real replacement for labor that is currently hard and costly to obtain. The shortage of labor serves as a foundation for market demand that will only be increasing irrespective of short-term changes in commodity prices.
The necessity for sustainable and precise agriculture constitutes the second main factor behind the growing demand since drones provide an opportunity for targeted interventions and decrease agrochemical usage compared to non-targeted ground application systems. The increasing demand for food globally, together with the virtually unchanged availability of arable lands, justifies the development of technologies aimed at improving yield per acre.
Restraints: Regulatory restrictions and hardware supply chain uncertainty limiting adoption speed
Regulatory restrictions on drone operations remain a genuine restraint in many markets, since aviation authorities in numerous countries have only recently begun authorizing agricultural spraying and beyond-visual-line-of-sight operations that make large-scale commercial drone deployment practical. That regulatory catch-up process continues limiting how quickly operators can scale operations even where farmer demand is clearly present.
Hardware supply chain uncertainty adds a further restraint, particularly in markets where geopolitical scrutiny of foreign-manufactured drone components has introduced genuine doubt about long-term hardware availability and software support. That uncertainty has measurably slowed purchasing decisions among both operators and investors waiting to see how regulatory outcomes resolve.
Opportunities: Drone-as-a-Service expansion and localized manufacturing opening new growth avenues
Expanding Drone-as-a-Service business models offer providers a genuine path to capturing recurring subscription revenue from farmers who can't justify direct hardware ownership, transferring both capital burden and operational risk to specialized service providers. Companies that build strong service networks and per-acre pricing models are positioned to capture disproportionate growth as this ownership-alternative continues expanding across smaller farming operations.
Localized hardware manufacturing represents a second significant opportunity, particularly in markets facing regulatory pressure on foreign-manufactured drone components, as domestic manufacturers race to fill the gap left by potential restrictions on established Chinese suppliers. Companies that successfully scale competitive, domestically produced hardware are positioned to capture significant market share as supply chain localization accelerates.
Recent Developments:
-
October 2025: Rantizo received FAA approval to operate up to three drones over 55 pounds simultaneously without a visual observer, including night operations, expanding what the largest U.S. drone spraying network can offer farmer customers.
-
December 2024: XAG released its P150 spray drone, which Rantizo added to its operator network in time for the 2025 spraying season.
-
2025: XAG received operational authorization from the UK Civil Aviation Authority for its P40 and V40 agricultural spraying aircraft, the first legalization of drone spraying and spreading on UK farms.
-
2025: The FAA granted a Part 107 beyond-visual-line-of-sight waiver for drone operations over a large Florida ranch, expanding the scope of precision agriculture data collection permitted under current U.S. drone regulation.
Agriculture Drone Market Key Players:
-
SZ DJI Technology Co., Ltd. (DJI)
-
XAG Co., Ltd.
-
Yamaha Motor Co., Ltd.
-
Parrot SA
-
AgEagle Aerial Systems Inc.
-
Trimble Inc.
-
PrecisionHawk Inc.
-
DroneDeploy Inc.
-
Sentera Inc.
-
AeroVironment, Inc.
-
Autel Robotics
-
Hylio Inc.
-
Delair SAS
-
Wingtra AG
-
EAVISION Technologies Co., Ltd.
-
3D Robotics, Inc.
-
Microdrones GmbH
-
Sky-Drones Technologies Ltd.
-
JOUAV Automation Technology Co., Ltd.
-
Garuda Aerospace Pvt. Ltd.
Agriculture Drone Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.90 Billion |
| Market Size by 2035 | USD 16.50 Billion |
| CAGR | CAGR of 15.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Fixed-Wing Drones, Rotary-Wing Drones, Hybrid VTOL Drones) • By Component (Hardware, Software, Services) • By Application (Crop Monitoring & Field Mapping, Crop Spraying, Variable Rate Application, Livestock Monitoring, Others) • By Farm Size (Large-Scale Commercial Farms, Small & Medium Farms) • By End User (Drone Service Providers/Custom Applicators, Agribusinesses/Research Institutes/Government Agencies, Individual Farmers) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SZ DJI Technology Co., Ltd. (DJI), XAG Co., Ltd., Yamaha Motor Co., Ltd., Parrot SA, AgEagle Aerial Systems Inc., Trimble Inc., PrecisionHawk Inc., DroneDeploy Inc., Sentera Inc., AeroVironment, Inc., Autel Robotics, Hylio Inc., Delair SAS, Wingtra AG, EAVISION Technologies Co., Ltd., 3D Robotics, Inc., Microdrones GmbH, Sky-Drones Technologies Ltd., JOUAV Automation Technology Co., Ltd., Garuda Aerospace Pvt. Ltd. |
Frequently Asked Questions
Key players in the Agriculture Drone Market include SZ DJI Technology Co., Ltd., Parrot Drones SAS, AgEagle Aerial Systems Inc., DroneDeploy, Inc., and PrecisionHawk, Inc., among others.
Key opportunities in the Agriculture Drone Market include expanding Drone-as-a-Service subscription models for smaller farms and localized hardware manufacturing amid regulatory pressure on foreign-made drone components.
The market is driven by rising labor shortages and costs across commercial farming operations, combined with growing need for sustainable, precision farming practices.
The Rotary-Wing Drones segment dominated the Agriculture Drone Market, accounting for approximately 61.70% market share.
The Asia Pacific region dominated the Agriculture Drone Market in 2025 with approximately 47.49% share.
