
Anti-Venom Market Report Scope & Overview:
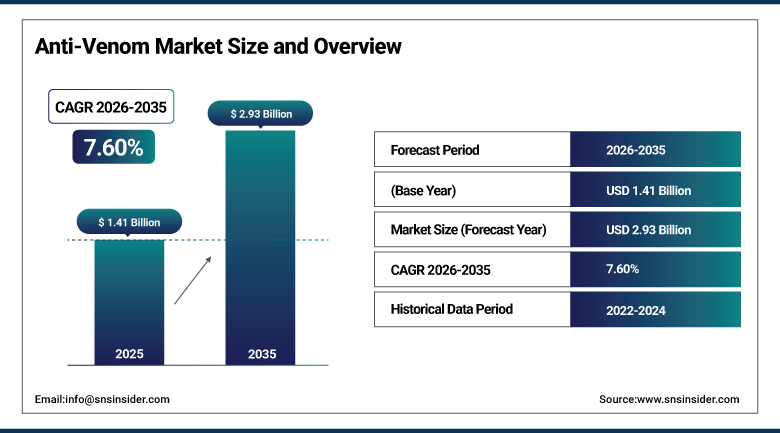
The Anti-Venom Market was valued at USD 1.41 Billion in 2025 and is expected to reach USD 2.93 Billion by 2035, growing at a CAGR of 7.60% from 2026-2035.
The Anti-Venom Market growth is being driven primarily by the increasing number of snake bites and sting from venomous insects, specifically in the tropical and subtropical areas of the world where the WHO suggests that there are 4.5 to 5.4 million snake bites occurring each year leading to significant envenomation mortality burden globally. Anti-venoms are vital life saving drugs which help in neutralizing the toxins caused by the bites and avoid serious consequences including organ failure and paralysis, thus providing treatment for one of the most neglected yet deadly diseases on earth. The market is driven further by favorable government policies, industry innovations and the World Health Organization goal of reducing snakebite mortality and disability by 50% by 2030.
In June 2024, MicroPharm Limited acquired Sanofi Pasteur's antivenom equine immunoglobulin product range, strengthening its position as a specialized manufacturer of equine-derived antivenom therapies. The acquisition represents another example of industry consolidation as companies seek to safeguard existing product lines and increase their ability to produce and distribute antivenom products on an international level.
To Get more information Anti-Venom Market - Request Free Sample Report
Anti-Venom Market Trends
-
Rising biotechnology investment in recombinant and monoclonal antibody-based anti-venom development.
-
Growing government stockpile programs supporting antivenom accessibility in endemic regions.
-
Continued industry consolidation as manufacturers acquire established antivenom product portfolios.
-
Increasing focus on high-potency monovalent antivenom products targeting medically significant species.
-
Expanding strategic partnerships between manufacturers and biotechnology firms on synthetic antivenoms.
U.S. Anti-Venom Market Outlook
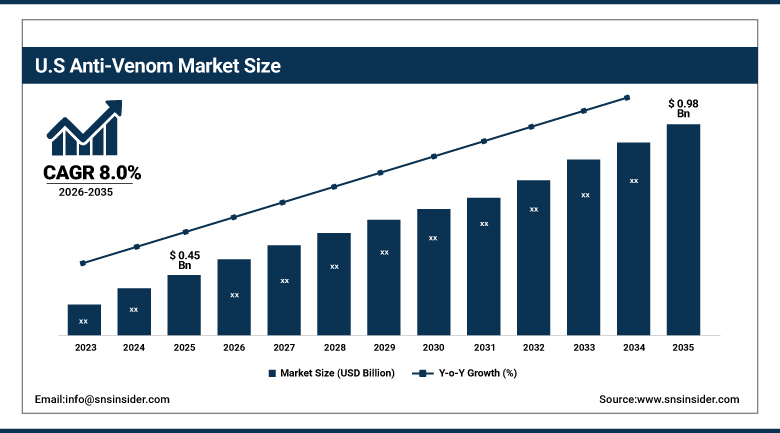
The U.S. Anti-Venom Market was valued at USD 0.45 Billion in 2025 and is expected to reach USD 0.98 Billion by 2035, growing at a CAGR of 8.0% from 2026-2035.
The U.S. Anti-Venom Market growth remains supported by the increased prevalence of envenomation injuries due to snakes and insects, as well as by the presence of top antivenom manufacturers and emergency infrastructure in the country. The domestic demand for the product is further facilitated by the existence of effective emergency infrastructure and FDA-approved antivenoms, which ensure consistent access to antivenoms. Additional regulatory focus on antivenom supply ensures the consistency of the domestic market through the efforts of manufacturers.
In 2025, the U.S. Food and Drug Administration extended the shelf life of Pfizer's coral snake antivenin because no alternative treatment was available, underscoring persistent supply fragility for certain antivenom products in the domestic market. The action reflects continued regulatory attention to ensuring reliable access to critical, life-saving antivenom therapies even where the underlying manufacturing base for niche envenomation treatments remains narrow.
Anti-Venom Market Segment Analysis
-
By Type, the Polyvalent segment dominated the Anti-Venom Market with approximately 62.50% share in 2025, while the Monovalent segment is the fastest growing with a CAGR of approximately 6.30%.
-
By Species, the Snake segment dominated the Anti-Venom Market with approximately 56.40% share in 2025, while the Scorpion segment is the fastest growing with a CAGR of approximately 7.80%.
-
By Mode of Action, the Neurotoxic segment dominated the Anti-Venom Market with approximately 50.40% share in 2025, while the Cytotoxic segment is the fastest growing with a CAGR of approximately 7.60%.
-
By End-User, the Hospitals & Clinics segment dominated the Anti-Venom Market with approximately 59.50% share in 2025, while the Ambulatory Surgical Centers segment is the fastest growing with a CAGR of approximately 7.90%.
By Type, Polyvalent dominates and Monovalent grows fastest
Polyvalent antivenom remains the dominant type segment within the Anti-Venom Market, reflecting its broad-spectrum neutralization capability against multiple venom types within a single formulation, making it the preferred choice for emergency treatment where the specific envenomating species may be uncertain. This segment benefits from its versatility across diverse clinical settings, particularly in regions with multiple medically significant venomous species.
Monovalent antivenom segment has been identified as the most rapidly growing among all segments. This is owing to advances in precision medicine technologies and huge investments made by major players into development of highly potent monovalent antivenom for treating the most important medically relevant species in North America, Europe, and Australia. The key emphasis of this segment is on the development of species-specific formulation with high levels of potency and low rates of adverse reactions.
By Species, Snake dominates and Scorpion grows fastest
Snakes constitute the leading segment within the Anti-Venom Market based on the estimation by the World Health Organization of millions of snakebite cases per year, resulting in the highest mortality rate globally from envenomation for any other type of venomous animal species. The segment derives from years of clinical experience and well-established protocols used as the foundation for anti-venom production globally.
Scorpion Sting is gaining momentum as the fastest growing segment among species. This is due to the increasing realization of health hazards associated with scorpion stings in arid and desert climates, which have high population density of scorpions. The "Scorpion Sting" segment targets to increase the availability of scorpion antivenoms in areas where scorpions abound in Middle East, North Africa, and Latin America.
By Mode of Action, Neurotoxic dominates and Cytotoxic grows fastest
Neurotoxic mode of action remains the dominant segment within the Anti-Venom Market, reflecting the prevalence of neurotoxic venom among medically significant snake species that cause respiratory paralysis and other life-threatening neurological complications requiring urgent antivenom intervention. This segment benefits from well-established clinical protocols for treating neurotoxic envenomation, which continues to represent the most immediately life-threatening category of venomous bites and stings.
Cytotoxic mode of action is becoming the most rapidly expanding category due to increased understanding of the link between tissue necrosis and injury caused by cytotoxic venoms, which may lead to severe long-term disabilities when left untreated. Cytotoxic antivenom category deals with antivenom products that can alleviate tissue injury and avoid complications leading to amputation, making cytotoxic antivenom more sought after for its disability-prevention capabilities besides mortality prevention.
By End-User, Hospitals & Clinics dominates and Ambulatory Surgical Centers grows fastest
Hospitals & Clinics remain the dominant end-user segment within the Anti-Venom Market, reflecting their established infrastructure for emergency envenomation treatment, including intensive care capabilities required for severe reactions to antivenom administration. This segment benefits from comprehensive diagnostic and treatment capabilities that continue to support hospital-based antivenom administration across diverse patient populations and severity levels.
Ambulatory Surgical Centers are emerging as the fastest-growing end-user segment, driven by expanding outpatient treatment capacity for less severe envenomation cases that do not require full hospital admission. This segment focuses on streamlined, cost-effective antivenom administration suited to lower-acuity cases, positioning ambulatory surgical centers to capture growing demand as healthcare systems continue seeking more efficient care delivery models for appropriate envenomation cases.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
82.90% |
|
Asia Pacific |
India |
44.60% |
|
Europe |
United Kingdom |
34.60% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
South Africa |
34.60% |
North America Anti-Venom Market Insights
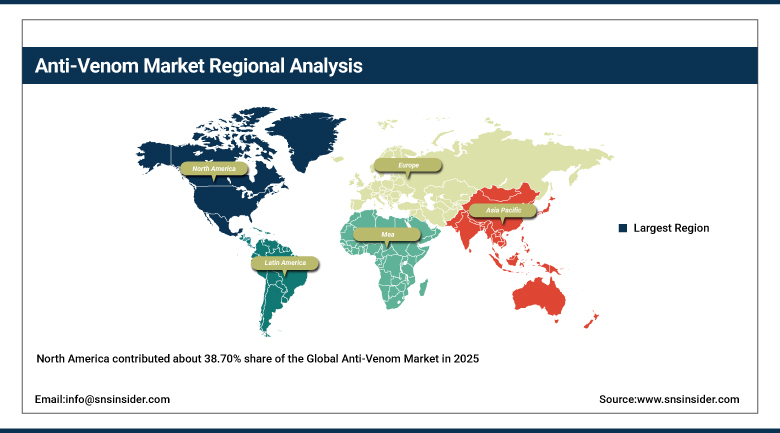
North America contributed about 38.70% share of the Global Anti-Venom Market in 2025 due to the presence of existing emergency healthcare infrastructure, specialized treatment facilities, and regulated supply of antivenom. The US continues to be the key contributor to regional demand due to the advanced emergency medical service systems and the presence of FDA regulations for antivenom drugs. FDA guidelines state that there are unique regulatory requirements for human use of antivenoms and there are approved products for venomous species.
Canada contributes additional demand through its established healthcare and emergency response infrastructure. Ongoing attention to medical countermeasure preparedness, product availability, and supply-chain reliability is expected to support regional demand. These factors are expected to reinforce North America's position as a significant regional market for anti-venom products throughout the forecast period.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Anti-Venom Market Insights
The Asia Pacific region is anticipated to witness the highest growth rate of around 9.2% in terms of CAGR throughout the forecast period of 2026 to 2035. This is due to the high burden of snakebite in the Asia Pacific region along with the growing capacity for antivenom production in the country. India stands out among other countries in the region in terms of its contribution, with tens of thousands of deaths from snakebites occurring annually.
China contributes additional regional demand, with government health initiatives placing antivenom on essential medicine lists for township clinics as part of broader healthcare access expansion. Continued rural trauma infrastructure investment and domestic manufacturing scale-up across the broader region further reinforce Asia Pacific's position as the fastest-growing global market for anti-venom.
Europe Anti-Venom Market Insights
Europe is an important region as far as the anti-venom market goes. This is because of the presence of antivenom manufacturers in the United Kingdom as well as envenomation treatment developers in this country. The proportion of the United Kingdom in Europe is determined by its proportion at home that includes holders of antivenom products portfolios.
Germany and France contribute additional regional demand, supported by established healthcare systems and emergency medical response capabilities. Continued European investment in antivenom research and development supports steady regional demand growth.
MEA & Latin America Anti-Venom Market Insights
Anti-Venom Market of Latin America is dominated by Brazil. Brazil contributes the bulk of demand in the Latin America due to its robust local capacity to manufacture antivenoms along with its infrastructure for supplying antivenom program throughout the country. Antivenom production and supply with the government support continue to fuel the regional market growth.
The Middle East & Africa region continues to grow in strategic importance, with demand concentrated in markets such as South Africa, which maintains an established antivenom manufacturing base serving domestic and regional export needs. The broader African continent, where the World Health Organization estimates hundreds of thousands of annual snakebites, continues to represent a significant area of unmet antivenom access need.
Market Dynamics
Growth Drivers: Rising Envenomation Incidence and Government Health Initiatives
The increase in cases of snake bites and insect stings is considered the major factor driving the market for Antivenom. The reason for the same is that in tropical and subtropical areas, people tend to seek traditional treatments rather than resorting to hospital and health centers due to the aforementioned conditions. Moreover, the development of favorable policies by the government along with the categorization of snake bite envenomation as a neglected tropical disease by WHO has contributed significantly to the same.
Rising biotechnology investment in recombinant and monoclonal antibody-based antivenoms provides an additional significant source of demand, as these technologies increase neutralization precision and minimize adverse side effects relative to conventional equine-derived formulations. Improved diagnostics and cold-chain storage capabilities further support market growth by enhancing the reach and effectiveness of antivenom therapies in remote and underserved regions.
Restraints: Supply Chain Fragility and Limited Manufacturing Base
The limited production facilities for some niche antivenin products can be considered a key restriction of the Anti-Venom Market since authorities had to prolong the expiration date of certain antivenins in the absence of any other possible treatments. This problem is complicated by the fact that manufacturing antivenins is an expensive and complicated process which still limits the number of companies that can produce some specialized products.
Limited access to timely medical care in rural and tropical regions restricts antivenom utilization even where products are available, as many envenomation victims continue to rely on traditional remedies rather than seeking hospital treatment. Continued cold-chain storage and distribution challenges in endemic regions add further complexity to ensuring reliable antivenom access where it is needed most.
Opportunities: Recombinant Antivenom Development and Emerging Market Access Expansion
The various advancements in the field of antivenom using recombinant antibodies and monoclonal antibodies represent a great market growth potential for the Anti-Venom Market, since such new-age antivenoms help in decreasing the reliance on animal sera. Those companies that will be able to develop antibody platforms that have been successfully validated and neutralize broadly represent companies that have huge potential in the market.
Rising domestic manufacturing capacity expansion across endemic regions presents a longer-term opportunity for manufacturers to strengthen local production and distribution capabilities serving underserved populations. As government procurement programs continue expanding across South Asia, Africa, and Latin America, manufacturers with established regional manufacturing partnerships are positioned to capture a disproportionate share of this growing demand.
Recent Developments:
-
2025: Bharat Serums and Vaccines Ltd. announced a strategic partnership with a biotechnology firm to co-develop synthetic antivenoms utilizing monoclonal antibody technology, targeting highly specific, safer treatments for neglected venomous species prevalent in South Asia and Africa.
-
2025: CSL Seqirus opened an integrated vaccine and antivenom manufacturing facility in Tullamarine, Melbourne, designed to produce Australian antivenoms and other biologics, strengthening domestic manufacturing capacity and supply security.
-
2025: VINS Bioproducts was listed among Indian manufacturers of snake venom antiserum in WHO South-East Asia regional materials, documenting its role in the region’s antivenom supply landscape.
Anti-Venom Market Key Players are:
-
CSL Limited
-
Pfizer Inc.
-
Merck & Co., Inc.
-
Boehringer Ingelheim International GmbH
-
Sanofi S.A.
-
Bharat Serums and Vaccines Ltd.
-
Serum Institute of India Pvt. Ltd.
-
Instituto Bioclon S.A. de C.V.
-
Vins Bioproducts Limited
-
Premium Serums & Vaccines Pvt. Ltd.
-
South African Vaccine Producers (Pty) Ltd.
-
Haffkine Bio-Pharmaceutical Corporation Limited
-
Incepta Pharmaceuticals Limited
-
Instituto Butantan
-
MicroPharm Limited
-
Rare Disease Therapeutics, Inc.
-
Laboratorios Silanes S.A.
-
BTG plc
-
Indian Immunologicals Limited
-
Instituto Clodomiro Picado
Anti-Venom Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 1.41 Billion |
| Market Size by 2035 | USD 2.93 Billion |
| CAGR | CAGR of 7.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Type (Polyvalent, Monovalent, Others) • By Species (Snake, Scorpion, Spider, Others) • By Mode of Action (Neurotoxic, Cytotoxic, Haemotoxic, Cardiotoxic, Myotoxic, Others) • By End-User (Hospitals & Clinics, Ambulatory Surgical Centers, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | CSL Limited, Pfizer Inc., Merck & Co., Inc., Boehringer Ingelheim International GmbH, Sanofi S.A., Bharat Serums and Vaccines Ltd., Serum Institute of India Pvt. Ltd., Instituto Bioclon S.A. de C.V., Vins Bioproducts Limited, Premium Serums & Vaccines Pvt. Ltd., South African Vaccine Producers (Pty) Ltd., Haffkine Bio-Pharmaceutical Corporation Limited, Incepta Pharmaceuticals Limited, Instituto Butantan, MicroPharm Limited, Rare Disease Therapeutics, Inc., Laboratorios Silanes S.A., BTG plc, Indian Immunologicals Limited, Instituto Clodomiro Picado. |

Frequently Asked Questions
Leading companies in the Anti-Venom Market include CSL Limited, Pfizer, Merck & Co., Boehringer Ingelheim, and Sanofi, among others.
Key opportunities include continued development of recombinant and monoclonal antibody-based antivenom technology, and rising domestic manufacturing capacity expansion across endemic regions.
The rising incidence of snakebites and venomous insect stings, combined with favorable government initiatives and the World Health Organization's neglected tropical disease designation, is the major factor driving market growth.
The Snake segment dominated the Anti-Venom Market with approximately 56.40% share in 2025.
North America dominated the Anti-Venom Market in 2025 with approximately 38.70% share, supported by robust emergency care infrastructure and FDA-approved formulations, led by the United States.
