
Automatic Labelling Machine Market Report Scope & Overview:
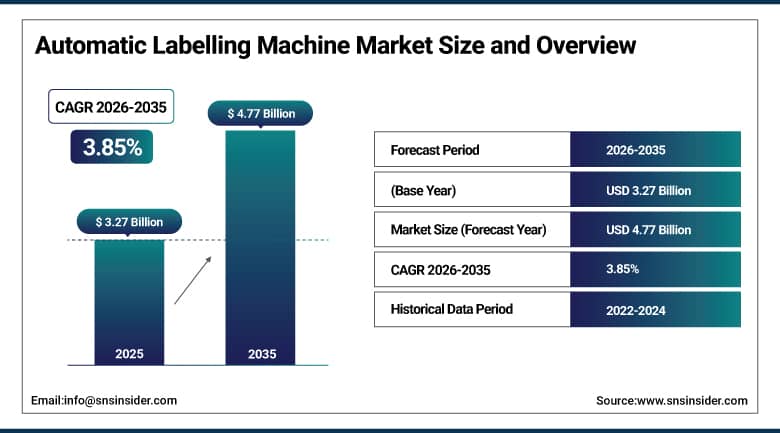
The Automatic Labelling Machine Market was valued at USD 3.27 Billion in 2025 and is expected to reach USD 4.77 Billion by 2035, growing at a CAGR of 3.85% from 2026 to 2035.
The automatic labelling machine's work involves placing a label accurately and quickly, but the accuracy bar keeps rising as regulators demand better traceability and brands chase more elaborate label designs on shorter production runs. What used to be a fairly mechanical piece of packaging-line equipment now often includes vision inspection systems that catch misapplied or missing labels in real time, plus IoT connectivity that feeds line-performance data back to plant managers. Growth is steady rather than explosive, since most large manufacturers already run some form of automated labelling, but replacement demand, serialization compliance in pharmaceuticals, and expansion of packaged food production in emerging markets are all keeping order books full.
In September 2025, Avery Dennison Corporation launched its AD CleanGlass and AD CleanFiber recyclable label solutions at Labelexpo Europe 2025, enabling cleaner label removal for reusable glass and paper recycling streams.
To Get More Information On Automatic Labelling Machine Market - Request Free Sample Report
Automatic Labelling Machine Market Trends
- Vision inspection systems are becoming close to standard on new labelling lines to catch misapplied or missing labels in real time.
- Print-and-apply RFID labelling is expanding in pharmaceuticals and logistics as serialization rules tighten.
- Servo-driven labelling heads are replacing older pneumatic and mechanical mechanisms for tighter placement accuracy.
- Shrink-sleeve labelling is gaining share in beverage and personal care categories chasing 360-degree branding.
- Manufacturers are integrating IoT connectivity into labelling equipment to feed real-time line performance data to plant managers.
The U.S. Automatic Labelling Machine Market Outlook
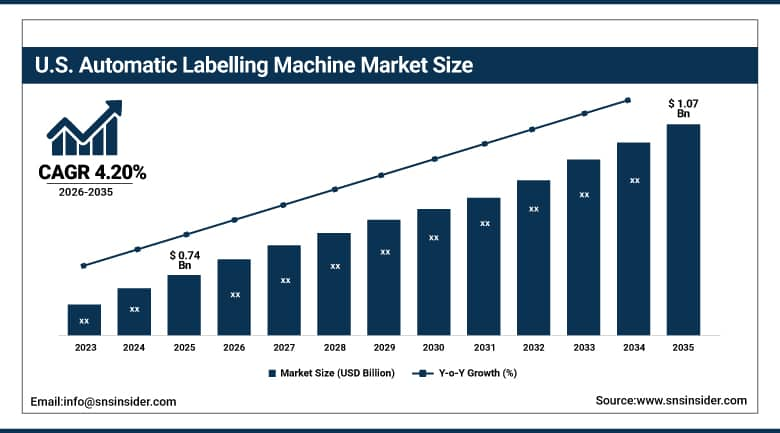
The U.S. automatic labelling machine market was valued at USD 0.74 Billion in 2025 and is projected to reach USD 1.07 Billion by 2035, growing at a CAGR of 4.20% during 2026-2035.
Pharmaceutical serialization requirements have been one of the more consistent demand drivers in the U.S. market, pushing manufacturers toward print-and-apply systems that can encode and verify unique product identifiers at line speed. Food and beverage producers are replacing older mechanical labelling equipment with servo-driven systems that hold tighter tolerances on smaller, more frequently changed label runs, a shift driven partly by private-label proliferation on grocery shelves. E-commerce fulfillment has added its own demand line too, since shipping labels and compliance labels for direct-to-consumer packages require faster changeover between SKUs than traditional retail distribution ever did. Domestic equipment manufacturers are also fielding steady replacement demand as older labelling lines reach end of service life.
In 2025, Krones AG expanded its print-and-apply RFID labelling systems to support stricter product serialization and supply chain traceability requirements across pharmaceutical and food packaging lines.
Automatic Labelling Machine Market Segment Analysis
- By Labeling Type, self-adhesive segment dominated the automatic labelling machine market in 2025 with 39% share; shrink-sleeve segment is the fastest-growing segment, registering a CAGR of 6.20% from 2026 to 2035.
- By Automation Level, fully automatic segment dominated the automatic labelling machine market in 2025 with 62% share; semi-automatic segment is the fastest-growing segment, registering a CAGR of 5.80% from 2026 to 2035.
- By End-User, food & beverage segment dominated the automatic labelling machine market in 2025 with 38% share; pharmaceuticals segment is the fastest-growing segment, registering a CAGR of 6.90% from 2026 to 2035.
- By Drive Type, servo-driven segment dominated the automatic labelling machine market in 2025 with 52% share; electromechanical segment is the fastest-growing segment, registering a CAGR of 5.40% from 2026 to 2035.
By Labeling Type, self-adhesive dominates the automatic labelling machine market while shrink-sleeve grows fastest
Self-adhesive labelling holds 39% of the automatic labelling machine market, and it is easy to see why once you consider how many different container shapes and materials it can handle without requiring a dedicated adhesive or heat-application system. Pressure-sensitive labels apply cleanly to glass, plastic, and metal alike, which makes self-adhesive equipment the default choice for manufacturers running mixed product lines rather than a single container format.
Shrink-sleeve labelling is growing at a 6.20% CAGR, the fastest pace among labelling types, pulled forward by beverage and personal care brands chasing full 360-degree branding that a flat label simply cannot deliver. The format also conveniently hides seams, tamper bands, and irregular bottle shapes that would otherwise complicate a standard label application, which has made it increasingly popular for premium and craft beverage packaging.
By Automation Level, fully automatic dominates the automatic labelling machine market while semi-automatic grows fastest
Fully automatic machines account for 62% of the market, reflecting how far labelling technology has come from manual and semi-manual application even in mid-sized manufacturing operations. High-volume food, beverage, and pharmaceutical producers need labelling speeds that only fully automated lines can sustain, and the cost of downtime from manual bottlenecks has made full automation the economically obvious choice for most large-scale operations.
Semi-automatic machines are growing fastest, at a 5.80% CAGR, largely because smaller manufacturers and specialty producers running short, frequently changing production batches do not need, or cannot justify the capital cost of, a fully automated line. Craft beverage producers, specialty cosmetics brands, and contract packagers handling variable order sizes have been the biggest adopters of this format.
By End-User, food & beverage dominates the automatic labelling machine market while pharmaceuticals grows fastest
Food & beverage accounts for 38% of end-user demand, the largest single category, reflecting both the sheer production volume in this industry and the regulatory requirement for accurate ingredient, nutrition, and allergen labelling on virtually every packaged product. Private-label proliferation across grocery retail has added further demand, since retailers frequently update packaging and label designs more often than legacy national brands do.
Pharmaceuticals is the fastest-growing end-user segment, expanding at a 6.90% CAGR, driven almost entirely by tightening serialization and anti-counterfeiting regulations that require unique, verifiable identifiers on individual product units. Print-and-apply and RFID labelling systems capable of encoding and verifying that data at line speed are becoming close to mandatory equipment for pharmaceutical manufacturers operating in regulated markets.
By Drive Type, servo-driven dominates the automatic labelling machine market while electromechanical grows fastest
Servo-driven systems hold 52% of the drive-type market, offering the placement precision and speed consistency that pneumatic and mechanical alternatives generally cannot match, particularly on smaller or irregularly shaped containers where a fraction of a millimeter of misalignment is visible to consumers. Manufacturers running high-speed lines with frequent SKU changes have largely standardized on servo-driven equipment for this reason.
Electromechanical systems are growing fastest among drive types, at a 5.40% CAGR, as cost-conscious manufacturers in emerging markets look for a middle ground between basic pneumatic equipment and premium servo-driven systems. These systems offer meaningfully better precision than older pneumatic designs at a lower capital cost than full servo systems, which suits manufacturers scaling up automation for the first time.
Regional Analysis
|
Region |
Country |
Share (2025) |
|
North America |
United States |
87.20% |
|
Asia Pacific |
China |
34.80% |
|
Europe |
Germany |
26.30% |
|
Middle East & Africa |
UAE |
16.40% |
|
Latin America |
Brazil |
29.60% |
Asia Pacific Automatic Labelling Machine Market Insights
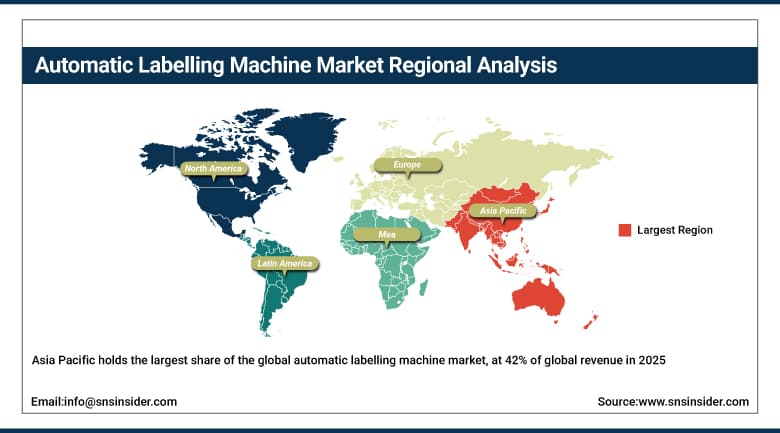
Asia Pacific holds the largest share of the global automatic labelling machine market, at 42% of global revenue in 2025, anchored by the region's massive food, beverage, and consumer goods manufacturing base and continued shift from manual to automated labelling across mid-sized manufacturers. China's sheer scale of packaged goods production accounts for a large part of that lead, while India's expanding pharmaceutical and consumer goods sectors are adding meaningful additional demand.
China holds roughly 34.80% of the regional market, supported by its scale in food, beverage, and consumer goods manufacturing. India is growing quickly as automation adoption expands beyond large manufacturers into mid-sized packaged goods producers, while Japan and South Korea contribute through their established pharmaceutical and electronics packaging sectors.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automatic Labelling Machine Market Insights
North America's automatic labelling machine market is expected to be the fast-growing region during the forecast period. This is supported by high existing automation penetration across food, beverage, and pharmaceutical manufacturing. Most large U.S. and Canadian manufacturers already run some form of automated labelling, so growth here comes mostly from replacement cycles and serialization-driven upgrades rather than first-time automation adoption.
The United States accounts for approximately 87.20% of the North American market, reflecting its large manufacturing base across food, beverage, and pharmaceutical sectors. Canada contributes a smaller but steady share, tied to its own food safety labelling requirements and export-oriented packaged goods industry.
Europe Automatic Labelling Machine Market Insights
The market of automatic labelling machines in Europe is stable because it is driven by stringent regulations from the EU regarding labelling that include things such as ingredient disclosures and recyclability icons. The demands for replacements and upgrades remain consistent regardless of lack of growth in volume due to increased demands for sustainability in the purchase of labelling equipment that uses recyclable labels.
Germany has 26.30% market share in Europe owing to its strong manufacturing industry and advanced packaging equipment industry. France and UK are the other two markets, where the demand for labelling machines is dependent on the pharmaceutical and food & beverages manufacturing industries of the two countries.
Middle East & Africa and Latin America Automatic Labelling Machine Market Insights
The Middle East & Africa region is growing steadily as packaged food and consumer goods manufacturing expands across the Gulf states, supported by rising import substitution efforts and growing modern retail penetration. Latin America is the steady-growing region globally. This is due to the expansion of packaged food, beverage, and personal care manufacturing across Brazil and Mexico as regional producers move away from manual labelling toward automated systems.
The UAE leads the Middle East & Africa market with a 16.40% share, supported by its role as a regional manufacturing and distribution hub. Brazil represents 29.60% of the Latin American market, reflecting its large food and beverage manufacturing base, with Mexico also contributing through its growing packaged consumer goods export industry.
Market Dynamics
Growth Drivers: Regulatory Traceability and Automation Upgrades Fueling Market Growth
Tightening serialization and traceability regulations, particularly in pharmaceuticals, are the clearest driver behind steady demand for more sophisticated labelling equipment capable of encoding and verifying unique product identifiers at line speed. Replacement of aging mechanical and pneumatic labelling lines with servo-driven, vision-inspected systems is adding a second consistent demand line across mature manufacturing markets.
Expansion of packaged food, beverage, and consumer goods manufacturing across emerging markets is creating first-time automation demand in regions where manual labelling has historically been common, particularly across Latin America and parts of Asia Pacific.
Restraints: High Equipment Costs and Integration Complexity Limiting Market Expansion
Fully automated, servo-driven labelling systems with vision inspection carry a significant capital cost that smaller manufacturers in price-sensitive markets often cannot justify, particularly for lower-volume production lines where the payback period stretches out. Integrating new labelling equipment into existing packaging lines can also be more complex than it looks, since line speed, container handling, and label material compatibility all need to work together without introducing new bottlenecks.
Skilled technician availability for maintaining and troubleshooting increasingly software-driven labelling equipment is uneven across regions, which can slow adoption in markets where manufacturers lack in-house automation expertise.
Opportunities: RFID Integration and Sustainable Labelling Creating New Growth Avenues
Print-and-apply RFID labelling represents a clear growth opportunity as pharmaceutical, logistics, and retail supply chains push toward item-level tracking that goes beyond basic barcode scanning. Equipment makers who can integrate reliable RFID encoding and verification into standard labelling lines stand to capture a meaningful share of this upgrade cycle.
Compatibility with recyclable and sustainable label materials, including wash-off adhesives and mono-material label constructions, is emerging as a second opportunity as brand owners respond to packaging waste regulations that increasingly extend to labels themselves, not just the containers they are applied to.
Recent Developments:
- 2025: Avery Dennison Corporation launched its AD CleanGlass and AD CleanFiber recyclable label solutions at Labelexpo Europe 2025, enabling cleaner label removal for reusable glass and paper recycling streams.
- 2025: Krones AG expanded its print-and-apply RFID labelling systems to support stricter product serialization and supply chain traceability requirements across pharmaceutical and food packaging lines.
- 2024: HERMA GmbH demonstrated new label-based marking technology for chemical and pharmaceutical product compliance at ACHEMA, targeting stricter hazard-labelling requirements.
- 2025: ProMach Inc. continued integrating vision inspection and IoT-enabled monitoring across its labelling equipment brands to support real-time quality verification on high-speed lines.
Automatic Labelling Machine Market key players are:
- Krones AG
- FUJI Seal International Inc.
- HERMA GmbH
- SATO Holdings Corporation
- ProMach Inc.
- Avery Dennison Corporation
- Label-Aire Inc.
- Accutek Packaging Equipment Co. Inc.
- ID Technology LLC
- CTM Labeling Systems
- Weber Packaging Solutions Inc.
- Universal Labeling Systems Inc.
- P.E. Labellers S.p.A.
- Pack Leader Machinery Inc.
- KWT Machine Systems Co. Ltd.
- Langguth GmbH
- Quadrel Labeling Systems
- NITA Labeling Equipment
- Volabel AB
- World Pack Automation Systems Private Limited
Automatic Labelling Machine Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.27 Billion |
| Market Size by 2035 | USD 4.77 Billion |
| CAGR | CAGR of 3.85% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Labeling Type (Self-Adhesive, Shrink-Sleeve, Glue-Based Labelers, Others) • By Automation Level (Fully Automatic, Semi-Automatic) • By End-User (Food & Beverage, Pharmaceuticals, Cosmetics & Personal Care, Chemicals, Logistics and E-Commerce, Others) • By Drive Type (Servo-Driven, Electromechanical, Pneumatic, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Krones AG, FUJI Seal International Inc., HERMA GmbH, SATO Holdings Corporation, ProMach Inc., Avery Dennison Corporation, Label-Aire Inc., Accutek Packaging Equipment Co. Inc., ID Technology LLC, CTM Labeling Systems, Weber Packaging Solutions Inc., Universal Labeling Systems Inc., P.E. Labellers S.p.A., Pack Leader Machinery Inc., KWT Machine Systems Co. Ltd., Langguth GmbH, Quadrel Labeling Systems, NITA Labeling Equipment, Volabel AB, World Pack Automation Systems Private Limited |
Frequently Asked Questions
Key players include Krones AG, FUJI Seal International Inc., HERMA GmbH, SATO Holdings Corporation, and ProMach Inc., alongside other established labelling equipment manufacturers.
Key opportunities include print-and-apply RFID integration for item-level supply chain tracking, compatibility with recyclable and sustainable label materials, and rising first-time automation demand across emerging manufacturing markets.
The market is driven by tightening serialization and traceability regulations, replacement of aging mechanical labelling lines with servo-driven systems, and expanding packaged goods manufacturing across emerging markets.
The Self-Adhesive segment dominated the Automatic Labelling Machine Market in 2025.
The Asia Pacific region dominated the Automatic Labelling Machine Market in 2025, accounting for approximately 42% of global market share.
