
Automatic Lubrication System Market Report Scope & Overview:
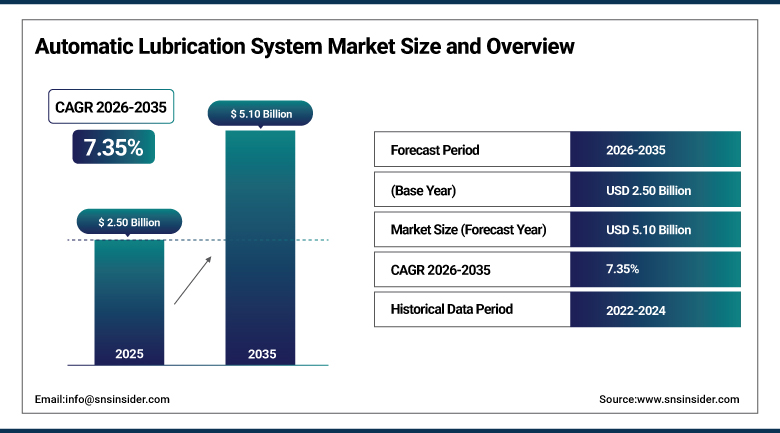
The Automatic Lubrication System Market was valued at USD 2.50 Billion in 2025 and is expected to reach USD 5.10 Billion by 2035, growing at a CAGR of 7.35% from 2026-2035.
Automatic Lubrication Systems Market refers to centralized and single point lubrication devices including reservoirs, pumps, metering valves, and injectors that deliver metered quantities of grease/oil to machine parts while machines are running, thereby eliminating the requirement of manually lubricating them. The key factors behind market growth include the push towards automation of industries in sectors like manufacturing, mining, construction, and transport, whereby automatic lubrication ensures lesser unscheduled downtime, increases part longevity, and results in lower maintenance costs than manually scheduled lubrication systems. The growing integration of lubrication systems within Industry 4.0 platforms is enabling manufacturers to incorporate Internet of Things-based systems within them, thereby offering visibility into lubricant usage and equipment condition in order to facilitate predictive maintenance programs. Workplace safety laws are further encouraging their use, as they require no person to access dangerous or inaccessible lubrication points of running machinery.
In March 2026, The Timken Company acquired the assets and related businesses of Bijur Delimon International, a leading designer and manufacturer of automated lubrication systems founded in 1872 and serving the rail, power generation, and mining sectors, with the acquired business expected to generate more than USD 60 million in sales in 2026.
To Get more information Automatic Lubrication System Market - Request Free Sample Report
Automatic Lubrication System Market Trends
-
Growing integration of IoT-enabled sensors into lubrication systems to support predictive maintenance programs.
-
Continued consolidation among established bearing and industrial motion manufacturers acquiring specialized lubrication systems businesses.
-
Rising adoption of automated lubrication in mining and construction equipment to reduce manual greasing in hazardous environments.
-
Expanding use of progressive and dual-line systems in heavy machinery requiring precise multi-point lubricant distribution.
-
Increasing demand for automated lubrication as a labor-saving solution amid ongoing skilled-technician shortages in industrial maintenance.
U.S. Automatic Lubrication System Market Outlook
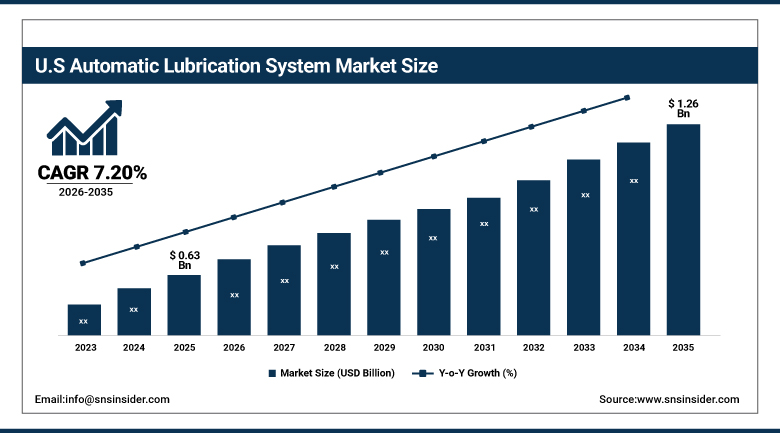
The U.S. Automatic Lubrication System Market was valued at USD 0.63 Billion in 2025 and is expected to reach USD 1.26 Billion by 2035, growing at a CAGR of 7.20% from 2026-2035.
United States represents the largest single-country market for automatic lubrication systems, fueled by significant investment in industrial automation in manufacturing, mining and heavy equipment maintenance, along with concentrated manufacturing in the country, dominated by players such as Graco, Timken and Bijur Delimon. The trend towards increasing on-shore manufacturing capacities and high capital spending in mining, construction and energy infrastructure continue to fuel demand for automatic lubrication equipment, which minimizes maintenance labor due to chronic shortages of skilled labor in industrial maintenance.
In January 2025, Graco Inc. restructured into a new global Industrial Division combining its Industrial and Lubrication Equipment divisions with its Process Transfer Equipment business, integrating previously independent regional operations into a unified global divisional structure effective at the start of the year.
Automatic Lubrication System Market Segment Analysis
-
By Product Type, the Oil-Based segment dominated the Automatic Lubrication System Market with approximately 57.40% share in 2025, while the Grease-Based segment is the fastest growing with a CAGR of approximately 8.65%.
-
By System Type, the Progressive segment dominated the Automatic Lubrication System Market with approximately 41.20% share in 2025, while the Dual-Line segment is the fastest growing with a CAGR of approximately 8.90%.
-
By End-Use Industry, the Manufacturing segment dominated the Automatic Lubrication System Market with approximately 29.75% share in 2025, while the Mining & Construction segment is the fastest growing with a CAGR of approximately 9.35%.
By Product Type, Oil-Based dominates, and Grease-Based grows fastest
Oil-based lubrication systems held the largest product share in 2025, reflecting their widespread use in high-speed rotating machinery, gearboxes, and precision manufacturing equipment where oil's superior flow characteristics and heat dissipation properties are essential to maintaining performance. Circulating oil systems are particularly favored in continuous manufacturing environments where consistent, high-volume lubricant delivery to numerous points is required across an operating shift.
Grease-based systems are growing fastest as mining, construction, and heavy off-highway equipment Oil-based lubrication systems had the biggest product market share in 2025 due to the wide usage of oil in high-speed rotating devices, gears, and machines for manufacturing because of its excellent flow and heat dissipation qualities. In particular, circulating oil systems are popular in industries with constant production where large quantities of oil need to be delivered to many points.
Systems based on grease are developing at the fastest rate since automated grease systems become more common in mining and construction equipment, which allows replacing manual lubrication of exposed parts of machines such as excavators and loaders operating in tough environments. The advantages of grease as a lubricant include excellent adhesion and moisture resistance qualities, making it the right choice for equipment that works in dusty and wet environments, as well as in wide temperature ranges.
By System Type, Progressive dominates, and Dual-Line grows fastest
Progressive lubrication systems dominated the market in terms of system types in 2025 due to their capacity to dispense precise quantities of lubricants at multiple points using only one pump and distribution system. The fact that progressive lubrication systems can distribute lubricant through many points from a single unit makes them suitable for complex machines and manufacturing equipment having multiple lubrication points. Moreover, progressive lubrication systems have the advantage of being able to monitor themselves since blockage of any injector in a progressive sequence is easily identifiable.
The dual-line systems are the fastest growing segment because they are most suitable for large-scale industrial and mining equipment which requires lubricating systems that are able to cover larger distances for lubrication along with many lubrication points. In addition, having two supply lines makes dual-line systems more reliable for critical equipment since lubrication failure of this equipment would be very expensive for the manufacturers.
By End-Use Industry, Manufacturing dominates, and Mining & Construction grows fastest
Manufacturing held the largest end-use share in 2025, reflecting the sheer breadth of machine tools, conveyors, presses, and production line equipment across discrete and process manufacturing that rely on automated lubrication to maintain uptime and extend equipment service life. Manufacturers' sustained focus on Industry 4.0 adoption and predictive maintenance programs continues to reinforce automated lubrication as a standard specification for new production equipment.
Mining & Construction is the fastest-growing end-use segment as elevated capital investment in mining production and infrastructure construction projects drives demand for automated lubrication on heavy equipment operating in remote, harsh environments where manual greasing is both labor-intensive and hazardous. The segment's growth is further reinforced by workplace safety regulations that increasingly discourage manual access to lubrication points on operating heavy equipment, making automated systems a compliance-supporting investment rather than a purely cost-driven upgrade.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
76.20 |
|
Europe |
Germany |
34.85 |
|
Asia Pacific |
China |
39.60 |
|
Middle East & Africa |
Saudi Arabia |
35.75 |
|
Latin America |
Brazil |
47.90 |
North America Automatic Lubrication System Market Insights
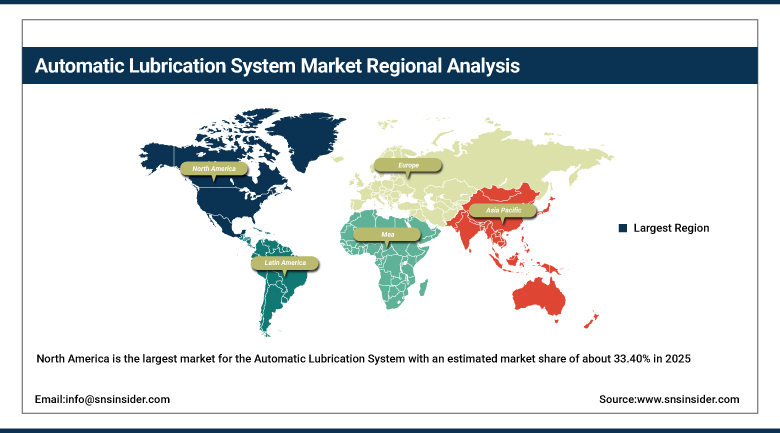
North America is the largest market for the Automatic Lubrication System with an estimated market share of about 33.40% in 2025. This is attributed to the large capital investments being made in the region for automation of industries, mining operations, and maintenance of heavy equipment in the US, along with high domestic production capability of the equipment with companies such as Graco, Timken, and Bijur Delimon. Investment in reshoring manufacturing capabilities, construction, and expansion projects continue to fuel higher equipment demand in North America.
The US accounts for the bulk of the regional revenue generation due to its wide distribution channel catering to both original equipment manufacturers and aftermarket customers in its industry. The mining and resource extraction industries of Canada provide regional demand due to their dependence on automated lubrication systems to keep heavy equipment running in locations where maintenance labor is difficult to access.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Automatic Lubrication System Market Insights
Asia Pacific has been found to be the fastest-growing region in the Automatic Lubrication System Market, with a forecast growth rate of 9.10% CAGR during the 2026-2035 forecast period. This is due to factors such as the rapid industrialization taking place in the region, increased manufacturing production, and massive investment in infrastructures as well as mining projects in China, India, and Southeast Asia.
Increased manufacturing capacity and continued investments in the mining and heavy construction machinery sectors in China are some of the factors that are driving regional demand in Asia Pacific for automatic lubrication systems. Growing demand from the industrial as well as the infrastructure construction industry sectors in India, in addition to SKF's expanding footprint in the region post-acquisition of the lubrication & flow management businesses from John Sample Group in 2024, is providing an added boost to the demand.
Europe Automatic Lubrication System Market Insights
Europe represents a mature automatic lubrication system market, underpinned by Germany's extensive manufacturing base and strong emphasis on industrial automation and predictive maintenance practices across its automotive, machine tool, and heavy industry sectors. Germany's dense concentration of precision manufacturing and machine tool builders sustains steady demand for high-precision progressive and dual-line lubrication systems integrated directly into new equipment at the point of manufacture.
France, Italy, and the United Kingdom contribute meaningful additional regional demand through their own automotive, aerospace, and heavy industry manufacturing sectors, while Nordic countries maintain elevated adoption rates tied to their wind energy and marine equipment industries, both of which rely heavily on automated lubrication for equipment operating in remote or harsh offshore environments. Continued European emphasis on workplace safety regulation is expected to sustain steady, if moderate, regional demand growth through the forecast period.
MEA & Latin America Automatic Lubrication System Market Insights
The Middle East & Africa automatic lubrication system market is expanding as Gulf Cooperation Council states invest in oil and gas infrastructure, petrochemical processing, and large-scale construction projects, with Saudi Arabia driving the bulk of regional demand given its extensive energy sector capital expenditure and diversification-driven infrastructure investment. Regional mining activity across parts of Africa is contributing additional incremental demand for automated lubrication on heavy extraction equipment.
Latin America is led by Brazil, where sustained mining sector investment and growing manufacturing output are driving demand for automated lubrication systems, supported by the country's established industrial base serving both domestic and regional export markets. Mexico's expanding automotive and manufacturing sectors, bolstered by nearshoring investment, are contributing additional regional demand as global manufacturers relocate production capacity closer to North American end markets.
Market Dynamics
Growth Drivers: Industrial Automation and Predictive Maintenance Adoption
The general trend towards industrial automation in manufacturing, mining, and equipment businesses is the key factor influencing the demand for automatic lubrication systems, as equipment managers perceive automatic lubrication as the core component of reliability-centered maintenance programs. The overall financial effectiveness of such systems due to reduced costs and lower chances of bearing wear caused by improper lubrication ensures that even though the industry is generally careful with capital expenditures, investments into the equipment are still justified.
The ability of automatic lubrication systems to be integrated with Industry 4.0 platforms and IoT-enabled systems of condition monitoring helps strengthen this trend by making it possible for the maintenance teams to replace the scheduled lubrication routines with predictive maintenance based on information on lubricant usage and operating conditions of the equipment, which makes the use of such systems even more appealing to industrial customers as a competitive advantage in their asset management.
Restraints: High Initial Investment and Limited End-User Awareness
The relatively high upfront cost of automated lubrication systems compared with manual greasing remains a meaningful restraint, particularly for smaller manufacturers and equipment operators with limited capital budgets who may not fully value the long-term maintenance savings against the immediate installation and equipment cost. This cost sensitivity is especially pronounced among smaller mining and construction contractors operating older equipment fleets not originally designed for retrofit automated lubrication.
Limited awareness of the total cost-of-ownership benefits of automated lubrication among some end users continues to constrain broader market penetration, particularly in developing regions where manual lubrication remains the entrenched default practice and maintenance decision-makers may lack access to the equipment reliability data needed to build a clear investment case. Overcoming this awareness gap typically requires direct engagement and demonstration programs from manufacturers, adding to customer acquisition costs in less mature regional markets.
Opportunities: Consolidation-Driven Platform Expansion and Emerging Market Penetration
Continued consolidation among established lubrication systems manufacturers, exemplified by Timken's 2026 acquisition of Bijur Delimon and SKF's 2024 acquisition of John Sample Group's lubrication and flow management businesses, presents an opportunity for acquiring companies to expand their addressable end markets and geographic reach more quickly than organic investment would allow. These transactions are enabling acquirers to offer broader, more integrated reliability platforms spanning bearings, lubrication, and condition monitoring to industrial customers.
Expanding industrial and mining investment across emerging markets in Asia Pacific, the Middle East, and Latin America presents a further opportunity for manufacturers to establish early distribution and service relationships ahead of increased competitive entry, particularly as regional manufacturing and resource extraction capacity continues to grow faster than in mature Western markets. Manufacturers that build local service and installation capability in these fast-growing regions are positioned to capture a disproportionate share of incremental demand as automated lubrication adoption broadens beyond its currently concentrated base in North America and Europe.
Recent Developments:
-
March 2026- The Timken Company acquired the assets and related businesses of Bijur Delimon International, a designer and manufacturer of automated lubrication systems serving the rail, power generation, and mining sectors, expected to generate more than USD 60 million in sales in 2026.
-
August 2024- SKF signed an agreement to acquire John Sample Group's Lubrication and Flow Management businesses, strengthening its automatic lubrication systems offering and expanding its presence across India and Southeast Asia.
-
January 2025- Graco Inc. restructured into a new global Industrial Division combining its Industrial and Lubrication Equipment divisions with its Process Transfer Equipment business, integrating previously independent regional operations into a unified global structure.
-
February 2020- Graco Inc. introduced the Compact Dyna-Star automatic lubrication system, engineered specifically for heavy-duty earthmoving machines operating in extreme work environments.
Automatic Lubrication System Market Key Players
-
SKF Group
-
Graco Inc.
-
The Timken Company
-
Bijur Delimon International
-
Lincoln Industrial Corporation
-
Groeneveld-BEKA
-
DropsA S.p.A.
-
Pulsarlube Co., Ltd.
-
Cenlub Systems
-
JSG Industrial Systems Pty Ltd.
-
Valin Corporation
-
Baier + Köppel GmbH & Co. KG
-
Andantex USA Inc.
-
Lubecore International Inc.
-
Lubrite Industries
-
Oil-Rite Corporation
-
Pricol Limited
-
Esko Pacific Sales Ltd.
-
ILC S.r.l.
-
Vogel Lubrication (SKF)
Automatic Lubrication System Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 2.50 Billion |
| Market Size by 2035 | USD 5.10 Billion |
| CAGR | CAGR of 7.35% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Oil-Based and Grease-Based) • by System Type (Single-Line, Dual-Line, and Progressive) • by End-Use Industry (Manufacturing, Automotive, Mining & Construction, Energy & Power, and Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | SKF Group, Graco Inc., The Timken Company, Bijur Delimon International, Lincoln Industrial Corporation, Groeneveld-BEKA, DropsA S.p.A., Pulsarlube Co., Ltd., Cenlub Systems, JSG Industrial Systems Pty Ltd., Valin Corporation, Baier + Köppel GmbH & Co. KG, Andantex USA Inc., Lubecore International Inc., Lubrite Industries, Oil-Rite Corporation, Pricol Limited, Esko Pacific Sales Ltd., ILC S.r.l., Vogel Lubrication (SKF) |
Frequently Asked Questions
North America dominated the Automatic Lubrication System Market with approximately 33.40% share in 2025, supported by extensive industrial automation investment and a concentrated domestic manufacturing base.
Key players in the Automatic Lubrication System Market include SKF Group, Graco Inc., The Timken Company, Bijur Delimon International, and Lincoln Industrial Corporation, among others.
Key opportunities lie in consolidation-driven platform expansion that broadens acquirers' reliability offerings, and in penetrating fast-growing industrial and mining markets across Asia Pacific, the Middle East, and Latin America.
The broad shift toward industrial automation and predictive maintenance, supported by IoT-enabled condition monitoring integration, is the major growth factor driving automatic lubrication system adoption.
By Product Type, the Oil-Based segment dominated the Automatic Lubrication System Market with approximately 57.40% share in 2025.
