
Automotive Active Purge Pump Market Report Scope & Overview:
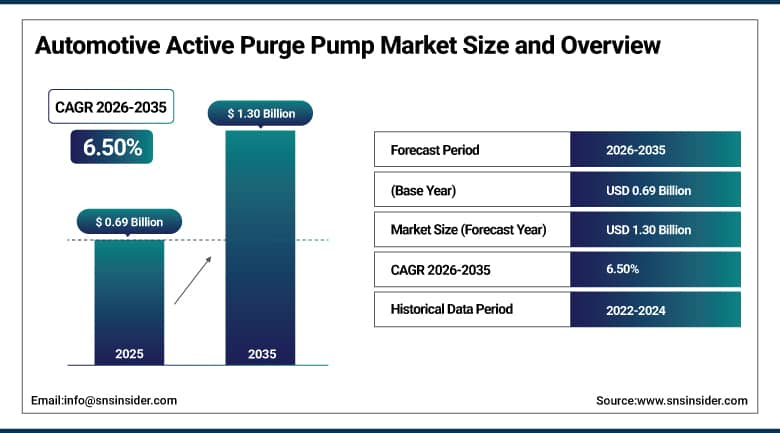
The Automotive Active Purge Pump Market was valued at USD 0.69 Billion in 2025 and is expected to reach USD 1.30 Billion by 2035, growing at a CAGR of 6.50% from 2026-2035.
The Automotive Active Purge Pump Market growth is largely being driven by increasingly stringent regulations pertaining to hydrocarbon evaporative emissions globally, which continue to necessitate that the fuel vapors that get collected in the charcoal canisters be actively purged into the intake system of the vehicle engine rather than just using passive or engine vacuum-powered purging. Active purge pumps, which make use of compact brushless DC motors, make it possible for the purging of the canister to take place at will without depending on engine operating conditions, which has become all the more important because of the increasingly fuel-efficient design of engines that produce minimal vacuum from the intake system while under partial load conditions.
Increased awareness of the issues of emissions and fuel efficiency among car owners and pressures by governments on the auto industry to cut down on hydrocarbon emissions have ensured that the demand continues to remain strong.
In 2024, Denso Corporation secured a multi-year supply agreement with Stellantis to provide active purge pumps for the automaker's next-generation vehicle platforms, supporting Stellantis' broader emission reduction targets.
To Get More Information On Automotive Active Purge Pump Market - Request Free Sample Report
Automotive Active Purge Pump Market Trends
-
Growing adoption of active purge pump technology in hybrid and plug-in hybrid vehicle platforms.
-
Rising integration of leak-detection sensors and diagnostics directly into compact pump housings.
-
Continued development of energy-optimized motors reducing current draw for plug-in hybrid applications.
-
Increasing regional localization of pump component manufacturing to reduce import duty and lead times.
-
Expanding aftermarket retrofit demand for emission control upgrades in aging vehicle fleets.
U.S. Automotive Active Purge Pump Market Outlook
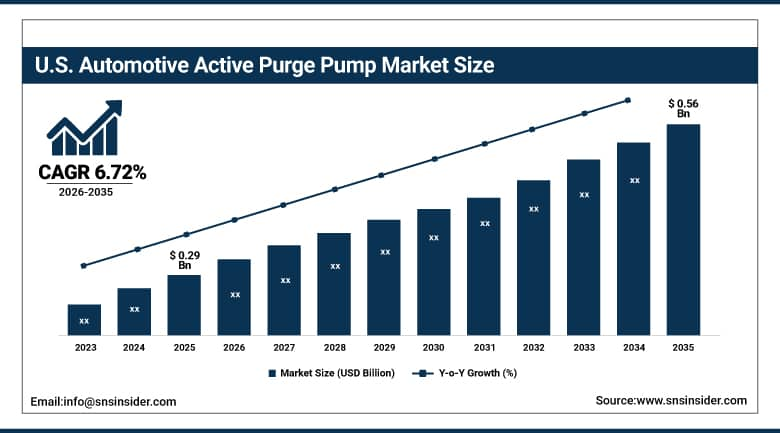
The U.S. Automotive Active Purge Pump Market was valued at USD 0.29 Billion in 2025 and is expected to reach USD 0.56 Billion by 2035, growing at a CAGR of 6.72% from 2026-2035.
The US automotive active purge pump market growth is being strengthened by the environmental protection agency's evaporation emissions regulations for gas powered cars, ongoing increase in hybrid cars manufacturing, and the high number of leading activities in emission control research and development taking place in the country. The domestic market is also influenced by close OEM partnerships between the active purge pump manufacturers and major automakers that have their head offices in North America. Growth in domestic plug-in hybrid car manufacturing will continue to favor demand for active purge pump technology that can operate during electric-only drives.
In 2024, Magna International opened a new research and development center in Michigan focused on advanced emission control technologies, including next-generation active purge pumps.
Automotive Active Purge Pump Market Segment Analysis
-
By Vehicle Type, the Passenger Vehicles segment dominated the Automotive Active Purge Pump Market with approximately 66.00% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Application, the Evaporative Emission Control Systems segment dominated the Automotive Active Purge Pump Market with approximately 55.0% share in 2025, while the Fuel Vapor Management segment is expected to be the fastest growing with a CAGR of approximately 8.2% during the 2026–2035 forecast period.
-
By Component, the DC Motor segment dominated the Automotive Active Purge Pump Market with approximately 41.27% share in 2025, while the Sensors segment is expected to be the fastest growing with a CAGR of approximately 6.13% during the forecast period.
-
By Sales Channel, the OEM segment dominated the Automotive Active Purge Pump Market with approximately 52.00% share in 2025, while the Aftermarket segment is the fastest growing with a CAGR of approximately 7.40%.
By Vehicle Type, Passenger Vehicles dominates and Commercial Vehicles grows fastest
Passenger Vehicles remain the dominant vehicle type segment within the Automotive Active Purge Pump Market, reflecting the sheer scale of global passenger vehicle production relative to commercial vehicle segments. This segment benefits from consistent active purge pump content across gasoline and hybrid passenger vehicle platforms, sustaining broad-based demand across a wide range of vehicle price points.
Commercial Vehicles are emerging as the fastest-growing vehicle type segment, driven by rising adoption of gasoline and hybrid powertrains in light commercial vehicle applications previously dominated by diesel engines. This segment focuses on durable pump designs suited to the higher-mileage duty cycles of commercial vehicle applications, positioning commercial vehicles to capture disproportionate growth as fleet operators increasingly adopt gasoline and hybrid light commercial vehicle platforms.
By Application, Fuel System dominates and Emission Control System grows fastest
Evaporative Emission Control Systems represent the dominant application segment within the Automotive Active Purge Pump Market, driven by increasingly stringent emission standards and the growing adoption of electronically controlled systems for precise fuel vapor and hydrocarbon management. Active purge pumps enable more accurate control of vapor flow within integrated evaporative emission architectures, supporting their increasing use across modern vehicle platforms and contributing to expanding demand during the forecast period.
Fuel Vapor Management applications are expected to represent the fastest-growing application segment, reflecting the pump’s fundamental role in controlling and routing fuel vapors from the charcoal canister into the engine intake for combustion. Demand is supported by the widespread integration of active purge systems across gasoline-powered and hybrid vehicles, where effective vapor management helps improve fuel efficiency while supporting compliance with evaporative emission regulations.
By Component, DC Motor dominates and Sensors grows fastest
DC Motor components have been established as the leading segment of the components category in the Automotive Active Purge Pump Market as they provide the essential actuation required in controlling the vapor flow within the pump assembly. This segment is expected to gain momentum owing to advancements in brushless DC motor technology which can provide reliable and efficient actuation within the harsh environments of the engine bay area.
Sensors have been identified as the segment with the highest growth rate. It can be attributed to the decreasing cost of sensors and their increasing use as leak detection and diagnostic sensors inside the small pumps. The segment is centered on providing real-time monitoring capabilities for onboard diagnostics and preventive maintenance purposes.
By Sales Channel, OEM dominates and Aftermarket grows fastest
OEM sales remain the dominant channel within the Automotive Active Purge Pump Market, reflecting the direct integration of active purge pumps into new-vehicle fuel system assemblies during original manufacturing. This segment benefits from long-term supply agreements between pump manufacturers and automakers, sustaining stable, high-volume demand tied directly to global gasoline and hybrid vehicle production levels.
The Aftermarket segment is emerging as the fastest-growing sales channel, driven by rising demand for retrofitting emission control systems in aging vehicle fleets, particularly in regions where regulatory upgrades are being phased in over time. This segment focuses on enabling vehicle owners and fleet operators to meet evolving evaporative emission standards without replacing entire fuel system assemblies, positioning aftermarket suppliers to capture growing demand during routine maintenance cycles.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.50% |
|
Asia Pacific |
China |
44.60% |
|
Europe |
Germany |
32.80% |
|
Latin America |
Brazil |
38.60% |
|
Middle East & Africa |
United Arab Emirates |
41.20% |
North America Automotive Active Purge Pump Market Insights
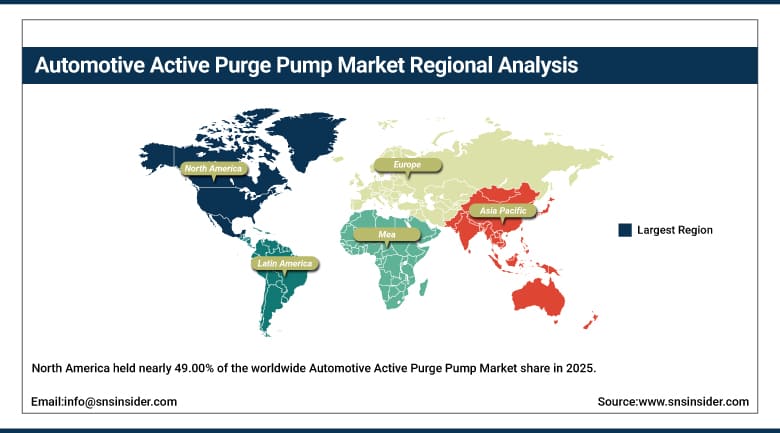
North America held nearly 49.00% of the worldwide Automotive Active Purge Pump Market share in 2025 on account of the existence of gasoline and hybrid car manufacturing in the region, as well as strict regulations related to evaporative emissions. North America has the highest level of demand coming from the United States on account of its strict EPA regulations and the presence of emission control leaders in the region.
The Canadian market provides the rest of the regional demand through its automotive value chain that includes vehicles assembled in North America. Growth in the production of hybrid and plug-in hybrid cars in Canada bolsters North America as the largest regional market for active purge pumps.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Active Purge Pump Market Insights
Asia Pacific is projected to expand at the fastest CAGR of approximately 7.50% across the Automotive Active Purge Pump Market during the 2026-2035 forecast period, driven by China's and India's stricter emission norms and rising vehicle production volumes. China represents the largest single contributor within the region, supported by its extensive gasoline and hybrid vehicle manufacturing base and continued tightening of domestic emission standards.
India and South Korea contribute additional regional demand, supported by expanding domestic vehicle production and rising regulatory emphasis on evaporative emission control. Japan's established automotive component manufacturing expertise, including localized production by leading suppliers, further reinforces Asia Pacific's position as the fastest-growing global market for automotive active purge pumps.
Europe Automotive Active Purge Pump Market Insights
Europe presents an important regional market for automotive active purge pumps, owing to Germany’s dominant automotive industry and its large number of luxury car makers along with leading emission systems providers like Continental and Robert Bosch. The representation of Germany within Europe is a result of both the fact that it has a dominating share in the production of automobiles in the region and that it is also an internal consumer of leading manufacturers of purge pumps.
Additional demand from France and the UK comes from their existing automotive manufacturing industries. Ongoing regulations within the European Union regarding evaporative emissions ensure sustained regional demand for purge pumps.
MEA & Latin America Automotive Active Purge Pump Market Insights
The Middle East & Africa region remains a smaller contributor to global demand, with growth supported by improving automotive infrastructure, increasing vehicle imports, and gradual implementation of emission control regulations across Gulf Cooperation Council markets such as the United Arab Emirates. South Africa continues to anchor demand on the African continent, supported by its comparatively more developed automotive assembly and export base.
Latin America's Automotive Active Purge Pump Market is led by Brazil, which accounts for the majority of regional demand on the strength of its large domestic vehicle assembly base and its role as a regional export hub for automakers operating in the region. Gradual tightening of regional emission standards continues to support steady regional demand growth.
Growth Drivers: Evaporative Emission Regulation and Fuel Efficiency Requirements
The rising trend of stricter hydrocarbon evaporative emissions regulations around the world forms the major factor that drives the Automotive Active Purge Pump Market, since the regulations require vehicles to use active purge systems rather than using vacuum-operated or passive purges alone. This trend has been augmented by the growing interest of automotive manufacturers in designing efficient engines with low intake vacuum under part loads.
Raising awareness about emissions and fuel efficiency among the owners of vehicles adds another driving force for the market, since the people prefer those vehicles that have advanced emission control systems. The growing use of active purge systems in hybrid and plug-in hybrid vehicles also drives the market, since these vehicles do not have adequate vacuum for vacuum-operated purging.
Restraints: Cost Sensitivity in Emerging Markets and Regulatory Fragmentation
Emerging economies where less stringent Stage 2 evaporative emission rules still apply represent a significant restraint on the Automotive Active Purge Pump Market, as automakers in these markets can continue relying on lower-cost passive purge systems while remaining compliant with local regulatory requirements. This dynamic limits the near-term addressable market for active purge pump technology to regions with more advanced emission standards.
Continued raw material and semiconductor component cost volatility for compact brushless DC motors and integrated sensors adds uncertainty to long-term manufacturing cost planning across the industry. The introduction of tariffs affecting cross-border automotive component trade has heightened cost considerations for market participants, prompting increased emphasis on regional sourcing and localized production strategies.
Opportunities: Hybrid Vehicle Integration and Sensor-Enabled Diagnostics Expansion
The increasing number of hybrid and plug-in hybrid cars offers an excellent opportunity for the Automotive Active Purge Pump Market, as there is a growing need for active purge systems that are able to function regardless of whether the engine vacuum is available. Companies that are able to provide proven energy efficient purge pumps that work specifically for hybrids are expected to get the most market share as the number of hybrid cars continues to grow.
An increase in the number of leak detection sensors and diagnostics that are built into compact housing provides an excellent long-term opportunity for suppliers to diversify into higher value emission monitoring systems that include sensors. With an increasing emphasis on emission monitoring system by the car manufacturers, companies that have already mastered sensors integration are expected to have the greatest market share.
Recent Developments
-
2024: Valeo unveiled a new compact active purge pump optimized for electric vehicles, aiming to enhance evaporative emission control in battery electric and hybrid vehicle models.
-
2025: Hitachi Astemo entered into a strategic partnership with Hyundai Motor Company to co-develop advanced active purge pump systems for upcoming vehicle models.
-
2025: GMB Korea localized magnet and motor lamination production for its active purge pump components, eliminating import duty and reducing lead times for Hyundai and Kia vehicle programs.
Automotive Active Purge Pump Companies are:
-
Continental AG
-
Denso Corporation
-
Robert Bosch GmbH
-
Schaeffler Group
-
Johnson Electric Holdings Limited
-
Aisan Industry Co., Ltd.
-
Hitachi Astemo, Ltd.
-
Forvia SE
-
TI Fluid Systems plc
-
Mann+Hummel GmbH
-
Mikuni Corporation
-
Stant Corporation
-
Kautex Textron GmbH & Co. KG
-
Yachiyo Industry Co., Ltd.
-
Walbro LLC
-
Magna International Inc.
-
Valeo S.A.
-
GMB Korea Co., Ltd.
Automotive Active Purge Pump Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 0.69 Billion |
| Market Size by 2035 | USD 1.30 Billion |
| CAGR | CAGR of 6.50% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Application (Fuel Vapor Management, Evaporative Emission Control Systems, Engine Air Management, Others) • By Vehicle Type (Passenger Vehicles and Commercial Vehicles) • By Component (DC Motor, Sensors, Housing, Actuators, Valves, Others) • By Sales Channel (OEM and Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Continental AG; Denso Corporation; Robert Bosch GmbH; Schaeffler Group; Johnson Electric Holdings Limited; MAHLE GmbH; Aisan Industry Co., Ltd.; Hitachi Astemo, Ltd.; Forvia SE; TI Fluid Systems plc; Mann+Hummel GmbH; Mikuni Corporation; Stant Corporation; Kautex Textron GmbH & Co. KG; Plastic Omnium SE; Yachiyo Industry Co., Ltd.; Walbro LLC; Magna International Inc.; Valeo S.A.; GMB Korea Co., Ltd. |
Frequently Asked Questions
Leading companies in the Automotive Active Purge Pump Market include Continental, Denso, Robert Bosch, Schaeffler Group, and Johnson Electric, among others.
Key opportunities include continued growth in hybrid and plug-in hybrid vehicle production requiring active purge technology, and rising integration of leak-detection sensors and diagnostics into compact pump housings.
Increasingly stringent hydrocarbon evaporative emission regulations worldwide, combined with automakers' pursuit of more fuel-efficient engine designs, is the major factor driving market growth.
The Passenger Vehicles segment dominated the Automotive Active Purge Pump Market with approximately 66.00% share in 2025.
North America dominated the Automotive Active Purge Pump Market in 2025 with approximately 49.00% share, reflecting the region's established gasoline and hybrid vehicle production base, led by the United States.
