
Automotive Wireless EV Charging Market Report Scope & Overview:
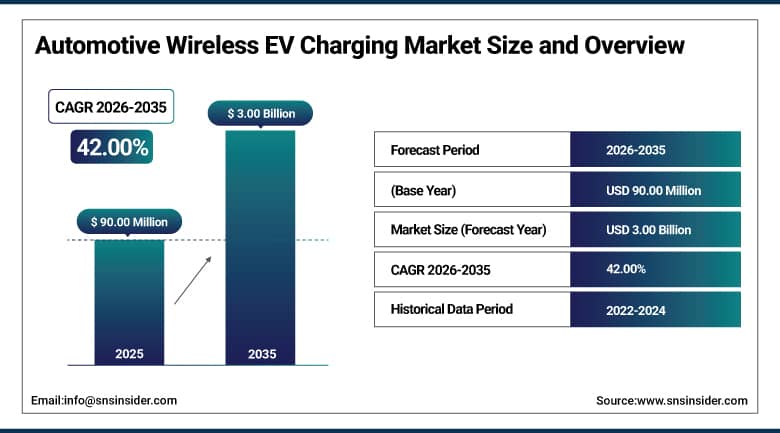
The Automotive Wireless EV Charging Market was valued at USD 90.00 Million in 2025 and is expected to reach USD 3.00 Billion by 2035, growing at a CAGR of 42.00% from 2026-2035.
The Automotive Wireless EV Charging Market growth is being driven primarily by consumer demand for convenience that removes cable hassles and enables contactless power transfer, a capability that integrates naturally with smart vehicles, smart homes, and automated parking systems already gaining traction across the broader automotive industry. Fleet operators are emerging as a particularly compelling early adopter segment, since wireless charging lowers labor costs and unlocks higher utilization rates by eliminating the time and physical effort a driver or technician would otherwise spend plugging in each vehicle, a benefit that continues to justify the technology's meaningfully higher capital expenditure relative to conventional plug-in charging.
Wireless EV charging is moving from demonstration projects toward real-world fleet applications. In Detroit, Electreon’s wireless charging road has operated for 18 months, with a Ford E-Transit shuttle charging both while driving and while stopped along a quarter-mile electrified road section. The project has also attracted UPS and Xos as partners, highlighting growing interest in hands-free charging for commercial fleets.
To Get More Information On Automotive Wireless EV Charging Market - Request Free Sample Report
Automotive Wireless EV Charging Market Trends
-
Rising development of dynamic in-road charging technology enabling electric vehicles to charge while in motion.
-
Growing fleet operator adoption of wireless depot charging reducing labor costs and improving vehicle utilization rates.
-
Expanding collaboration between automakers and research institutes accelerating wireless charging standardization efforts.
-
Increasing integration of wireless charging with autonomous vehicle systems and smart parking infrastructure.
-
Growing commercialization momentum as vehicle manufacturers transition from prototyping toward production-ready wireless charging systems.
-
Rising state transportation department programs researching electrified highway infrastructure supporting dynamic charging corridors.
U.S. Automotive Wireless EV Charging Market Outlook
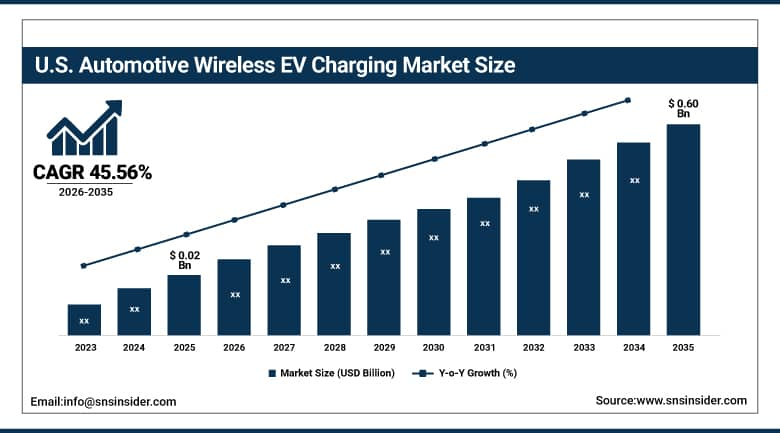
The U.S. Automotive Wireless EV Charging Market was valued at USD 0.02 Billion in 2025 and is expected to reach USD 0.60 Billion by 2035, growing at a CAGR of 45.56% from 2026-2035.
Growth of the U.S. Automotive Wireless EV Charging Market will keep on being fuelled by various research projects undertaken by universities with regard to electrification of highways, as well as trials run by state transportation departments in order to explore possibilities of dynamic road charging of vehicles in interstate locations. Increasing popularity of the technology among businesses which operate fleet of vehicles because of its potential to save labor costs and enhance turnaround times of vehicles also fuels domestic demand.
The U.S. Department of Transportation has supported wireless EV charging through the Joint Office of Energy and Transportation, including projects evaluating dynamic wireless charging on roadways. In Detroit, Electreon’s wireless charging roadway project has demonstrated charging for an electric shuttle while driving and while stopped, providing a U.S. test case for hands-free charging in commercial and public transport applications.
Automotive Wireless EV Charging Market Segment Analysis
-
By Charging Type, the Static Wireless Charging segment dominated the Automotive Wireless EV Charging Market with approximately 71.85% share in 2025, while the Dynamic Wireless Charging segment is the fastest growing with a CAGR of approximately 52.40%.
-
By Power Supply, the Up to 11 kW segment dominated the Automotive Wireless EV Charging Market with approximately 57.80% share in 2025, while the Above 50 kW segment is the fastest growing with a CAGR of approximately 58.80%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive Wireless EV Charging Market with approximately 65.20% share in 2025, while the Commercial Vehicles segment is the fastest growing with a CAGR of approximately 48.60%.
-
By Installation, the Home Charging segment dominated the Automotive Wireless EV Charging Market with approximately 62.40% share in 2025, while the Commercial Charging Stations segment is the fastest growing with a CAGR of approximately 47.80%.
By Charging Type, Static Wireless Charging Dominates the Automotive Wireless EV Charging Market and Dynamic Wireless Charging Grows Fastest
Static wireless charging continues to lead the charging-type segment, owing to simple installation in garages, parking lots, workplaces, and fleet yards that requires no modification to existing road infrastructure and lets vehicle owners adopt the technology with minimal upfront disruption. Highway authorities piloting these corridors are focusing initial deployment on high-traffic commercial routes, where the infrastructure investment can be justified by serving the greatest possible volume of passing vehicles.
Dynamic wireless charging represents the fastest-growing charging-type category, driven by development of in-road technology capable of charging electric vehicles while they remain in motion. Growing university and state transportation department research into electrified highway corridors continues to reinforce this segment's accelerating adoption despite its substantially higher infrastructure investment requirements.
By Power Supply, Up to 11 kW Dominates the Automotive Wireless EV Charging Market and Above 50 kW Grows Fastest
Systems rated up to 11 kW continue to dominate the power-supply segment, reflecting residential and light commercial applications where available electrical infrastructure and typical overnight charging windows align well with this power range's practical capabilities. Public transit agencies in particular are emerging as early adopters of this higher power tier, since electric buses require rapid charging turnaround between routes that lower-power systems simply cannot support.
Systems rated above 50 kW represent the fastest-growing power-supply category, as commercial applications increasingly demand rapid charging capability suited to fleet depot operations and high-utilization commercial vehicles that cannot tolerate extended overnight charging windows. Growing commercial fleet electrification continues to reinforce this segment's accelerating adoption.
By Vehicle Type, Passenger Cars Dominates the Automotive Wireless EV Charging Market and Commercial Vehicles Grows Fastest
Passenger cars continue to dominate the vehicle-type segment, consistent with their outsized share of overall electric vehicle sales relative to commercial vehicle categories and sustained consumer interest in the convenience wireless charging offers for daily home and workplace use. Transit authorities piloting wireless bus charging programs are reporting meaningful reductions in driver downtime, a benefit that continues to attract additional municipal and regional transit investment.
Commercial vehicles, including buses and coaches, represent the fastest-growing vehicle-type category, as fleet operators increasingly recognize wireless depot charging's ability to reduce labor costs and unlock higher vehicle utilization rates across demanding daily operating schedules.
By Installation, Home Charging Dominates the Automotive Wireless EV Charging Market and Commercial Charging Stations Grows Fastest
Residential installation of wireless chargers remains the most popular for installation, considering that most electric car owners prefer charging overnight from their residence where the wireless charging pad provides greater convenience compared to plugging in the cord manually. Additionally, shopping centers and corporate facilities are slowly adding commercial wireless chargers as they realize the attractiveness of such a device to EV owners who require an effortless charging experience in the course of doing tasks.
The commercial charging station is the fastest growing installation category, attributed to growing deployments in fleet depots and public parking as commercial companies realize the efficiency and benefits of wireless charging.
Regional Insights
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Europe |
Germany |
24.60% |
|
Asia Pacific |
China |
68.40% |
|
North America |
United States |
79.80% |
|
Latin America |
Brazil |
26.40% |
|
Middle East & Africa |
UAE |
29.60% |
Europe Automotive Wireless EV Charging Market Insights
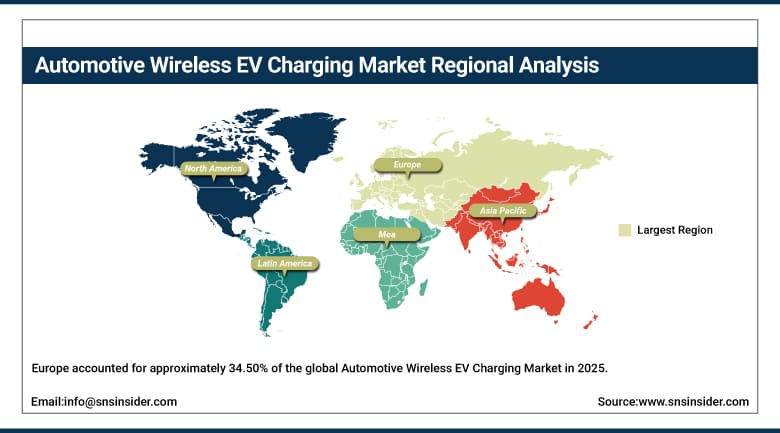
Europe accounted for approximately 34.50% of the global Automotive Wireless EV Charging Market in 2025, making it the largest regional market, driven by high adoption rates among premium automobile companies, sustained investment in electrified transport research, and a favorable automotive supplier base spanning multiple national markets. Italy and the Netherlands contribute additional regional demand, supported by growing EV adoption and expanding automotive research collaboration across the broader European Union market.
Germany represents the largest single contributor within the region, with vehicle manufacturers actively transitioning from prototyping toward commercialization of wireless charging technology. France and the United Kingdom contribute additional regional demand tied to their respective domestic automotive research and manufacturing sectors.
Get Customized Report as Per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Wireless EV Charging Market Insights
The Asia Pacific region holds around 26.75% of the global market share in the Automotive Wireless EV Charging market in 2025 and is expected to be the leading growth region at a CAGR of 48.65% during the forecast period from 2026 to 2035. It is due to the large production base of electric vehicles in China, development in wireless charging standards and urbanization. There are also incentives offered by governments in developing their own wireless charging components and closing the gap in terms of technology with their western counterparts.
China has emerged as the major contributor in the region owing to its development in charging component industry and investments by government in electric vehicles. Japan and South Korea are other contributors in the region on account of their expertise in automotive manufacturing technology.
North America Automotive Wireless EV Charging Market Insights
North America accounted for approximately 28.40% of the global Automotive Wireless EV Charging Market in 2025, driven by research initiatives from universities studying electrified highways, programs implemented by state transportation departments, and increased interest among commercial fleets in depot charging solutions. Growing consumer awareness of wireless charging technology, driven partly by media coverage of pilot programs, continues to build domestic demand even ahead of widespread commercial availability.
The United States represents the substantial majority of regional demand, while Canada and Mexico contribute additional demand through their participation in North American automotive research and manufacturing supply chains.
MEA & Latin America Automotive Wireless EV Charging Market Insights
Middle East & Africa represents an emerging market with the UAE contributing the most to this region due to electric vehicle adoption and infrastructure investment that is linked to economic diversification efforts. The Saudi Arabian market is also following the same pattern with investments in electric vehicle infrastructure in addition to overall economic diversification efforts within the Gulf countries.
In Latin America, the main contributor is Brazil with continued domestic electric vehicle adoption that has helped develop the regional market. There is also contribution from Mexico and Argentina due to domestic automotive manufacturing activities in these countries.
Growth Drivers: Consumer Convenience and Fleet Utilization
Consumer demand for convenience that removes cable hassles and enables contactless power transfer represents the principal driver of market growth, as wireless charging integrates naturally with smart vehicles, smart homes, and automated parking systems gaining traction across the broader automotive industry. Growing collaboration between automakers and research institutes continues to accelerate development of both stationary and in-road dynamic charging technologies, expanding the range of viable near-term use cases.
Fleet operator interest in reduced labor costs and higher vehicle utilization rates provides an additional significant source of growth, as wireless depot charging eliminates the time and effort otherwise spent manually connecting each vehicle. Growing collaboration between automakers and research institutes further reinforces this underlying demand trend.
Restraints: High Infrastructure Costs and Technology Immaturity
The substantially higher capital expenditure required for wireless charging infrastructure relative to conventional plug-in systems represents a significant restraint, as both static pad installation and especially dynamic in-road technology demand meaningful upfront investment before returns materialize. Limited standardization across manufacturers continues to complicate cross-brand compatibility, a challenge that echoes the early years of conventional plug-in charging before universal connector standards emerged.
The technology's relative immaturity compared to established plug-in charging standards adds a further restraint, as limited standardization across manufacturers and ongoing efficiency optimization work continue to slow broader commercial adoption beyond early pilot deployments.
Opportunities: Dynamic Charging Corridors and Commercial Fleet Electrification
Continued development of dynamic in-road charging corridors presents a substantial growth opportunity, as successful electrified highway pilot programs could fundamentally reshape how electric vehicles are charged during longer journeys rather than requiring dedicated stops. Suppliers developing high-power wireless solutions specifically engineered for buses and delivery vans are positioned to capture meaningful share as municipal and commercial fleet electrification programs continue expanding.
Commercial fleet electrification represents a further opportunity, as suppliers developing high-power wireless depot charging solutions specifically engineered for buses, delivery vans, and other commercial vehicles are positioned to capture meaningful share as fleet operators increasingly prioritize utilization efficiency.
Recent Developments
-
In March 2026, Electreon completed its acquisition of InductEV, combining Electreon’s dynamic and stationary wireless charging technologies with InductEV’s high-power wireless charging systems for heavy-duty vehicles. The combined portfolio covers passenger vehicles, delivery vans, buses, and heavy-duty trucks.
-
In 2026, WiTricity completed a new research and development laboratory in Stuart, Florida, expanding its capabilities for automotive wireless charging integration, testing, and customization. The facility supports systems ranging from 7.2 kW to 50 kW for passenger EVs, autonomous vehicles, robotaxis, and fleet applications.
-
In December 2025, Infineon Technologies announced an agreement to supply customized silicon-carbide power modules to Electreon for its dynamic wireless EV charging technology. The SiC modules are designed to increase power density in Electreon’s in-road charging systems for buses, trucks, and other electric vehicles.
Automotive Wireless EV Charging Companies are:
-
WiTricity Corporation
-
Tesla, Inc.
-
Toyota Motor Corporation
-
Toshiba Corporation
-
Momentum Dynamics Corporation
-
BYD Company Ltd.
-
Evatran Group Inc. (Plugless Power)
-
InvisPower
-
Continental AG
-
Robert Bosch GmbH
-
Qualcomm Incorporated
-
Powermat Technologies Ltd.
-
Elix Wireless
-
HEVO Inc.
-
ENRX (IPT Technology GmbH)
-
Wireless Advanced Vehicle Electrification, Inc.
-
Mahle GmbH
-
InductEV, Inc.
Automotive Wireless EV Charging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 90.00 Million |
| Market Size by 2035 | USD 3.00 Billion |
| CAGR | CAGR of 42.00% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Charging Type (Static Wireless Charging, Dynamic Wireless Charging) • by Technology (Inductive Power Transfer, Magnetic Resonance Coupling, Capacitive Power Transfer) • by Power Supply (Up to 11 kW, 11-50 kW, Above 50 kW) • by Vehicle Type (Passenger Cars, Commercial Vehicles, Two-Wheelers) • by Installation (Home Charging, Commercial Charging Stations) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | WiTricity Corporation, Tesla, Inc., Toyota Motor Corporation, Toshiba Corporation, ZTE Corporation, Momentum Dynamics Corporation, BYD Company Ltd., Evatran Group Inc.(Plugless Power), InvisPower, Continental AG, Robert Bosch GmbH, Qualcomm Incorporated, Powermat Technologies Ltd., Texas Instruments Inc., Elix Wireless, HEVO Inc., ENRX (IPT Technology GmbH), Wireless Advanced Vehicle Electrification, Inc., Mahle GmbH, InductEV, Inc. |
Frequently Asked Questions
Key players include WiTricity Corporation, Tesla, Inc., Toyota Motor Corporation, Toshiba Corporation, and Momentum Dynamics Corporation, among other leading wireless charging technology developers.
Continued development of dynamic in-road charging corridors and commercial fleet electrification represent the primary opportunities.
Growth is primarily driven by consumer demand for convenience combined with fleet operator interest in reduced labor costs and higher vehicle utilization rates.
By Charging Type, Static Wireless Charging dominated the market with approximately 71.85% share in 2025, owing to simple installation in garages, parking lots, and fleet yards.
Europe dominated the market with approximately 34.50% share in 2025, driven by high adoption rates among premium automobile companies and sustained research investment.
