
Automotive Brake Shoe Market Report Scope & Overview:
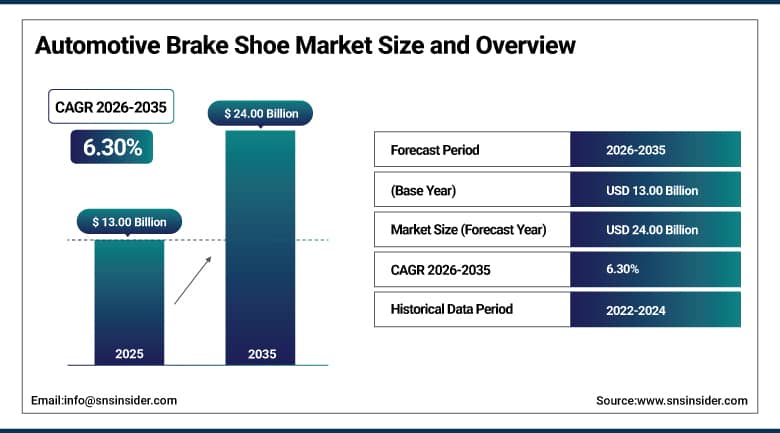
The Automotive Brake Shoe Market was valued at USD 13.00 Billion in 2025 and is expected to reach USD 24.00 Billion by 2035, growing at a CAGR of 6.30% from 2026–2035.
A brake shoe is a curved piece of metal that transports the brake lining inside a vehicle's drum brake system, pressed outward against the inside of the brake drum during braking so that friction between the lining and drum surface slows the wheel, with the resulting energy lost as heat. Leading/trailing, twin leading, and duo-servo are the three main drum brake shoe configurations found in vehicles, and all three types are self-energizing in at least one direction, meaning the drum's own rotation helps intensify the braking force once contact begins. The market continues growing steadily as increasing vehicle production, rising safety standards, and technological advancements in brake systems, particularly amid the shift toward electric and hybrid vehicles, keep reinforcing demand.
Environmental regulations limiting asbestos use continue accelerating a genuine material shift across the industry, pushing manufacturers toward composite and coated brake shoe technologies that eliminate the health and environmental liabilities older asbestos-based friction linings once carried. That regulatory-driven transition has become one of the more consequential engineering shifts in the category, since replacing a decades-old friction material means re-validating braking performance, wear characteristics, and noise behavior essentially from scratch rather than simply swapping one ingredient for another.
To Get More Information On Automotive Brake Shoe Market - Request Free Sample Report
Automotive Brake Shoe Market Trends
-
Rising adoption of composite and coated brake shoe technologies as environmental regulations continue limiting conventional asbestos-based friction materials
-
Growing integration of 3D printing and smart technology enhancing brake shoe manufacturing precision and performance monitoring capability
-
Increasing development of lightweight braking system components supporting broader vehicle fuel efficiency and electric vehicle range goals
-
Expanding organic fiber development and continuous friction material innovation improving brake shoe durability and consistency
-
Growing well-organized aftermarket industry in emerging economies, supported by high vehicle penetration and accessible replacement parts
-
Rising demand for optimized safety systems, with technology increasingly helping manufacturers fine-tune braking performance across vehicle categories
U.S. Automotive Brake Shoe Market Outlook
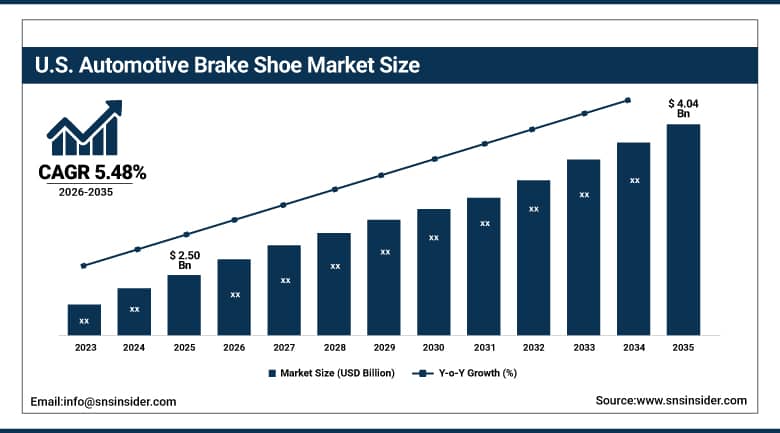
The U.S. Automotive Brake Shoe Market was valued at approximately USD 2.50 Billion in 2025 and is expected to reach approximately USD 4.04 Billion by 2035, growing at a CAGR of approximately 5.48%.
Demand in the United States is anchored by rising safety standards and continued vehicle production, alongside a well-organized aftermarket industry supported by high automobile penetration, accessible parts distribution, and established service station networks nationwide. Technological advancements in brake systems, particularly with the shift toward electric and hybrid vehicles, continue reshaping domestic manufacturer priorities, as electrified drivetrains increasingly pair regenerative braking with conventional friction systems requiring different wear and heat-management characteristics. Growing socio-economic advancement continues driving preference for quality aftermarket goods across the domestic replacement parts market.
Major American and multinational brake component suppliers, including Bosch, Ford, Federal-Mogul, and ACDelco, continue focusing on strategy-building models to strengthen their product portfolios and expand business across the domestic market. That competitive focus on portfolio breadth reflects how brake shoes remain a genuinely essential safety component even as automakers increasingly favor disc brakes over drum brakes for front-axle applications, since drum brake shoes remain standard equipment on rear axles across a substantial share of new passenger vehicles and the vast majority of the existing vehicle parc still on American roads.
Automotive Brake Shoe Market Segment Analysis
-
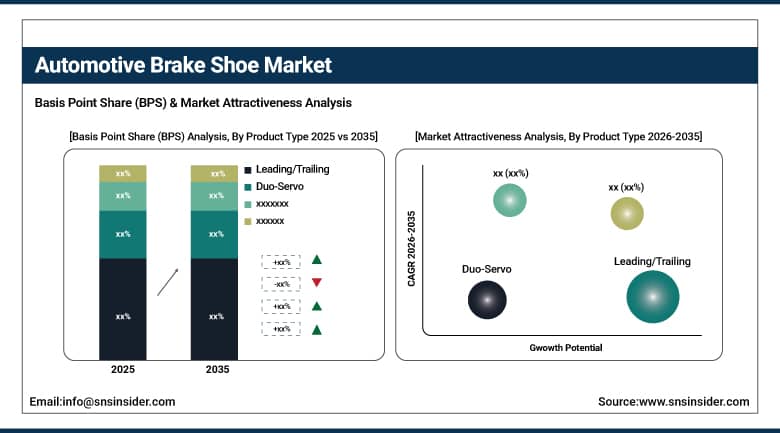
By Product Type, the Leading/Trailing segment dominated the Automotive Brake Shoe Market with approximately 52.40% share in 2025, while the Duo-Servo segment is the fastest growing with a CAGR of approximately 7.60%.
-
By Material, the Semi-Metallic segment dominated the Automotive Brake Shoe Market with approximately 46.60% share in 2025, while the Ceramic/Composite segment is the fastest growing with a CAGR of approximately 8.20%.
-
By Vehicle Type, the Passenger Cars segment dominated the Automotive Brake Shoe Market with approximately 58.60% share in 2025, and is also the fastest growing with a CAGR of approximately 7.40%.
-
By Sales Channel, the Aftermarket segment dominated the Automotive Brake Shoe Market with approximately 57.80% share in 2025, and is also the fastest growing with a CAGR of approximately 7.20%.
By Product Type, Leading/Trailing dominates, Duo-Servo grows fastest
The leading/trailing configuration accounted for the highest percentage of the product-type segment in 2025 and is set to maintain its position as the traditional type of drum brakes that is incorporated into the construction of most passenger vehicles and light commercial vehicles because of their reliable and effective braking capability. It is for this reason that leading/trailing remains the biggest selling product-type in the overall automotive brake shoe market.
The duo-servo product-type segment is the fastest-growing one owing to its self-energizing nature in both directions, meaning that it provides increased braking efficiency compared to other types. Increasing demand for improved safety in commercial and heavy-duty vehicles continues driving duo-servo product-type sales at a faster-than-average pace in comparison to the overall, leading/trailing-driven product-type segment.
By Material, Semi-Metallic dominates, Ceramic/Composite grows fastest
Semi-metallic brake shoe materials held the largest share of the material segment in 2025, valued for their balance of durability, heat dissipation, and cost-effectiveness across a wide range of everyday driving conditions and vehicle categories. That balance of performance and affordability keeps semi-metallic materials the dominant material choice across the broader automotive brake shoe market.
Ceramic and composite materials are growing fastest as environmental regulations continue limiting asbestos use and manufacturers increasingly adopt these alternatives for their reduced noise, lower dust generation, and genuinely competitive braking performance relative to older friction materials. The development of organic fibers and regular introduction of innovations in braking systems continue reinforcing this above-average growth trajectory relative to the broader, semi-metallic-dominated material mix.
By Vehicle Type, Passenger Cars dominates and grows fastest
Passenger cars held the largest share of the vehicle-type segment in 2025, reflecting the sheer scale of global passenger vehicle production and sales relative to commercial vehicle output in any given year, with drum brake shoes remaining standard rear-axle equipment across a substantial share of passenger vehicles worldwide. That production and sales scale keeps passenger cars the dominant vehicle-type category across the broader automotive brake shoe market.
Passenger cars are also the fastest-growing vehicle-type segment as rising per capita disposable income levels and electro-mobility developments continue expanding new vehicle sales across both developed and emerging markets simultaneously. That combination of continued dominance and above-average growth reflects the segment's sheer scale advantage over commercial vehicle applications, which grow steadily but from a smaller overall base.
By Sales Channel, Aftermarket dominates and grows fastest
The aftermarket segment accounted for the largest share of the sales-channel segment in 2025, supported by the presence of a well-organized aftermarket industry in emerging countries, high penetration of automobiles with easy accessibility of parts, low cost, expert technical teams, and availability of good service facilities. That combination of accessibility and established service infrastructure keeps the aftermarket the dominant sales channel across the broader automotive brake shoe market.
The aftermarket is also growing fastest, driven by growing socio-economic advancement and a growing preference for aftermarket goods in both emerging and developed economies, as consumers increasingly favor cost-effective replacement parts over OEM-sourced components. Regular brake shoe wear and replacement cycles across the existing global vehicle parc continue reinforcing this above-average growth trajectory relative to the OEM sales channel.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
Asia Pacific |
China |
40.60% |
|
North America |
United States |
80.20% |
|
Europe |
Germany |
25.60% |
|
Latin America |
Brazil |
34.80% |
|
Middle East & Africa |
UAE |
29.60% |
Asia Pacific Automotive Brake Shoe Market Insights
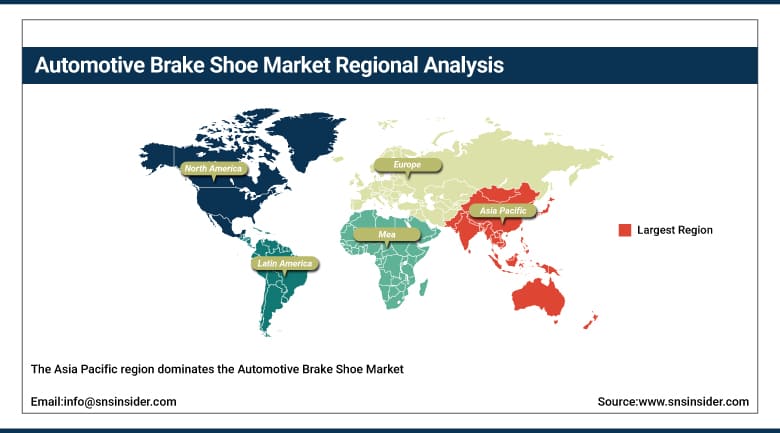
The Asia Pacific region dominates the Automotive Brake Shoe Market, and is also expected to grow at the fastest rate in the world, with major global automakers outsourcing parts and components from the region given its comparatively low manufacturing costs relative to other regions. Booming automotive manufacturing across China and India, combined with an increased automotive aftermarket, continues reinforcing this leading and accelerating position.
China's massive vehicle manufacturing base gives the region substantial baseline demand, while India's rapidly expanding automotive production sector is drawing significant new investment in brake component manufacturing capacity. Japan and South Korea represent more mature, technology-forward markets with established brake material standards, while Southeast Asian markets continue following a similar vehicle-production-driven growth trajectory as regional manufacturing infrastructure expands.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Automotive Brake Shoe Market Insights
North America constitutes an important market for the automotive brake shoe industry owing to increasing safety norms along with ongoing production of vehicles and a properly structured aftermarket that makes parts available and provides services. The USA alone forms the majority of the demand from this region, owing to increasing safety norms and vehicle production.
Canada adds to the demand through vehicle sales and the commercial trucking industry in Canada. Mexico is seeing an expansion in the market along with automotive manufacturing investments due to nearshoring. There are close supply links between North America, making many of the top manufacturers of brake components serve all the three countries.
Europe Automotive Brake Shoe Market Insights
Europe represents a mature, regulation-conscious automotive brake shoe market, shaped by environmental concerns and regulations limiting asbestos use that continue pushing manufacturers toward composite and coated brake shoe technologies. Germany anchors regional demand, home to a large automotive manufacturing base and several major brake component suppliers with deep engineering expertise.
France and Italy contribute meaningful volume as well, each with substantial automotive manufacturing sectors adapting to tightening EU environmental and safety requirements. Growing regional emphasis on organic fiber friction materials and continuous braking system innovation continues shaping product development across the region more directly than in most other global markets.
MEA & Latin America Automotive Brake Shoe Market Insights
The Middle East and Africa represent a smaller but developing automotive brake shoe market, with the UAE driving demand through growing vehicle sales and automotive retail investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader automotive manufacturing and vehicle ownership infrastructure development.
Latin America is a growing market led by Brazil, where expanding vehicle production and a growing commercial vehicle sector continue driving demand for automotive brake shoes. Mexico and Argentina contribute meaningful secondary demand, tied to their own growing automotive manufacturing sectors.
Market Dynamics
Growth Drivers: Rising vehicle production and safety standards fueling adoption
Increasing vehicle production is one of the clearest forces behind rising automotive brake shoe demand, as growing global vehicle output continues expanding the addressable market for drum brake components across both OEM and aftermarket channels simultaneously. Rising safety standards continue reinforcing this demand base, as regulatory bodies worldwide maintain stringent braking performance requirements that every vehicle, regardless of drivetrain type, must satisfy.
Technological advancements in brake systems add a second major driver, particularly with the shift towards electric and hybrid vehicles that require carefully engineered friction systems working alongside regenerative braking technology. Introducing breakthrough technology for the creation of lightweight braking systems, combined with rising per capita disposable income levels and electro-mobility developments, continues reinforcing this demand base across nearly every major automotive market.
Restraints: Disc brake substitution and asbestos regulation compliance costs limiting margin stability
Continued substitution of drum brakes with disc brake systems, particularly for front-axle applications across premium and mid-range vehicles, remains a genuine restraint, since disc brakes offer superior heat dissipation and stopping performance that many automakers increasingly specify even for standard trim levels. That structural shift continues limiting the addressable market for drum brake shoes specifically, even as they remain standard on rear axles across a substantial vehicle share.
Compliance costs associated with asbestos regulation add a further restraint, as manufacturers face genuine reformulation and re-validation investment navigating varying environmental and material safety standards across different jurisdictions simultaneously. That compliance burden falls disproportionately on smaller manufacturers without dedicated regulatory affairs and materials science capability built into their operations.
Opportunities: Composite material innovation and emerging market aftermarket expansion opening new growth avenues
Composite and ceramic material innovation offers manufacturers a genuine path to capturing premium business from automakers and consumers seeking reduced noise, lower dust generation, and asbestos-free friction performance without sacrificing braking effectiveness. Companies that build strong composite material engineering capability are positioned to capture disproportionate growth as regulatory and consumer pressure on legacy friction materials continues building.
Emerging market aftermarket expansion represents a second significant opportunity, as growing automobile penetration and increasingly well-organized aftermarket industries across developing economies continue expanding demand for accessible, cost-effective brake shoe replacement parts. Manufacturers that build genuine emerging-market distribution and service network capability are positioned to capture disproportionate growth as vehicle ownership continues expanding across these fast-growing regions.
Recent Developments:
-
In 2025, major suppliers, including Bosch and Ford, continued focusing on strategy-building models to strengthen their brake component product portfolios and expand business globally.
-
In 2025, multiple manufacturers continued integrating 3D printing and smart technology to enhance brake shoe manufacturing precision and performance monitoring capability.
-
In 2025, Federal-Mogul and Continental continued developing composite and coated brake shoe technologies in response to tightening asbestos-related environmental regulations.
-
In 2025, regional manufacturers across India and China continued expanding production capacity to serve growing domestic commercial vehicle and aftermarket demand.
Automotive Brake Shoe Market Key Players
-
Robert Bosch GmbH
-
Ford Motor Company
-
Continental AG
-
Federal-Mogul LLC
-
TRW Automotive
-
Delphi Technologies
-
Akebono Brake Industry Co., Ltd.
-
ACDelco
-
Meritor, Inc.
-
MAT Holdings, Inc.
-
Nisshinbo Holdings Inc.
-
MK Kashiyama & Co., Ltd.
-
Dura International
-
FBK Corporation
-
Brembo S.p.A.
-
ICER Brakes
-
Mando Corporation (HL Mando)
-
Sangsin Brake Co., Ltd.
-
Henan Wanxiang Auto Parts Co., Ltd.
-
Aisin Corporation
Automotive Brake Shoe Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 13.00 Billion |
| Market Size by 2035 | USD 24.00 Billion |
| CAGR | CAGR of 6.30% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • by Product Type (Leading/Trailing, Twin Leading, Duo-Servo) • by Material (Semi-Metallic, Ceramic/Composite, Others) • by Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles) • by Sales Channel (OEM, Aftermarket) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Robert Bosch GmbH, Ford Motor Company, Continental AG, Federal-Mogul LLC, TRW Automotive, Delphi Technologies, Akebono Brake Industry Co., Ltd., ACDelco, Meritor, Inc., MAT Holdings, Inc., Nisshinbo Holdings Inc., MK Kashiyama & Co., Ltd., Dura International, FBK Corporation, Brembo S.p.A., ICER Brakes, Mando Corporation (HL Mando), Sangsin Brake Co., Ltd., Henan Wanxiang Auto Parts Co., Ltd., Aisin Corporation |
Frequently Asked Questions
Leading companies include Robert Bosch GmbH, Ford Motor Company, Continental AG, Federal-Mogul LLC, and TRW Automotive, among other major brake component manufacturers.
Opportunities include composite and ceramic material innovation delivering asbestos-free friction performance and emerging market aftermarket expansion through accessible, cost-effective replacement parts distribution.
Growth is driven by increasing vehicle production, rising safety standards, and technological advancements in brake systems amid the shift toward electric and hybrid vehicles.
Leading/Trailing dominates by product type with approximately 52.40% share, Semi-Metallic dominates by material with roughly 46.60% share, and Passenger Cars dominates by vehicle type with about 58.60% share; Duo-Servo, Ceramic/Composite, and Passenger Cars are also among the fastest-growing segments within their respective categories, alongside the Aftermarket sales channel.
Asia Pacific is the largest and fastest-growing regional market, led by China, given the region's extensive automotive manufacturing base and comparatively low production costs.
