
Automotive Retread Tires Market Report Scope & Overview:
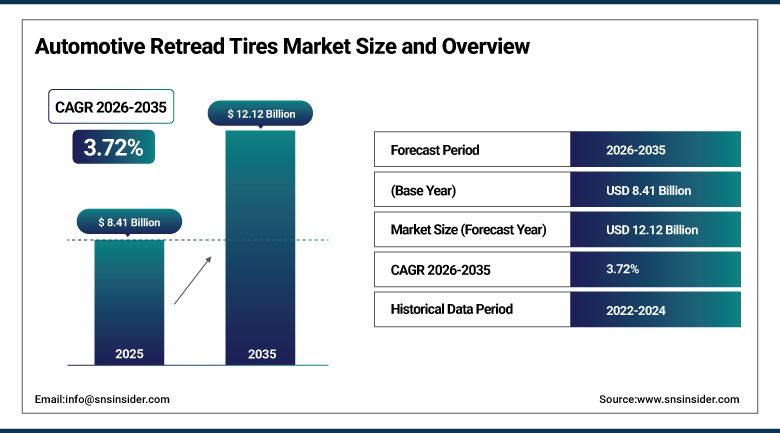
The Automotive Retread Tires Market was valued at USD 8.41 Billion in 2025 and is expected to reach USD 12.12 Billion by 2035, growing at a CAGR of 3.72% from 2026-2035.
The Automotive Retread Tires Market has been constantly growing because of the inherent cost effectiveness of the market, as a retreaded tire can be manufactured at much lower costs when compared to that of a new tire, without compromising on safety and performance, with tire costs accounting for almost 25% of the total costs of running a fleet of vehicles in commercial trucking. The policies adopted by the government for sustainability purposes have increased this cost-effectiveness demand further, as the government of the U.S. has come up with tax benefits for retreaded tires that help increase the process of recycling and reuse of material in the tire industry.
In January 2025, Continental extended the reach of its holistic ContiLifeCycle concept by launching two new Generation 5 tire lines, the Conti Eco Gen 5 for long-distance and regional haulage and the Conti Urban HA 5 for urban buses, both engineered with optimized rolling resistance and extended casing recyclability without compromising retread performance. The launch reflects a broader supplier strategy of designing new tires specifically for multi-life retreadability from the outset, rather than treating retreading as an afterthought applied to casings originally engineered only for single-life use, a design philosophy that is increasingly differentiating premium tire suppliers competing for long-term fleet casing management contracts.
To Get more information Automotive Retread Tires Market - Request Free Sample Report
Automotive Retread Tires Market Trends
- Growing supplier design of casings specifically engineered for multi-life retreadability from initial manufacture.
- Rising adoption of hot-retread premium programs offering performance comparable to new tires for long-haul fleets.
- Expanding development of retread tire ranges designed for the distinct load characteristics of electric commercial vehicles.
- Increasing government tax incentives promoting retreaded tire adoption as a recycling and sustainability measure.
- Continued investment in automation, inspection technology, and digital casing tracking across retreading facilities.
U.S. Automotive Retread Tires Market Outlook
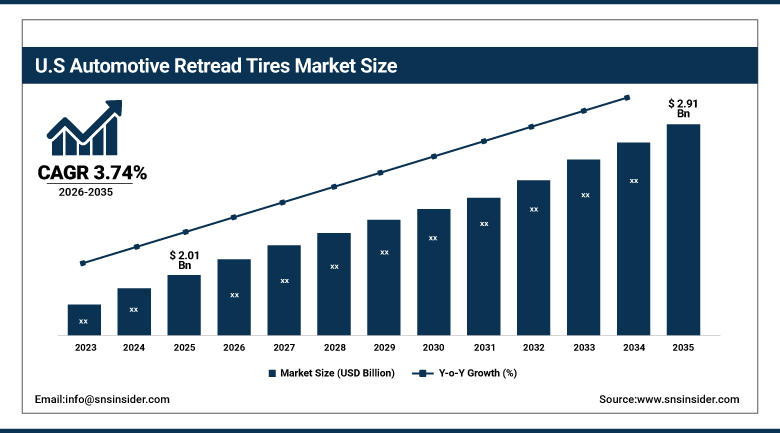
The U.S. Automotive Retread Tires Market was valued at USD 2.01 Billion in 2025 and is expected to reach USD 2.91 Billion by 2035, growing at a CAGR of 3.74% from 2026-2035.
The U.S. Automotive Retread Tires Market growth continues to be reinforced by federal tax incentives that promote retreaded tire adoption as a recycling and sustainability measure, alongside a large domestic commercial trucking fleet for which tire expense represents a significant share of total operating cost. Hot-retread premium programs are becoming more common due to the growing need for durability of casings and performance equivalent to that of new tires among long-haul fleets, while the existing Bandag, Michelin Retread Technologies, and Goodyear Certified Retreader programs remain key in retreading operations in the country.
In October 2025, Goodyear unveiled retreaded tire products specifically created for electric vehicles, taking into account the specific load and torque requirements of electric commercial trucks that differ from those of diesel trucks. The case provides an example of how local tire manufacturers take action to make retreading available to the expanding number of electric commercial trucks, making sure that the benefits provided by the technology will not be lost during the transition to electric vehicles.
Automotive Retread Tires Market Segment Analysis
- By Process Type, the Pre-Cure segment dominated the Automotive Retread Tires Market with approximately 66.90% share in 2025, while the Mold-Cure segment is the fastest growing with a CAGR of approximately 5.40%.
- By Sales Channel, the OEM Programs segment dominated the Automotive Retread Tires Market with approximately 83.45% share in 2025, while the Independent Service Providers segment is the fastest growing with a CAGR of approximately 5.65%.
- By Vehicle Type, the Light Commercial Vehicles segment dominated the Automotive Retread Tires Market with approximately 54.22% share in 2025, while the Heavy Commercial Vehicles segment is the fastest growing with a CAGR of approximately 5.15%.
- By End Use, the Long-Haul Freight segment dominated the Automotive Retread Tires Market with approximately 38.60% share in 2025, while the Urban Delivery segment is the fastest growing with a CAGR of approximately 5.85%.
By Process Type, Pre-Cure dominates, and Mold-Cure grows fastest
Pre-cure is the main type of process in the Automotive Retread Tires Market due to the fact that it can be processed in a flexible manner and has a shorter cycle time compared to the mold cure process, as it enables the application of tread rubber to tires of various sizes without a mold.
Mold-cure is emerging as the fastest-growing process type because there is increased demand from fleets that want retread tires with similar tread designs and performance capability compared to the OE tires. For the fleets that emphasize performance equivalency to new tires, this category emphasizes investment in molds that will enable unique tread design capabilities.
By Sales Channel, OEM Programs dominate, and Independent Service Providers grow fastest
OEM Programs remain the dominant sales channel, characterized by tire manufacturers' direct casing management and retread service agreements bundled with new tire sales, allowing fleet operators to work with a single accountable supplier across a tire's full multi-life service history.
Independent Service Providers are emerging as the fastest-growing sales channel, driven by cost-sensitive fleet segments seeking flexible pricing and localized service outside manufacturer-branded retread networks. As smaller regional fleets prioritize service responsiveness, this segment focuses strongly on building direct relationships with independent retreaders capable of faster turnaround than centralized OEM programs.
By Vehicle Type, Light Commercial Vehicles dominate, and Heavy Commercial Vehicles grow fastest
Light commercial vehicles remain the dominant vehicle-type segment, characterized by the rapidly expanding e-commerce and last-mile delivery sector, which relies on large fleets of vans and light trucks requiring robust, cost-effective retreaded tires able to withstand varied urban road conditions.
Heavy commercial vehicles are emerging rapidly as fleet operators seek to minimize operational costs through structured retread programs applied to long-haul trucks and buses. As construction and transport fleets prioritize casing value extraction, this segment focuses strongly on multi-life casing management programs that maximize the number of retread cycles a premium casing can support.
By End Use, Long-Haul Freight dominates, and Urban Delivery grows fastest
Long-haul freight remains the dominant end-use segment, characterized by high-mileage operating profiles that make tire replacement frequency, and therefore retread economics, a central factor in overall fleet operating cost management for interstate and cross-border trucking operations.
Urban delivery is emerging as the fastest-growing end-use segment, driven by the continued expansion of e-commerce-driven last-mile logistics networks that operate large fleets of light and medium-duty delivery vehicles. As delivery fleet operators prioritize cost control amid rising vehicle counts, this segment focuses strongly on shorter-cycle retread programs suited to the frequent stop-and-go duty cycles characteristic of urban delivery routes.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
71.50 |
|
Europe |
Germany |
29.85 |
|
Asia Pacific |
China |
39.60 |
|
Middle East & Africa |
United Arab Emirates |
33.75 |
|
Latin America |
Brazil |
49.20 |
North America Automotive Retread Tires Market Insights
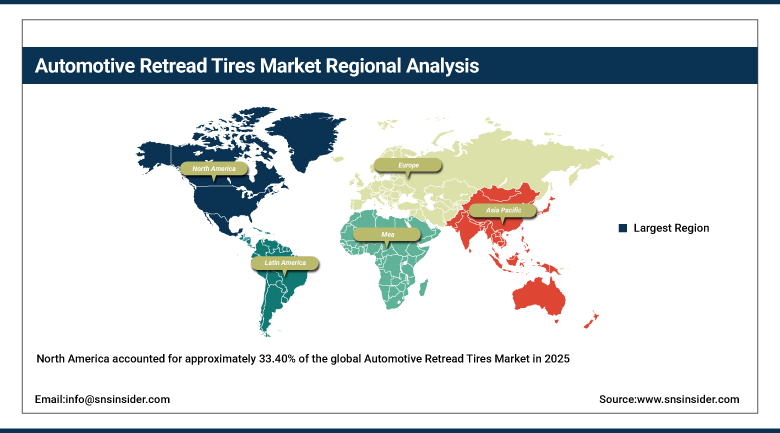
North America accounted for approximately 33.40% of the global Automotive Retread Tires Market in 2025, remaining the largest regional market on the strength of federal tax incentives promoting retreaded tire adoption and a large domestic commercial trucking fleet for which tire expense represents a significant share of total operating cost. The United States dominates regional demand, supported by established Bandag, Michelin Retread Technologies, and Goodyear Certified Retreader networks that collectively operate hundreds of retread plants across the country.
Among the fifty largest U.S. retreaders, the Bandag system accounts for the largest share of affiliated plants, followed by Michelin Retread Technologies and Goodyear Certified Retreaders, illustrating the degree to which branded retread networks structure the domestic competitive landscape. Canada contributes additional regional demand through its own commercial trucking sector, which similarly depends on cost-effective tire management across long-haul freight routes.
Get Customized Report as per Your Business Requirement - Enquiry Now
Asia Pacific Automotive Retread Tires Market Insights
Asia Pacific is projected to expand at a CAGR of approximately 5.90% from 2026 to 2035, the fastest of any region, driven by China's massive commercial trucking fleet and expanding freight volumes that support structured retread programs. China, ASEAN member states, and Mexico are expected to expand faster than mature markets as freight growth and cost-focused fleet operations reinforce retread adoption across the broader Asia-Pacific and North American nearshoring corridor.
The increase in the commercial vehicle fleet in India, which is backed up by the home-grown manufacturer MRF Limited and JK Tyre & Industries, is creating significant incremental regional demand owing to increasing prices of new tires. Japan and South Korea add regional demand through their well-developed commercial trucking industry with high retread quality standards.
Europe Automotive Retread Tires Market Insights
Europe represents a significant Automotive Retread Tires Market, shaped by stringent environmental regulation and a strong emphasis on circular-economy principles within fleet management practices. Germany leads regional demand, anchored by Continental's ContiLifeCycle program and its concentration of commercial vehicle OEMs requiring long-term casing management solutions.
France, Italy, and the United Kingdom contribute meaningful additional regional demand through their own commercial trucking and bus fleets, while continued EU-wide emphasis on tire recycling and sustainability reporting is expected to sustain steady retread adoption throughout the forecast period.
MEA & Latin America Automotive Retread Tires Market Insights
The Middle East & Africa Automotive Retread Tires Market is expanding due to the investments by the Gulf Cooperation Council nations in logistics and transportation networks, while the UAE leads in the region due to its position as an important freight transshipment point.
Latin America is led by Brazil, where a substantial domestic commercial vehicle fleet and cost-sensitive fleet operating environment continue to drive demand for retreaded tires as a lower-cost alternative to new tire purchases. Mexico contributes additional regional demand through its growing role as a nearshore logistics hub serving North American supply chains.
Market Dynamics
Growth Drivers: Fleet Cost Optimization and Government Sustainability Incentives
Optimization of fleet costs is the prime factor behind the success of the Automotive Retread Tires Market since retread tires are 30% to 50% cheaper than their brand new counterparts, and fleet operators have the ability to gain maximum benefit from high-quality casings through repeat retreading. In the trucking business, tire cost makes up a huge portion of operating cost.
Tax incentives by governments for sustainability are aiding this cost-based demand as retreading of tires is seen as an example of recycling through incentive programs, while other circular economy policies encourage fleet owners to keep casing life longer rather than buy new tires. This government support is giving visibility of demand to the retreading companies based on policy as well.
Restraints: Quality Perception and Casing Availability Constraints
Persistent consumer and fleet operator perception concerns regarding retreaded tire quality and safety, despite retreads delivering performance comparable to new tires under proper casing management, continue to constrain broader adoption, particularly in the passenger car segment where drivers tend to prioritize new tire purchases over retreads.
Casing availability constraints limit retread supply growth, since only tires meeting specific structural integrity standards can be safely retreaded, and rising new tire quality has in some cases reduced the number of casings reaching end of original tread life in condition suitable for multiple retread cycles, creating a structural ceiling on retread volume growth independent of demand.
Opportunities: Electric Fleet Retreading and Multi-Life Casing Design
The growing electrification of commercial vehicle fleets presents a significant opportunity for suppliers developing retread tire ranges engineered for the distinct load distribution and torque characteristics of electric trucks, allowing the cost and sustainability advantages of retreading to extend into an expanding segment of the commercial vehicle fleet.
Continued supplier investment in casings engineered from initial manufacture for multi-life retreadability presents a further opportunity to expand the addressable retread market, as tires designed explicitly for repeated retreading can support more retread cycles than casings originally engineered only for single-life use. Suppliers successfully commercializing multi-life casing programs are positioned to capture long-term fleet contracts that extend well beyond a single tire purchase transaction.
Recent Developments:
- 2026: Michelin unveiled NAZCA, an automated regrooving machine for truck, bus, and coach tires. The system uses laser scanning and algorithms to automate regrooving and can potentially increase workshop regrooving capacity by 30–50%. It complements Michelin’s REMIX retreading model.
- 2026: Vipal presented its V Super Hybrid technology at Tire Cologne 2026. Developed for mixed paved/unpaved operations, the technology focuses on durability, mileage performance and casing preservation; Vipal also showcased its EV-oriented DV-UMe tread on a retreaded tire.
- 2026: Pirelli North America launched its first closed-loop tire recycling initiative, working with Bolder Industries to convert scrap tires into recovered carbon black for use in new Pirelli tires.
Automotive Retread Tires Market Key Players are:
- Bridgestone Corporation
- Compagnie Générale des Établissements Michelin
- The Goodyear Tire & Rubber Company
- Continental AG
- Marangoni S.p.A.
- Pirelli & C. S.p.A.
- Nokian Tyres plc
- MRF Limited
- Kraiburg Austria GmbH & Co. KG
- JK Tyre & Industries Ltd.
- Vipal Rubber Corporation
- Trelleborg Wheel Systems
- Hankook Tire America Corp.
- Yokohama Tire Corporation
- Triangle Tire USA
- Oliver Rubber Company, LLC
- Kal Tire
- Recamic
- LKQ Corporation
- Bandag, LLC
Automotive Retread Tires Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 8.41 Billion |
| Market Size by 2035 | USD 12.12 Billion |
| CAGR | CAGR of 3.72% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Process Type (Pre-Cure, Mold-Cure) • By Sales Channel (OEM Programs, Independent Service Providers, Fleet Contracts, Others) • By Vehicle Type (Passenger Cars, Light Commercial Vehicles, Heavy Commercial Vehicles) • By End Use (Long-Haul Freight, Urban Delivery, Construction & Mining, Passenger Transport, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Bridgestone Corporation, Compagnie Générale des Établissements Michelin, The Goodyear Tire & Rubber Company, Continental AG, Marangoni S.p.A., Pirelli & C. S.p.A., Nokian Tyres plc, MRF Limited, Kraiburg Austria GmbH & Co. KG, JK Tyre & Industries Ltd., Vipal Rubber Corporation, Trelleborg Wheel Systems, Hankook Tire America Corp., Yokohama Tire Corporation, Triangle Tire USA, Oliver Rubber Company, LLC, Kal Tire, Recamic, LKQ Corporation, Bandag, LLC |
Frequently Asked Questions
Key players in the Automotive Retread Tires Market include Bridgestone Corporation, Michelin, The Goodyear Tire & Rubber Company, Continental AG, and Marangoni S.p.A., among others.
Key opportunities lie in retread tire ranges engineered for electric commercial vehicles, and in multi-life casing designs that extend a tire's retread cycles and support long-term fleet contracts.
Fleet cost optimization, as retreads typically cost 30% to 50% less than new tires, combined with government sustainability tax incentives, is the major growth factor.
By Process Type, the Pre-Cure segment dominated the Automotive Retread Tires Market with approximately 66.90% share in 2025.
North America dominated the Automotive Retread Tires Market with approximately 33.40% share in 2025, supported by federal tax incentives and a large domestic commercial trucking fleet.
