
Ballistic Protection Market Report Scope & Overview:
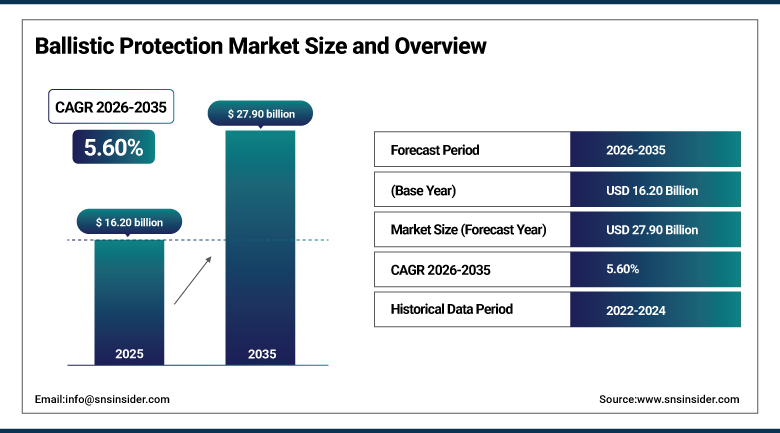
The Ballistic Protection Market was valued at USD 16.20 Billion in 2025 and is expected to reach USD 27.90 Billion by 2035, growing at a CAGR of 5.60% from 2026 to 2035.
The growth rate of the ballistic protection market is consistent due to the increasing number of geopolitical uncertainties and regional conflicts, leading to a requirement for improved ballistic protection in the defense and military industry. Ballistic protection refers to equipment which protects humans, vehicles, aircraft, ships, and fixed structures against projectiles such as bullets, fragments, shrapnel, and any other form of kinetic objects based on their capacity to absorb the energy transferred. In addition to that, factors such as the modernization of the army by various countries to counter new threats, increasing demand for protective clothing, armored vehicles, and defense infrastructure, and the rise in demand for modular ballistic protection systems are contributing to the growth of this market.
Military structures that used to be common are becoming less frequent; rather, ballistic panels, bulletproof kiosks, and glass, as well as shield units and armor barriers, are finding their way into civilian settings such as schools, religious centers, embassies, airports, and other public areas due to increased civilian threat exposure, indicating that the market is evolving structurally beyond its former military application base.
To Get more information Ballistic Protection Market - Request Free Sample Report
Ballistic Protection Market Trends
- Rising demand for lightweight, modular protection is driving innovation in multi-threat ballistic systems.
- Growing smart technology integration is improving situational awareness and safety in ballistic protection equipment.
- Increasing civilian and commercial adoption is expanding demand across schools, religious facilities, and private security.
- Expanding demand for multifunctional materials is combining ballistic, chemical, and thermal protection capabilities.
- Strategic partnerships are accelerating development of advanced and cost-effective ballistic protection solutions.
The U.S. Ballistic Protection Market Outlook
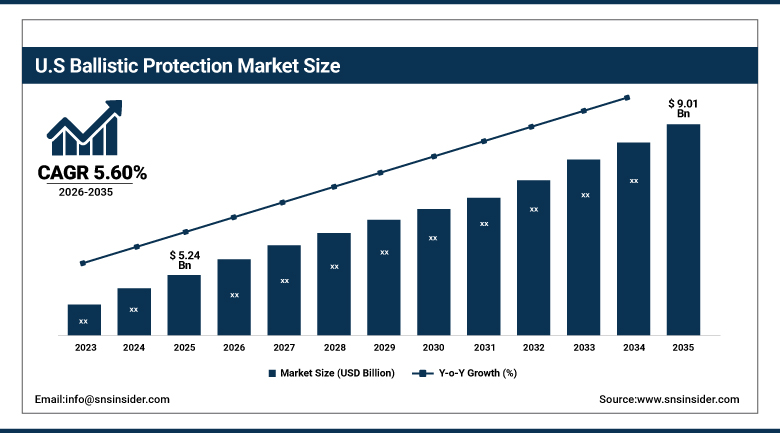
The U.S. Ballistic Protection Market was valued at USD 5.24 Billion in 2025 and is projected to reach USD 9.01 Billion by 2035, growing at a CAGR of 5.60% during 2026–2035.
Top defense organizations in the country, as well as those in law enforcement, are continuing to invest in ballistic protection in an effort to support ongoing modernization efforts and increased procurement of advanced ballistic gear, as well as armored vehicles and defense infrastructure. Increasing protection program expansion in the law enforcement community and increased civilian and commercial demand for portable ballistic protection gear, along with ongoing investment in research and development of ballistic materials, is continuing to fuel the demand for ballistic protection.
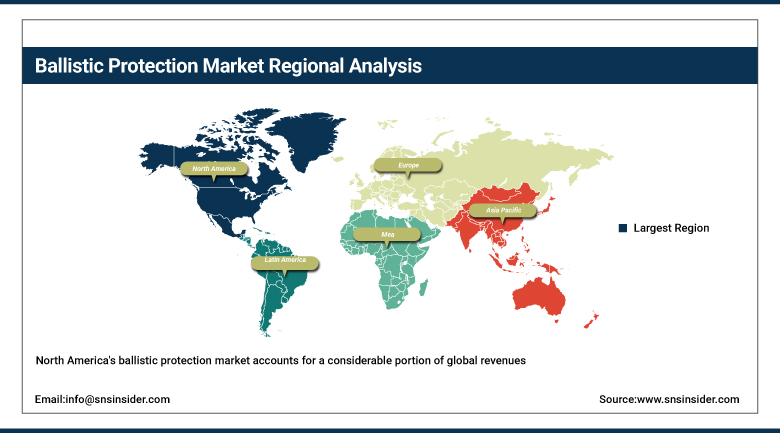
North America represents a significant share of ballistic protection market revenue, driven by advanced defense infrastructure and high procurement volumes from military, homeland security, and law enforcement agencies investing in continuous innovation and strategic collaborations across the domestic ballistic protection supply chain.
Ballistic Protection Market Segment Analysis
- By Product Type, spall & fragmentation protection dominated the ballistic protection market with a 38.60% share in 2025, while vehicle armor is the fastest-growing product type segment with a CAGR of 7.00% from 2026–2035.
- By Material Type, composites dominated the ballistic protection market with a 31.00% share in 2025, while ceramics is the fastest-growing material type segment with a CAGR of 7.50% from 2026–2035.
- By Application, land/ground forces dominated the ballistic protection market with a 44.60% share in 2025, while naval & marine platform is the fastest-growing application segment with a CAGR of 7.60% from 2026–2035.
- By End User, military dominated the ballistic protection market with a 68.90% share in 2025, while homeland security is the fastest-growing end user segment with a CAGR of 6.80% from 2026–2035.
By Product Type, spall & fragmentation protection dominated the ballistic protection market, while vehicle armor is the fastest-growing segment.
The spall & fragmentation protection segment held the largest market share in 2025. Spall and fragmentation protection remains the dominant product type category owing to its widespread deployment across military vehicles, naval vessels, and fixed installations, where preventing secondary fragmentation injuries from projectile impacts continues to represent a fundamental protective requirement across the majority of ballistic protection applications worldwide.
The vehicle armor segment is the fastest growing market and is projected to grow with a CAGR of 7.00% during the forecast period. Ongoing conflicts and political instability, coupled with increasing threats to convoys, transport, and critical infrastructure, are pushing demand for armored commercial vehicles across various regions, with heightened demand for armored vehicles ensuring the safety of military personnel, diplomats, and humanitarian workers.
By Material Type, composites dominated the ballistic protection market, while ceramics is the fastest-growing segment.
The composites sub-segment held a share of 31.00% in the global ballistic protection market in 2025. The composites segment will continue to be the most popular segment on account of their high strength-to-weight ratio and flexibility in use in various applications ranging from personal protection to armored vehicles and infrastructure.
The ceramics segment is the fastest growing market and is projected to grow with a CAGR of 7.50% during the forecast period. Materials such as alumina, boron carbide, and silicon carbide ensure superior hardness and impact resistance, making them ideal for stopping high-velocity projectiles, a major growth driver for their usage in vehicle armoring and personal protection armor across increasingly demanding threat environments.
By Application, land/ground forces dominated the ballistic protection market, while naval & marine platform is the fastest-growing segment.
The land/ground forces segment dominated the ballistic protection market with a revenue share of 44.60% in 2025. Land and ground forces applications remain the dominant category owing to the substantial scale of global ground troop deployment requiring personal protective equipment, vehicle armor, and fixed infrastructure protection across the majority of conventional military and homeland security operations worldwide.
The naval and marine platform segment will register the highest CAGR of 7.60% during the forecast period. Increased naval fleets’ modernization projects and increased need for ballistic protection in ship hulls and bridges will fuel segment growth as more navies focus on enhancing their survivability in modernization projects of their fleets.
By End User, military dominated the ballistic protection market, while homeland security is the fastest-growing segment.
The military segment held the largest share of the ballistic protection market in 2025. Military end users remain the dominant category owing to sustained global defense modernization spending and the fundamental role ballistic protection plays in safeguarding personnel, vehicles, and infrastructure across combat and peacekeeping operations, representing the foundational and most substantial ballistic protection procurement channel worldwide.
The homeland security segment is expected to register the fastest CAGR of 6.80% during the forecast period 2026-2035. Law enforcement units are expanding community protection programs by deploying portable ballistic gear for rapid response units, while rising terrorist and extremist activity concerns continue driving increased procurement of advanced protective equipment across domestic security agencies worldwide.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|---|---|---|
|
North America |
United States |
85.00% |
|
Europe |
United Kingdom |
27.60% |
|
Asia Pacific |
China |
44.60% |
|
Middle East & Africa |
UAE |
26.80% |
|
Latin America |
Brazil |
37.70% |
North America Ballistic Protection Market Insights
North America's ballistic protection market accounts for a considerable portion of global revenues owing to the presence of state-of-the-art defense infrastructure as well as high-level procurement activities from military, homeland security, and law enforcement organizations committed to innovation along the region's ballistic protection value chain.
The US was the leading country within the North America ballistic protection market in 2025, driven by sustained defense modernization spending and growing law enforcement community protection program expansion. Canada is contributing to regional growth through its own expanding defense procurement and domestic ballistic protection manufacturing investment.
Get Customized Report as per Your Business Requirement - Enquiry Now
Europe Ballistic Protection Market Insights
The ballistic protection industry of Europe is among the prominent regions in 2025. This is because of several reasons including heavy investments in defense modernization of the region, presence of major manufacturers of ballistic protection products, and increasing procurement standards for NATO.
The United Kingdom is forecast to post steady growth, driven by requirement-led upgrades within British Armed Forces and strategic law enforcement units. Lightweight ballistic protection kits and discreet wearables are gaining priority due to evolving counterterrorism tactics, though procurement cycles remain conservative, shaped by budgetary scrutiny across the region's defense agencies.
Asia Pacific Ballistic Protection Market Insights
China's ballistic protection market is forecast to grow at a CAGR of 7.60% from 2025 to 2035, outperforming the global benchmark by 36%, positioning the broader Asia Pacific region as the fastest-growing market during the forecast period, demand driven by increasing domestic military output and central procurement mandates.
China is one of the main growth drivers in the Asia Pacific ballistic protection market, owing to increasing domestic military output and central procurement mandates. India and South Korea are also contributing to regional growth through expanding defense modernization programs and rising domestic ballistic protection manufacturing investment across the region's rapidly growing defense industrial base.
Middle East & Africa and Latin America Ballistic Protection Market Insights
Middle East & Africa and Latin American regions are gradually expanding ballistic protection adoption as defense modernization investment grows across both regions, supported by increasing regional conflicts and rising geopolitical tension driving procurement.
Brazil is set to be a prominent Latin American market fueled by rising geopolitical tensions and massive defense spending due to internal conflicts and tensions. The Middle East & Africa region has UAE and Saudi Arabia investing heavily in advanced military and homeland security infrastructure as part of broader defense modernization strategies supporting the region's expanding ballistic protection procurement programs.
Market Dynamics
Growth Drivers: Rising geopolitical instability and defense modernization driving market growth
Due to increasing instability in geopolitics and increasing conflicts, there has been a need for ballistic protection in the defense and military industry. With the ongoing process of military modernization of various countries in order to counter new threats, there has been a need for protection equipment for soldiers and other individuals fighting in the battlegrounds, along with many nations modernizing their defense systems.
Increasing government spending in strengthening the defense sector, increasing conflicts between countries, and rising terrorist and extremist activities continue to primarily drive market growth. Rising demand for lightweight, modular, and multi-threat protection systems, growing civilian and commercial adoption across public infrastructure, and increasing procurement by defense and security agencies worldwide are further supporting demand across the forecast period.
Restraints: High production costs and material scarcity limiting market expansion
One of the biggest hindrances to market expansion is the cost of production related to ballistic materials with higher performance levels, especially ceramics and composites that need special methods of production, limiting their use by smaller law enforcement agencies and commercial customers with constrained procurement budgets.
Moreover, heavy ballistics protection lowers mobility, which is an important issue that may impact future demand from customers looking for lighter and more mobile protective gear for use in the field. The limited availability of the raw material needed, such as specialty aramid fiber and advanced ceramic, adds another level of supply risk for companies expanding their production capacity.
Opportunities: Expansion of civilian adoption and smart technology integration creating new growth avenues
Lightweight bulletproof vests are being increasingly adopted, presenting enormous income possibilities for the target market entities, owing to the constant advancement in the field of material science, which resolves the mobility and comfort issues that were previously restricting the widespread use of such protective gear.
In this respect, there is huge potential for further development of smart sensors and communications technology that would improve situational awareness and increase safety of users in their bulletproof vests. In addition, it seems that the increase in civilian, public and commercial usage of ballistic protection products in developing regions of Asia Pacific and Latin America would be highly beneficial in terms of market growth.
Recent Developments:
- 2025: Point Blank Enterprises launched an updated lightweight ballistic vest platform, offering law enforcement and military customers improved mobility without compromising multi-threat protection performance.
- 2025: Honeywell expanded its Spectra Shield ballistic fiber production capacity, strengthening its ability to supply high-performance materials to body armor and vehicle armor manufacturers globally.
- 2026: BAE Systems launched an updated modular vehicle armor system, offering defense customers scalable protection levels adaptable to varying threat environments across different mission profiles.
- 2026: Safariland introduced a new multi-threat body armor plate, combining ballistic and stab protection capabilities for law enforcement customers facing increasingly diverse operational threats.
Ballistic Protection Market key players are:
- BAE Systems plc
- Honeywell International, Inc.
- E.I. du Pont de Nemours and Company (DuPont)
- Royal TenCate NV (Avient)
- Teijin Aramid B.V.
- Safariland, LLC
- Point Blank Enterprises, Inc.
- 3M Company
- Elmon S.A.
- Ceradyne, Inc. (3M)
- Survitec Group Limited
- Rheinmetall AG
- Craig International Ballistics Pty Ltd.
- MKU Limited
- Armorworks Enterprises, LLC
- Premier Armor Solutions
- Angel Armor, LLC
- National Molding, LLC (Safariland Group)
- Hesco Bastion Limited
- DSM Protective Materials (Avient)
Ballistic Protection Market Report Scope :
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 16.20 Billion |
| Market Size by 2035 | USD 27.90 Billion |
| CAGR | CAGR of 5.60% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Product Type (Spall & Fragmentation Protection, Vehicle Armor, Structural & Fixed Infrastructure) • By Material Type (Composites, Ceramics, Aramid Fiber, Metals) • By Application (Land/Ground Forces, Naval & Marine Platform, Aerial Platform) • By End User (Military, Homeland Security, Commercial) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | BAE Systems plc, Honeywell International, Inc., E.I. du Pont de Nemours and Company (DuPont), Royal TenCate NV (Avient), Teijin Aramid B.V., Safariland, LLC, Point Blank Enterprises, Inc., 3M Company, Elmon S.A., Ceradyne, Inc. (3M), Survitec Group Limited, Rheinmetall AG, Craig International Ballistics Pty Ltd., MKU Limited, Armorworks Enterprises, LLC, Premier Armor Solutions, Angel Armor, LLC, National Molding, LLC (Safariland Group), Hesco Bastion Limited, DSM Protective Materials (Avient). |
Frequently Asked Questions
The Ballistic Protection Market is expected to grow at a CAGR of 5.60% from 2026 to 2035.
The Ballistic Protection Market was valued at USD 16.20 Billion in 2025.
The market is driven by escalating geopolitical instability and regional conflicts heightening the need for advanced ballistic protection in the defense and military sectors.
The Military segment held the largest share of the Ballistic Protection Market in 2025.
The North America region dominated the Ballistic Protection Market in 2025.
