
Battery Packaging Market Report Scope & Overview
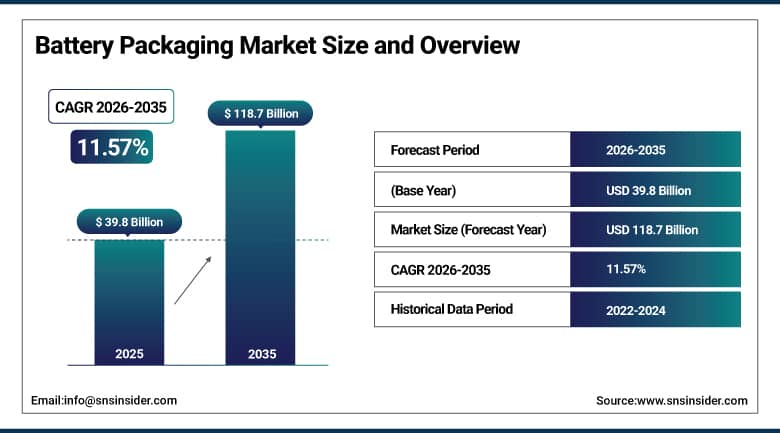
The Battery Packaging Market size was valued at USD 39.8 billion in 2025 and is expected to reach USD 118.7 billion by 2035, growing at a CAGR of 11.57% from 2026–2035.
The battery packaging refers to the type of packaging materials used to protect the batteries against various hazards such as mechanical damage, thermal abuse, moisture, and chemical exposure. With the rapid development of electric vehicles and the increasing importance of energy storage in maintaining the stability of the grid as well as incorporating renewable energies into the grid, there has been growing interest in high-performance packaging technologies of batteries by manufacturers, car makers, and energy companies. The development of batteries with high energy density, such as lithium iron phosphate batteries and solid-state batteries, has resulted in an increased need for better packaging materials.
Global battery demand surpassed 1.5 TWh in 2025, increasing by more than 35% year-over-year, while battery storage emerged as a major source of demand growth. EV battery deployment alone reached 1.2 TWh, up nearly 30%, supporting continued demand for advanced protective packaging solutions.
To Get More Information On Battery Packaging Market - Request Free Sample Report
Battery Packaging Market Trends
-
The quick growth of electric vehicle manufacturing all around the globe is resulting in increased demand for superior battery packaging that is made out of various materials and has different designs to accommodate large lithium-ion battery production and logistics needs.
-
The rising number of environmental laws and sustainable practices is fostering the use of environmentally friendly, lightweight, and reusable materials for battery packaging since more companies want to decrease their use of plastic.
-
Faster growth in battery technology and safety standards is fueling demand for battery packaging that can help maintain the optimal temperature of battery cells and improve their overall lifespan.
-
The increasing trend in the usage of prismatic and pouch battery cells for EVs is redefining the battery packaging needs because of their high space utilization, lightweight, and energy density advantages over cylindrical batteries.
-
Battery cell designs based on the cell-to-pack or cell-to-chassis concepts are changing the packaging needs due to their high efficiency and reduced use of battery modules.
-
Manufacturers have begun to develop sophisticated packing materials for lithium-ion batteries with the use of cardboard and fiber to transport batteries safely according to the rules of sustainability and dangerous goods transportation laws.
-
With the increasing usage of large energy batteries for storage purposes to integrate renewable energy, there is an ever-growing demand for better packaging for batteries.
U.S. Battery Packaging Market Outlook
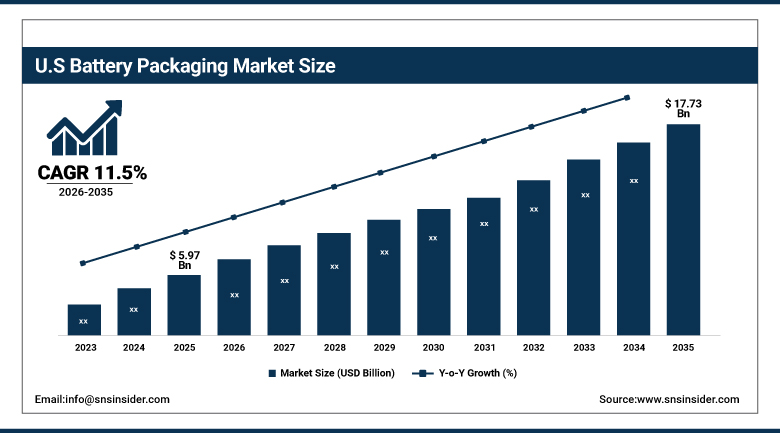
The U.S. Battery Packaging Market was valued at USD 5.97 billion in 2025 and is expected to reach USD 17.73 billion by 2035, growing at a CAGR of 11.5% from 2026 to 2035.
The U.S. battery packaging industry is being propelled by the fast-paced development of electric vehicle manufacturing in the country, significant capital allocation towards building battery gigafactories, and the booming grid-scale energy storage industry. The Inflation Reduction Act has boosted EV manufacturing and battery manufacturing in the country, generating strong demand for packaging materials and solutions. Giants such as Tesla, General Motors, and Ford are establishing battery manufacturing facilities in the U.S., which will need large amounts of packaging materials.
The U.S. battery manufacturing base continues to expand rapidly, with the U.S. Department of Energy reporting more than $150 billion in announced private investment across the domestic battery supply chain since 2021. In addition, U.S. battery cell and module manufacturing capacity reached approximately 200 GWh annually, strengthening demand for protective packaging, containers, trays, films, and other battery packaging solutions.
Battery Packaging Market Segment Analysis
-
By Material, the Cardboard/Paperboard segment dominated the Battery Packaging Market with approximately 61.23% share in 2025, while the segment is expected to grow at a CAGR of approximately 10.84% during 2026–2035.
-
By Casing Type, the Cylindrical segment dominated the Battery Packaging Market with approximately 55.28% share in 2025, while the Prismatic segment is the fastest growing with a CAGR of approximately 13.26% during 2026–2035.
-
By Packaging Type, the Cell & Pack Packaging segment dominated the Battery Packaging Market with approximately 63.38% share in 2025, while the segment is expected to grow at a CAGR of approximately 11.72% during 2026–2035.
-
By Battery Type, the Lithium-Ion segment dominated the Battery Packaging Market with approximately 39.65% share in 2025, while the Lead Acid segment is the fastest growing with a CAGR of approximately 12.38% during 2026–2035.
-
By End Use, Electric Vehicles dominated the Battery Packaging Market in 2025 and are also the fastest-growing end-use segment, with a CAGR of approximately 14.18% during 2026–2035.
By Material, Cardboard Leads for Sustainability, Metal Critical for EVs
The Cardboard/Paperboard segment dominated the Battery Packaging Market in 2025, supported by its cost-effectiveness, lightweight characteristics, recyclability, and suitability for consumer and small-format battery packaging. Manufacturers are increasingly adopting paper-based packaging as sustainability requirements and environmental awareness influence packaging decisions across the battery industry. Cardboard and paperboard also offer flexibility in printing, branding, handling, and transportation, making them suitable for a wide range of retail battery products. Growing pressure to reduce plastic consumption and improve packaging recyclability is further supporting demand for fiber-based materials, particularly in consumer electronics and portable battery applications.
The segment is expected to maintain steady growth as battery manufacturers and packaging suppliers continue transitioning toward environmentally responsible materials. Increasing regulatory emphasis on recyclable packaging and corporate sustainability commitments are encouraging the development of lightweight paper-based packaging with improved strength and protective performance. However, the rapid expansion of electric vehicle and energy storage batteries is also creating opportunities for advanced packaging materials designed to provide greater mechanical protection and thermal resistance. This is encouraging innovation across paperboard, polymer, metal, and composite packaging solutions to address the diverse requirements of modern battery systems.
By Casing Type, Cylindrical Largest, Prismatic Fastest Growing
The Cylindrical segment dominated the Battery Packaging Market in 2025, supported by its established use across consumer electronics, power tools, electric vehicles, and energy storage applications. Cylindrical battery cells offer advantages such as standardized dimensions, mechanical stability, efficient automated manufacturing, and consistent production quality. Their established manufacturing ecosystem and widespread availability of mature cell formats continue to support demand for cylindrical battery packaging. The increasing production of cylindrical lithium-ion cells for automotive applications is further strengthening the segment's position, particularly as battery manufacturers scale high-volume production facilities.
The Prismatic segment is the fastest growing, driven by increasing adoption in electric vehicles and stationary energy storage systems. Prismatic cells can provide efficient space utilization and flexible packaging configurations, making them attractive for applications where battery pack design and energy density are important considerations. Automakers and battery manufacturers are increasingly evaluating prismatic formats for large battery packs, particularly as EV platforms evolve toward higher capacity and improved packaging efficiency. Continued investment in battery gigafactories, cell manufacturing automation, and next-generation battery technologies is expected to create additional demand for specialized prismatic casing and packaging solutions.
By End-Use: Electric Vehicles Dominate Growth
The Cell & Pack Packaging segment dominated the Battery Packaging Market in 2025, reflecting the large-scale requirement for packaging solutions at both individual cell and assembled battery-pack levels. Battery cells and packs require protective structures capable of managing mechanical stress, vibration, moisture, heat, and other environmental factors during manufacturing, transportation, and operation. Increasing battery production across electric vehicles, consumer electronics, industrial equipment, and energy storage systems is consequently generating substantial demand for cell and pack packaging. The growing complexity of battery assemblies is also encouraging manufacturers to invest in packaging solutions that integrate structural protection, thermal management, and safety features.
The segment is expected to expand in line with global battery manufacturing volumes and the increasing deployment of lithium-ion batteries across multiple industries. Electric vehicle manufacturers are particularly increasing requirements for lightweight yet durable battery enclosures and protective packaging systems. At the same time, grid-scale energy storage installations require robust packaging capable of supporting large battery modules and ensuring safe handling and transportation. Advances in materials, modular packaging designs, thermal barriers, and fire-resistant structures are creating additional opportunities for suppliers. The continued expansion of battery manufacturing capacity is therefore expected to remain a key source of demand.
Regional Analysis
|
Region |
Major Country |
Share within Region 2025 (%) |
|---|---|---|
|
North America |
United States |
75.00% |
|
Europe |
Germany |
32.00% |
|
Asia Pacific |
China |
52.00% |
|
Middle East & Africa |
UAE |
35.00% |
|
Latin America |
Brazil |
50.00% |
North America Battery Packaging Market Insights
The North American region captured about 20% of the global Battery Packaging Market’s revenue share in 2025, with significant contributions from the United States. The high demand for electric vehicles in the domestic market, driven by financial incentives as per the Inflation Reduction Act (IRA), is contributing towards the fast-growing supply chain of the battery packaging industry in the region. The growing investments in gigafactories of companies like Panasonic Corporation, Samsung SDI, and LG Energy Solution, coupled with rising investments from automotive companies in the country, are contributing to increased demands for advanced battery packaging products and thermal protection solutions. Moreover, the growing popularity of energy storage projects in various states like California and Texas is boosting demand for safe packaging materials for lithium-ion batteries.
Europe Battery Packaging Market Insights
Europe is a prominent and continuously increasing segment of the worldwide Battery Packaging Market due to its robust goals regarding electric vehicle usage and investment in batteries' manufacture within the region. Several countries, such as Germany, France, Sweden, and Poland, are now rising to become prominent producers and suppliers of batteries due to their ongoing development of gigafactories and environmental-friendly energy programs backed by governments. Furthermore, the European Battery Alliance, along with other EU sustainability policies, is driving up the demand for battery packaging products within Europe. Moreover, stringent European Union policies concerning recyclable batteries, carbon emissions, hazardous substance management, and sustainable materials for battery packaging encourage the development of innovative battery packaging technologies.
Asia Pacific Battery Packaging Market Insights
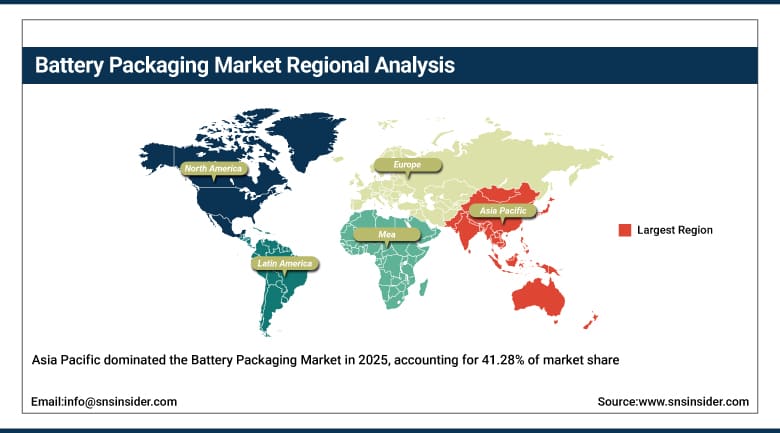
The Asia Pacific region emerged as the key contributor to the Global Battery Packaging Market in 2025, contributing about 41.28% of the overall market revenue. Some of the prominent regional markets that contribute to the growth of the industry include China, Japan, South Korea, and India. China currently leads as the largest producer of batteries in the world, owing to the widespread manufacture of electric vehicles, increasing energy storage installations, and an extensive network for producing lithium-ion batteries, thereby becoming the largest market for battery packaging products. On the other hand, South Korea hosts leading battery manufacturers like Samsung SDI, LG Energy Solution, and SK On. The export of batteries and collaborations with EV makers have created significant opportunities for the market in the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
MEA and Latin America Battery Packaging Market Insights
Energy storage has become an area of focus in the Middle East for grid stability and for use with renewable energy sources, increasing the demand for battery packaging products. Saudi Arabia has its Vision 2030 initiative related to energy, while the UAE has plans to develop clean energy that increases the use of batteries. Africa is in an early stage of development for the battery packaging market, with some projects involving solar energy combined with storage in remote areas and for businesses.
The Latin American region is expected to grow as well, being one of the emerging markets in this industry. In Brazil there is great potential for renewable energy, and with more installations, there will be a need for batteries. In Mexico, there is a strong automobile industry and especially electric vehicle production, hence, the need for battery packages.
Market Dynamics
Growth Drivers: Electric vehicle adoption and energy storage investment are transforming the market
The global shift away from the use of fossil fuels is at the heart of the growth in demand for battery packaging. The production of EVs is rising from several million units per year to tens of millions over the forecast horizon, and each car will need a battery system with proper packaging. Additionally, there is increasing demand for batteries in renewable energy applications. Both trends represent demand drivers that are structural in nature and will continue despite short-term changes in economic conditions.
Policy action is one of the biggest catalysts for such demand. The Inflation Reduction Act in the U.S., the European Union's Battery Regulation, and China's NEV policies provide strong financial support and mandates that result in increased demand for electric vehicles and their batteries. Every dollar spent on EV subsidies through policy results in higher demand for battery packaging.
Restraints: Supply chain complexity and raw material price volatility create cost pressure
In terms of battery packaging, many types of materials may be needed, which include engineering plastics, aluminum, steel, and films. The procurement of these materials is not simple and can be influenced by some political developments, trade sanctions, or any shortages of these materials. Changes in aluminum and engineering plastics prices will affect the costs related to packaging. Battery manufacturers that are cost-oriented would find this difficult to manage.
Opportunities: Next-generation battery formats and solid-state batteries require new packaging solutions
As technology moves towards advanced batteries such as solid-state batteries, there will be a considerable change in the demands made on the packaging system. Solid-state batteries function under much higher pressure and temperature ranges compared to liquid electrolytes and demand more precise mechanical contact between the layers of the cell. This opens up possibilities for innovative packaging design that can meet the needs of advanced batteries. Firms who innovate in solid-state battery packaging will enjoy early market entry into the space.
Recent Developments
-
2026: The CATL battery system called "Kirin Battery" was introduced, which consisted of cell-to-pack batteries having superior thermal management packaging that could also function as a structural element for the vehicles, thus saving the need for packaging modules separately. This design also allowed more energy efficiency, with a 13% improvement over previous models.
-
2026: The Nefab Group introduced battery packaging solutions for North America's electric vehicles with the opening of its advanced engineering center in Mexico dedicated to designing lithium-ion battery packaging.
-
2025: Energizer Holdings introduced new battery packaging solutions that were completely recyclable and plastic-free.
Battery Packaging Market Key Players
-
DS Smith Plc
-
Smurfit Kappa Group
-
Sealed Air Corporation
-
Integer Holdings Corporation
-
Tekni-Plex Inc.
-
BASF SE
-
Crown Holdings Inc.
-
EnerSys
-
Nefab Group
-
Schoeller Allibert
-
UFP Technologies Inc.
-
Sonoco Products Company
-
ZARGES GmbH
-
East Penn Manufacturing
-
Exide Technologies
-
Bollore Group
-
Elkem ASA
-
Sigma Lithium Corporation
Battery Packaging Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 39.8 Billion |
| Market Size by 2035 | USD 118.7 Billion |
| CAGR | CAGR of 11.57% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Material (Cardboard/Paperboard, Plastic, Metal, Others) • By Casing Type (Cylindrical, Prismatic, Pouch) • By Packaging Type (Cell & Pack Packaging, Module Packaging, Battery Management System Packaging) • By Battery Type (Lithium-Ion, Lead Acid, Lithium Iron Phosphate, Nickel-Based, Others) • By End-Use (Electric Vehicles, Consumer Electronics, Energy Storage Systems, Industrial, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Amcor Plc, DS Smith Plc, Smurfit Kappa Group, Sealed Air Corporation, Integer Holdings Corporation, Tekni-Plex Inc., Evonik Industries AG, BASF SE, Crown Holdings Inc., EnerSys, Nefab Group, Schoeller Allibert, UFP Technologies Inc., Sonoco Products Company, ZARGES GmbH, East Penn Manufacturing, Exide Technologies, Bollore Group, Elkem ASA, Sigma Lithium Corporation |
Frequently Asked Questions
Key players in the Battery Packaging Market include Amcor Plc, DS Smith Plc, Smurfit Kappa Group, Sealed Air Corporation, Nefab Group, BASF SE, Crown Holdings Inc., EnerSys, Sonoco Products Company, and UFP Technologies Inc.
Key opportunities include the development of sustainable and recyclable packaging, advanced thermal-management solutions, lightweight materials, modular battery packaging, and packaging solutions for next-generation and solid-state batteries.
The major growth factors are the rapid expansion of electric vehicle production and increasing investment in grid-scale energy storage systems.
By material, Cardboard/Paperboard dominated the market with approximately 61.23% share in 2025. By casing type, Cylindrical held the largest share at 55.28%, while Cell & Pack Packaging led by packaging type with 63.38%. Lithium-Ion accounted for 39.65% of the battery-type segment. Electric Vehicles represent the largest and fastest-growing end-use segment.
Asia Pacific dominated the Battery Packaging Market with approximately 41.28% of global revenue share in 2025, supported by strong battery manufacturing capacity and the expanding electric vehicle
