
Food Processing Seals Market Report Scope & Overview:
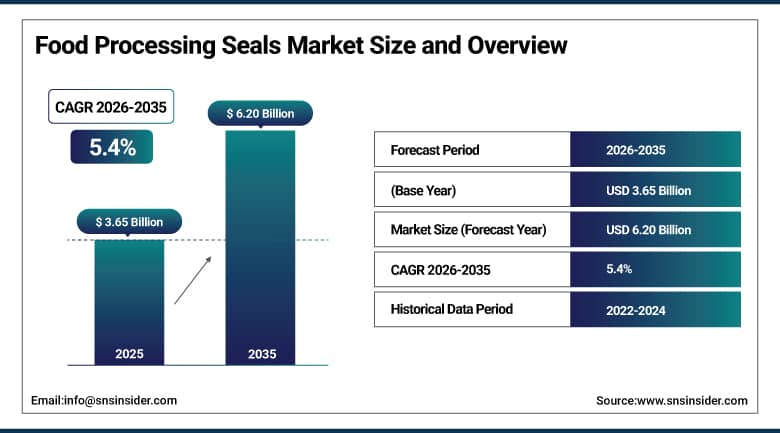
The Food Processing Seals Market was valued at USD 3.65 Billion in 2025 and is expected to reach USD 6.20 Billion by 2035, growing at a CAGR of 5.4% from 2026–2035.
The Food Processing Seals Market is registering steady growth due to the growing requirement of hygiene, durability, and high performance in sealing applications in food processing and packaging machines. The rising consumption of processed, packaged, and convenience foods in the world is motivating the companies to increase their production capacity and use modern facilities for the processing of foods. Growing regulations for food safety and hygiene are contributing towards the adoption of food grade sealing products that comply with the regulations. Besides this, the growing automation in food processing industries is generating the demand for seals that can operate in harsh conditions. Growing industries of dairy, beverages, bakery, meat, poultry, seafood, and fruits and vegetables processing are also favoring market growth.
Trelleborg Sealing Solutions has been racing to replace PFAS-based fluoropolymers across its FoodPro material range with alternatives like its Isolast FFKM line, expected to reach commercial availability in 2025, without sacrificing the chemical resistance and sterilization tolerance that food and beverage processors depend on.
To Get More Information On Food Processing Seals Market - Request Free Sample Report
Food Processing Seals Market Trends
-
PFAS restrictions are reshaping material choices across the industry, pushing manufacturers to develop fluorine-free elastomer compounds, including EPDM and HNBR formulations, as regulators tighten availability of PTFE-based sealing materials.
-
Rising compliance costs and automation-led equipment upgrades are shifting demand away from commoditized gaskets toward higher-value, precision-engineered sealing solutions built for automated, high-speed production lines.
-
Metal- and X-ray-detectable particles are being integrated into a growing share of newly developed elastomer seals, letting processors catch a failed or fragmented seal before it contaminates a batch rather than after the fact.
-
Automated bakery and confectionery operations continue driving demand for seals that can withstand caustic wash-down chemicals and the constant motion stress of high-speed rotary and linear equipment.
-
Traceability and food safety documentation requirements are pushing processors toward seal suppliers who can provide detailed material compliance records alongside the physical product itself.
U.S. Food Processing Seals Market Outlook
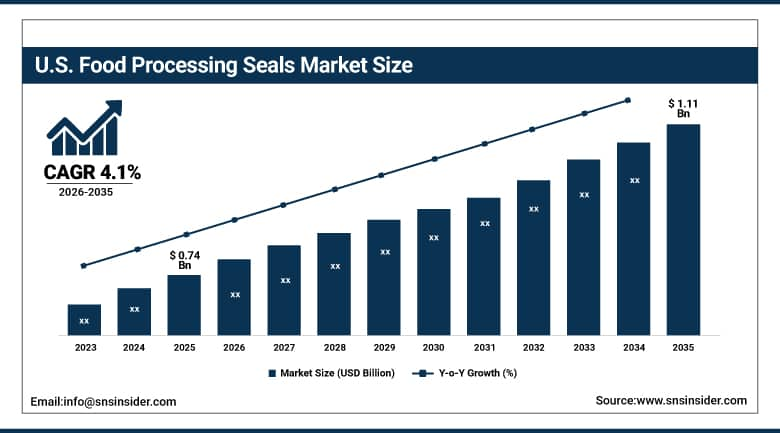
The U.S. Food Processing Seals Market was valued at approximately USD 0.74 Billion in 2025 and is expected to reach approximately USD 1.11 Billion by 2035, growing at a CAGR of approximately 4.1%.
Demand in the United States is shaped by a large, mature food and beverage processing industry alongside strict FDA and USDA material compliance requirements that govern what can legally touch food during production. Meat, poultry, and dairy processing represent a substantial share of domestic sealing demand, given the scale of those industries and the rigorous sanitation protocols they run. A handful of long-established American seal manufacturers, several with roots stretching back more than a century, continue to hold deep, multi-generational customer relationships with domestic food processors that newer entrants have struggled to displace.
A.W. Chesterton Company, a Massachusetts-based seal manufacturer with roots stretching back to 1895, continues expanding its AXIUS platform of mechanical seals, engineered for the kind of foreign-object-detectable, X-ray-inspectable construction that food and beverage processors increasingly specify to satisfy contamination-control audits. The company's century-long history serving the U.S. industrial sealing market gives it particularly deep customer relationships with domestic food and beverage processors upgrading legacy equipment.
Food Processing Seals Market Segment Analysis
-
By Seal Type, the O-Rings segment dominated the Food Processing Seals Market with approximately 34.0% share in 2025, while the Mechanical Seals segment is the fastest growing with a CAGR of approximately 6.8%.
-
By Material Type, the Elastomers segment dominated the Food Processing Seals Market with approximately 57.0% share in 2025, while the Face Materials segment is the fastest growing with a CAGR of approximately 7.2%.
-
By Application, the Processing Equipment segment dominated the Food Processing Seals Market with approximately 58.0% share in 2025, while the Packaging Equipment segment is the fastest growing with a CAGR of approximately 6.6%.
-
By End-User Industry, the Meat, Poultry & Seafood segment dominated the Food Processing Seals Market with approximately 26.6% share in 2025, while the Bakery & Confectionery segment is the fastest growing with a CAGR of approximately 6.9%.
By Seal Type, O-rings dominate, mechanical seals grow fastest
O-rings held the largest share of the seal-type segment in 2025, valued for their simple, reliable design and broad compatibility across the huge range of pumps, valves, and fittings found on a typical food processing line. Their comparatively low cost and ease of replacement during routine maintenance keep O-rings the default choice for the majority of sealing points on most equipment.
Mechanical seals are growing fastest as automation-led equipment upgrades push processors toward higher-value, precision-engineered sealing solutions capable of handling the demands of continuous, high-speed rotating equipment like pumps and mixers. Their more sophisticated design better tolerates the constant mechanical stress and cleaning-cycle exposure that automated production lines put seals through, justifying the higher upfront cost relative to simpler O-ring designs.
By Material Type, elastomers dominate, face materials grow fastest
Elastomer was leading the type of material segment in 2025, as it provided chemical resistance, flexibility, and fast and cost-effective replacement compared to metals and specialized face materials. Resistance to water, oil, grease, acids, and alcohols make elastomer a sensible choice across almost all food processing environments which require wet and chemical resistance.
Face material segment is expected to be the fastest growing segments due to increasing demand for mechanical seals with low friction, abrasion resistance, and purity, which is essential in bakery and confectionary processing equipment, where sealing materials should not degrade under influence of sticky products and aggressive cleaning chemicals.
By Application, processing equipment dominates, packaging equipment grows fastest
Processing equipment accounted for the largest application share in 2025, spanning the pumps, valves, mixers, and homogenizers where food product itself passes directly through sealed components. The sheer number of individual sealing points across a typical processing line, combined with the direct product contact each one involves, keeps this the largest and most safety-critical application category.
Packaging equipment is the fastest-growing application as automation continues expanding across filling, capping, and wrapping lines that require reliable, food-safe seals of their own to maintain hygienic operation. Rising investment in high-speed, automated packaging infrastructure across the food industry is pulling sealing demand into this category faster than the more mature processing equipment segment is growing.
By End-User Industry, meat, poultry & seafood dominates, bakery & confectionery grows fastest
Meat, poultry, and seafood processing accounted for the largest end-user share in 2025, reflecting both the scale of global protein production and the especially rigorous sanitary sealing standards this category demands given its high contamination risk. Frequent equipment wash-down cycles in these facilities also drive a faster seal replacement cadence than most other food categories require.
Bakery and confectionery is the fastest-growing end-user industry as automated, high-speed rotary and linear production equipment continues expanding across this category, along with growing adoption of Clean-in-Place systems that expose seals to caustic cleaning chemicals and aggressive wash-down procedures. That combination of mechanical stress and chemical exposure is driving a steady, above-average replacement cycle that keeps this end-user industry growing faster than the broader market.
Regional Analysis
|
Region |
Major Country |
Share within Region, 2025 (%) |
|
Asia Pacific |
China |
38.0% |
|
North America |
United States |
78.0% |
|
Europe |
Germany |
24.0% |
|
Latin America |
Brazil |
37.0% |
|
Middle East & Africa |
Saudi Arabia |
29.0% |
Asia Pacific Food Processing Seals Market Insights
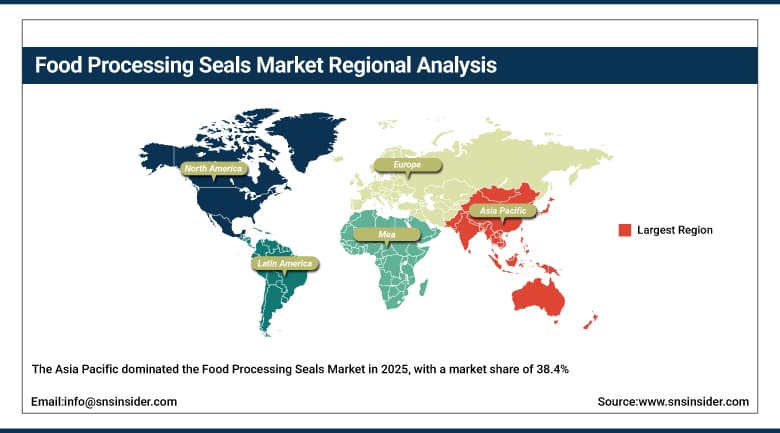
The Asia Pacific dominated the Food Processing Seals Market in 2025, with a market share of 38.4%, and is expected to grow at the fastest pace till 2035. The high population of the region, along with rising disposable income and increased consumption of processed food, is contributing towards the demand for better food processing machines and seals. The region is making its mark in the food processing seals market due to rapid growth of organized food manufacturing in the countries like China, India, Japan, and Southeast Asia, which are investing heavily in automation and food safety.
The large food processing industry in China makes the base demand of the region, whereas India’s rising organized food market and export-oriented food processing are bringing a lot of value addition to the regional demand. Japan and South Korea are well-established markets, while Southeast Asian markets follow the same trend as that of the region.
Get Customized Report as Per Your Business Requirement - Enquiry Now
North America Food Processing Seals Market Insights
North America is an important market for Food Processing Seals, wherein the US dominates regional demand owing to a vast meat, dairy, bakery, and beverages processing industry base. The stringency of regulations on FDA and USDA compliance affects sourcing and product choice. Such regulations benefit seal makers that possess knowledge about the regulations and are trusted by consumers for their products. Automation in food processing along with investments in hygiene and equipment is adding to rising demand for advanced sealing solutions in North America.
Canada's demand is driven by its food processing industry and exports, while Mexico's market is growing on the back of rising food manufacturing investment driven by nearshoring trends. Supply linkages between the countries make most of the demand in North America interconnected in terms of major seal manufacturers operating in all three markets.
Europe Food Processing Seals Market Insights
Europe is characterized as an experienced and regulated Food Processing Seals Market, driven by rigorous EU food contact materials standards, along with a developed food & beverages manufacturing industry. The market of Germany has been identified as a major one for the region, backed up by developed engineering in the country as well as seal manufacturers. An increased demand for hygiene, durability, and performance of seals in food processing and packaging machinery keeps stimulating the market growth. Investments in automation and food safety continue to boost market opportunities in Europe.
France, Italy, and the Netherlands also add significant volumes, owing to large production capacities of their dairy, beverages, and processed foods industries. Growing restrictions on PFAS and other materials of concern from the EU are making processors move towards fluorine-free seals more rapidly than elsewhere.
MEA & Latin America Food Processing Seals Market Insights
The Middle East and Africa represent a smaller but developing food processing seals market, with Saudi Arabia driving demand through growing food processing and beverage manufacturing investment tied to broader economic diversification goals. Growth elsewhere in the region remains tied closely to the pace of broader food manufacturing infrastructure development.
Latin America is a growing market led by Brazil, one of the world's largest food and protein exporters, where expanding meat processing and beverage manufacturing continue driving demand for sanitary sealing solutions. Mexico and Argentina contribute meaningful secondary demand, tied to their own substantial food processing and export industries.
Market Dynamics
Growth Drivers: Rising processed food demand and tightening sanitation standards fueling adoption
Growing global demand for processed and convenience foods is one of the clearest forces behind rising food processing seals demand, as expanding populations and rising disposable incomes across emerging markets push more consumers toward packaged rather than home-prepared food. That demand growth directly translates into more processing equipment, and every additional piece of equipment represents a fresh set of sealing points that need reliable protection.
Tightening sanitation and food safety regulation adds a second major driver, as government and industry standards worldwide push processors toward more rigorous equipment hygiene and contamination prevention. Seals sit at the center of this compliance burden, since a failed or degraded seal is one of the most common pathways for physical or chemical contamination to enter a food product.
Restraints: PFAS regulation and supply chain consistency limiting margin stability
Tightening PFAS regulation, while ultimately a positive development for food safety, has created real material availability and cost pressure for manufacturers who have historically relied on PTFE-based compounds for their chemical resistance and sterilization tolerance. Finding fluorine-free alternatives that match PFAS performance without compromising seal life is proving to be a genuinely difficult and costly engineering problem.
Supply chain consistency for food-grade polymers and specialty compounds adds a further restraint, since any disruption to specialty material availability can extend lead times and complicate production planning for both seal manufacturers and the food processors who depend on them. Competition from low-cost regional suppliers in commodity seal categories adds further margin pressure on manufacturers without a clear technical differentiation.
Opportunities: Fluorine-free material innovation and automation-driven upgrades opening new growth avenues
Fluorine-free elastomer innovation offers manufacturers a genuine path to capturing premium business from processors seeking to get ahead of tightening PFAS regulation before it becomes a hard compliance deadline. Companies that successfully develop compounds matching PFAS-level performance are positioned to capture significant new business as regulatory pressure continues building across major markets.
Automation-driven equipment upgrades across processing and packaging lines represent a second significant opportunity, as processors replace older, simpler sealing setups with more sophisticated, higher-value engineered solutions built for continuous high-speed operation. Manufacturers that build strong relationships with equipment original equipment manufacturers are positioned to capture this upgrade cycle as automation continues spreading across the food processing industry.
Recent Developments:
-
November 2025: Freudenberg Sealing Technologies presented certified, sustainable hygienic-design sealing solutions at drinktec 2025 in Munich, one of the food and beverage industry's largest global trade fairs.
-
November 2025: Freudenberg Sealing Technologies announced new sealing solutions developed without bisphenol AF, part of a broader push to remove substances of concern from materials used in food-contact and hygienic-design applications.
-
2025: Trelleborg Sealing Solutions continued expanding its FoodPro material range, which already spans standard elastomers alongside PTFE and polyethylene plastics engineered to withstand repeated Clean-in-Place and Sterilization-in-Place cycles.
-
2025: Multiple major sealing manufacturers accelerated development of fluorine-free elastomer compounds, including EPDM and HNBR formulations, as potential PFAS restrictions threaten to limit availability of PTFE-based sealing materials.
Food Processing Seals Market Key Players
-
Freudenberg Sealing Technologies GmbH & Co. KG
-
Trelleborg AB
-
Flowserve Corporation
-
Parker Hannifin Corporation
-
SKF Group
-
Smiths Group plc
-
AESSEAL plc
-
A.W. Chesterton Company
-
IDEX Corporation
-
EnPro Industries, Inc.
-
James Walker Group Ltd.
-
Meccanotecnica Umbra S.p.A.
-
EagleBurgmann GmbH & Co. KG
-
Garlock Sealing Technologies
-
John Crane
-
Klinger Group
-
CinchSeal LLC
-
Precision Associates, Inc.
-
Kismet Rubber Products LLC
-
Saint-Gobain S.A.
Food Processing Seals Market Report Scope:
| Report Attributes | Details |
|---|---|
| Market Size in 2025 | USD 3.65 Billion |
| Market Size by 2035 | USD 6.20 Billion |
| CAGR | CAGR of 5.4% From 2026 to 2035 |
| Base Year | 2025 |
| Forecast Period | 2026-2035 |
| Historical Data | 2022-2024 |
| Report Scope & Coverage | Market Size, Segments Analysis, Competitive Landscape, Regional Analysis, DROC & SWOT Analysis, Forecast Outlook |
| Key Segments | • By Seal Type (O-Rings, Gaskets, Lip Seals, Mechanical Seals, Magnetic Seals, Others) • By Material Type (Elastomers, Polyurethane, Metal, Face Materials, PTFE & Fluoropolymers, Others) • By Application (Processing Equipment, Packaging Equipment, Others) • By End-User Industry (Meat, Poultry & Seafood, Bakery & Confectionery, Dairy, Beverages, Fruits & Vegetables, Others) |
| Regional Analysis/Coverage | North America (US, Canada), Europe (Germany, UK, France, Italy, Spain, Russia, Poland, Rest of Europe), Asia Pacific (China, India, Japan, South Korea, Australia, ASEAN Countries, Rest of Asia Pacific), Middle East & Africa (UAE, Saudi Arabia, Qatar, South Africa, Rest of Middle East & Africa), Latin America (Brazil, Argentina, Mexico, Colombia, Rest of Latin America). |
| Company Profiles | Freudenberg Sealing Technologies GmbH & Co. KG, Trelleborg AB, Flowserve Corporation, Parker Hannifin Corporation, SKF Group, Smiths Group plc, AESSEAL plc, A.W. Chesterton Company, IDEX Corporation, EnPro Industries, Inc., James Walker Group Ltd., Meccanotecnica Umbra S.p.A., EagleBurgmann GmbH & Co. KG, Garlock Sealing Technologies, John Crane, Klinger Group, CinchSeal LLC, Precision Associates, Inc., Kismet Rubber Products LLC, Saint-Gobain S.A. |
Frequently Asked Questions
Key players include Freudenberg Sealing Technologies, Trelleborg AB, Flowserve Corporation, Parker Hannifin Corporation, and SKF Group, among others.
Key opportunities include fluorine-free materials, contamination detection, automation-ready seals, sanitary processing, bakery automation, and expanding processed food production.
Growing global demand for processed and convenience foods combined with tightening sanitation and food safety regulation worldwide.
Asia Pacific dominated the Food Processing Seals Market in 2025 and is also the fastest-growing region.
